



- Automotive Components & Materials
- Automotive Brake Pad Market
Automotive Brake Pad Market Size, Share, and Growth Forecast, 2026 - 2033
Automotive Brake Pad Market by Material Type (Semi-Metallic, Ceramic, Non-Asbestos Organic, Low-Metallic NAO), Vehicle Type (Passenger Cars, Two-Wheelers, LCVs, HCVs), Sales Channel, Axle Position, and Regional Analysis for 2026 - 2033

Automotive Brake Pad Market Size and Trends Analysis
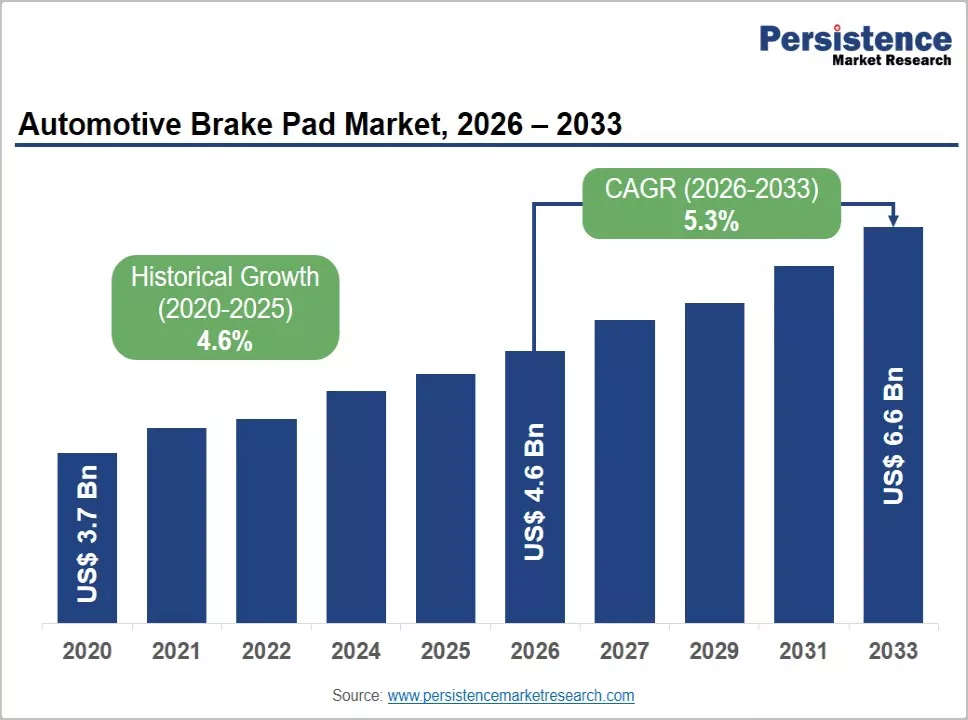
The global automotive brake pad market size is likely to be valued at US$4.6 billion in 2026 and is expected to reach US$6.6 billion by 2033, growing at a CAGR of 5.3% between 2026 and 2033. Market expansion is supported by rising global vehicle production, increasing demand for replacement brake components, and advancements in friction material technology.
Growing adoption of electric vehicles and stricter environmental requirements are also influencing brake pad manufacturing, particularly the development of low-dust and copper-free formulations.
Key Industry Highlights
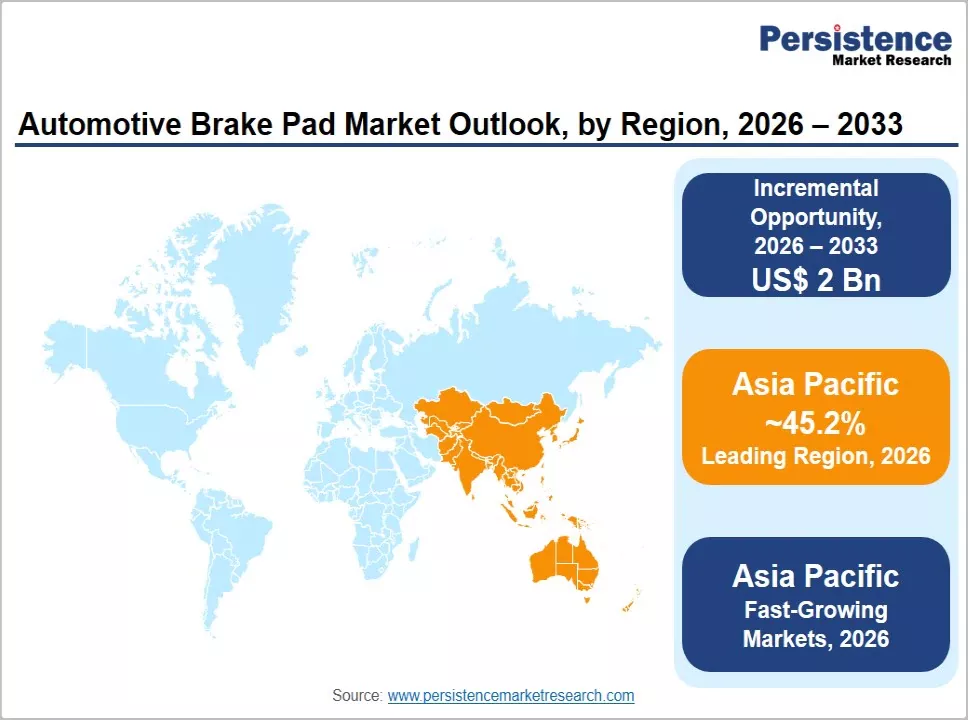
- Leading Region: Asia Pacific, anticipated to account for 45.2% of the market share, supported by large-scale automotive production, expanding vehicle ownership, and established automotive component manufacturing facilities.
- Fastest-growing Region: Asia Pacific, driven by rising two-wheeler and passenger vehicle production, expanding automotive aftermarket networks, and increasing demand for replacement braking components.
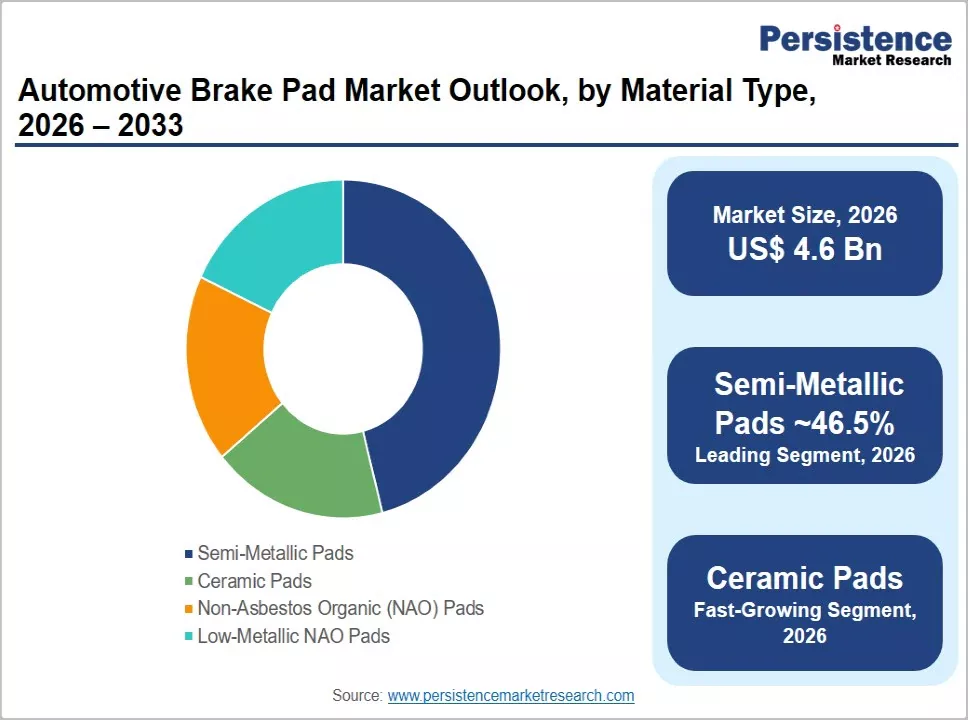
- Dominant Material Type: Semi-metallic brake pads, anticipated to account for 46.5% of the market share, supported by their braking performance, heat resistance, durability, and suitability across different vehicle categories.
- Leading Vehicle Type: Passenger cars, anticipated to hold 51.7% of the market share, driven by the large global passenger vehicle fleet and recurring demand for brake pad replacement.
DRO Analysis
Drivers – Increasing Global Vehicle Production and Expanding Vehicle Ownership Support Brake Pad Demand
Growth in global automotive production directly supports demand for brake pads through original equipment installations. According to the International Organization of Motor Vehicle Manufacturers, global vehicle production increased from 92.7 million units in 2024 to 96.4 million units in 2025, representing growth of 3.9%. Asia Oceania accounted for a substantial proportion of this production, with regional output reaching approximately 59.2 million vehicles in 2025. Rising production across passenger cars, commercial vehicles, and two-wheelers increases the requirement for braking components and creates additional demand for OEM brake pad suppliers.
The expansion of the global vehicle fleet also supports replacement demand. Brake pads experience friction-related wear during regular vehicle operation, making periodic inspection and replacement an essential part of vehicle maintenance. Urban traffic congestion, frequent braking, vehicle operating conditions, and commercial fleet utilization influence replacement frequency. The growing number of vehicles operating beyond their initial warranty periods further strengthens aftermarket demand. This combination of OEM installations and recurring replacement requirements provides a stable foundation for automotive brake pad consumption across developed and emerging automotive markets.
Technological Advancements and Environmental Regulations Are Transforming Brake Pad Materials
Automotive brake pad manufacturers are increasingly focusing on friction materials that combine braking efficiency, durability, reduced noise, and lower particulate emissions. The transition toward electric and hybrid vehicles is also influencing product development because braking systems in these vehicles operate alongside regenerative braking technologies. Manufacturers are developing friction compounds that maintain consistent braking performance while addressing vehicle-specific requirements, including additional vehicle weight and reduced friction brake usage in certain driving conditions.
Environmental regulations are accelerating material innovation. California's Motor Vehicle Brake Friction Material Law introduced progressively stricter restrictions on copper and other regulated substances. From January 1, 2025, the applicable copper threshold for covered brake friction materials is 0.5% by weight. These requirements are encouraging manufacturers to invest in alternative friction materials, copper-free formulations, and improved manufacturing processes. The resulting technological transition is strengthening demand for specialized brake pad products across OEM and aftermarket applications.
Restraint – Raw Material Costs and Manufacturing Complexity Affect Production Economics
Automotive brake pad manufacturing involves several material inputs, including steel, copper, iron, graphite, abrasives, friction modifiers, resins, and other compounds. Changes in the prices of metals, energy, transportation, and industrial chemicals influence manufacturing costs and supplier margins. Manufacturers also face additional expenditure associated with research, product testing, certification, and the development of alternative friction formulations. The transition toward copper-free and low-emission products adds complexity to material selection and performance validation. These cost pressures are particularly relevant for suppliers serving price-sensitive aftermarket markets, where competition from regional manufacturers and lower-priced replacement products places pressure on selling prices and production margins.
Opportunities – Development of Low-Emission and Copper-Free Brake Pad Technologies
The growing focus on environmental performance presents an important opportunity for automotive brake pad manufacturers. Regulations addressing brake wear particles and restricted substances are increasing interest in friction materials with lower environmental impact. The European Union's Euro 7 Regulation introduces limits for brake particle emissions, extending emissions-related requirements beyond conventional exhaust pollutants. For passenger cars and light commercial vehicles, the regulation establishes PM10 brake particle limits that vary by powertrain technology.
Manufacturers are responding through copper-free formulations, improved friction compounds, optimized pad and disc combinations, and technologies designed to reduce brake dust. Electric vehicles also represent an important application area because their braking systems require friction components compatible with regenerative braking. Suppliers developing low-dust and durable brake pads are positioned within an expanding product category that includes passenger vehicles, electric vehicles, and premium commercial applications.
Expansion of the Automotive Aftermarket Creates Replacement Product Opportunities
The automotive aftermarket represents a significant opportunity as brake pads are consumable safety components requiring periodic replacement. The growing number of vehicles operating across emerging economies is increasing demand for affordable and readily available replacement products. Independent repair shops, authorized service centers, parts distributors, and online automotive retailers are expanding access to brake pad products.
Category-wise Analysis
Material Type Insights
Semi-metallic brake pads are anticipated to account for 46.5% of the market share. These products combine metal fibers, friction modifiers, and other materials to provide braking performance, heat dissipation, and durability. Their established use across passenger cars, light commercial vehicles, and heavy-duty applications supports their leading position. Semi-metallic formulations are particularly relevant in applications requiring consistent braking under demanding operating conditions, including frequent braking, higher vehicle loads, and extended operating periods. Their established manufacturing processes and broad vehicle compatibility also support their availability through OEM suppliers and aftermarket distributors.
Ceramic brake pads represent the fastest-growing material category. Their growth is associated with lower brake dust, reduced noise, and suitability for passenger vehicles and premium automotive applications. Ceramic formulations are increasingly relevant among consumers seeking quieter braking and cleaner wheel surfaces. Manufacturers are also expanding product portfolios to address different vehicle models and driving requirements. Semi-metallic pads retain an advantage in applications prioritizing durability and heat management, while ceramic products are gaining traction in passenger vehicles where comfort and reduced dust generation influence replacement decisions.
Vehicle Type Insights
Passenger cars are anticipated to represent the leading vehicle category, accounting for 51.7% of the market share. Their leading position reflects the large passenger vehicle population and recurring maintenance requirements across private vehicles, fleet cars, SUVs, and premium automobiles. Passenger cars use front and rear braking systems, creating continuous demand for replacement pads across different vehicle platforms. The expansion of passenger vehicle production in China, India, Japan, Germany, and the United States also supports OEM demand. Increasing adoption of advanced braking systems and electronic safety technologies is encouraging manufacturers to develop vehicle-specific friction materials.
Two-wheelers represent the fastest-growing vehicle category. Rising motorcycle and scooter ownership, particularly across Asia Pacific, is supporting demand for braking components. Two-wheelers are widely used for personal transportation, commuting, delivery services, and commercial mobility. The growth of electric scooters and motorcycles is also creating demand for compatible braking products. Manufacturers are expanding their motorcycle brake pad portfolios to cover different engine capacities, vehicle designs, and riding conditions. Light commercial vehicles and heavy commercial vehicles remain important categories because of their extensive use in logistics, transportation, construction, and industrial operations. SUVs also represent a growing sub-segment within passenger vehicles because of their expanding production and increasing vehicle weight.
Sales Channel Insights
The aftermarket is anticipated to account for 65.2% of the market share. Brake pads require replacement as friction material wears during vehicle operation. This creates recurring demand across authorized service centers, independent repair shops, automotive parts retailers, and online distribution platforms. The expanding global vehicle fleet and increasing average vehicle age further support aftermarket sales. Consumers also increasingly access replacement components through digital automotive marketplaces, improving product selection and availability across passenger cars and two-wheelers.
The OEM channel remains important because every newly manufactured vehicle requires a complete braking system. Automotive manufacturers source brake pads from established component suppliers that meet vehicle-specific performance, quality, and safety requirements. Authorized service centers also contribute to replacement sales through scheduled maintenance and manufacturer-approved components. Independent repair shops and retail parts stores maintain an important position in the replacement ecosystem, particularly in price-sensitive markets. Online aftermarket channels are expanding through digital catalogs, vehicle compatibility tools, distributor partnerships, and direct-to-consumer sales.
Regional Insights
North America Automotive Brake Pad Market Trends
North America represents an established automotive brake pad market, supported by a large passenger vehicle fleet, commercial transportation activity, and an extensive automotive aftermarket. The United States remains the primary regional market, while Canada contributes through vehicle manufacturing, replacement component distribution, and automotive maintenance services.
U.S. Automotive Brake Pad Market Trends
The United States represents the largest automotive brake pad market in North America because of its extensive passenger vehicle fleet, established automotive aftermarket, and strong presence of vehicle manufacturers and component suppliers. Demand is generated by passenger cars, SUVs, pickup trucks, and commercial vehicles. The replacement market remains important because brake pads are subject to wear during regular vehicle operation, particularly in urban transportation and commercial fleet applications.
Environmental compliance is influencing the development of replacement brake pads. California's Brake Pad Law requires covered friction materials to meet progressively stricter restrictions on copper and other substances. From January 2025, the applicable copper threshold is 0.5% by weight. The regulation is encouraging suppliers to expand low-copper and copper-free product portfolios.
Europe Automotive Brake Pad Market Trends
Europe represents a technologically advanced automotive brake pad market, supported by established vehicle manufacturing industries, premium passenger vehicle production, and stringent vehicle safety and environmental requirements. Germany and the United Kingdom are important markets because of their automotive manufacturing capabilities, developed replacement component networks, and demand for advanced braking technologies.
Germany Automotive Brake Pad Market Trends
Germany represents a major European market because of its established automotive manufacturing base and presence of leading vehicle manufacturers and component suppliers. Passenger cars, premium automobiles, SUVs, and commercial vehicles generate demand for OEM brake pads and replacement products. The country's automotive engineering ecosystem also supports the development of advanced braking systems and specialized friction materials.
Germany also has an established automotive aftermarket supported by distributors, workshops, and vehicle servicing networks. Demand for replacement pads remains significant across passenger vehicles and commercial fleets. Suppliers with broad vehicle coverage and established OEM relationships maintain an important position in this market.
Asia Pacific Automotive Brake Pad Market Trends
Asia Pacific is anticipated to remain the largest and fastest-growing regional market, accounting for approximately 45.2% of market share. Its position is supported by large-scale vehicle production, expanding two-wheeler ownership, increasing passenger vehicle sales, and a well-developed automotive component manufacturing ecosystem.
China Automotive Brake Pad Market Trends
China represents a major automotive brake pad market because of its extensive vehicle manufacturing base and large domestic vehicle population. Passenger cars, electric vehicles, commercial vehicles, and two-wheelers contribute to demand across OEM and aftermarket channels. The country also has an established automotive component manufacturing ecosystem, supporting domestic production and exports.
The rapid expansion of electric vehicle manufacturing is influencing braking component development. Electric vehicles incorporate regenerative braking, which changes the operating patterns of friction braking systems. Manufacturers are focusing on brake pads with suitable wear characteristics, corrosion resistance, noise control, and compatibility with electric vehicle platforms.
India Automotive Brake Pad Market Trends
India represents an important growth market because of rising vehicle production, expanding passenger vehicle ownership, and substantial two-wheeler demand. According to the Society of Indian Automobile Manufacturers, passenger vehicle production reached approximately 5.06 million units in FY 2024–25, while two-wheeler production reached approximately 23.88 million units.
The large two-wheeler market supports demand for motorcycle and scooter brake pads, while increasing passenger vehicle production strengthens OEM requirements. Commercial transportation, logistics, and delivery services also contribute to replacement demand. The expansion of organized automotive servicing and independent repair facilities supports the distribution of branded and aftermarket braking products.
Competitive Landscape
The global automotive brake pad market is characterized by competition among established braking system manufacturers, automotive component suppliers, and specialized friction material companies. Leading participants include Brembo, ZF Friedrichshafen, TMD Friction, Akebono Brake Industry, Nisshinbo, ADVICS, Bosch, and Continental.
The market also includes regional manufacturers and private-label suppliers that compete through manufacturing costs, product availability, and distribution relationships. Environmental compliance and demand for copper-free formulations are becoming important competitive factors. Manufacturers with established testing facilities, broad vehicle coverage, and strong distribution networks maintain an important position across global markets.
Key Industry Developments
- In August 2025, ZF introduced a new generation of TRW motorcycle brake pads featuring improved initial braking response, heat resistance, and friction materials free from copper, nickel, and antimony.
- In February 2026, Textar announced the introduction of 153 new products during 2025, including 49 passenger car brake pads and five commercial vehicle brake pads. The expansion included 43 first-to-market product applications, strengthening its vehicle coverage and replacement component availability across the European aftermarket.
Companies Covered in Automotive Brake Pad Market
- Brembo S.p.A.
- ZF Friedrichshafen AG
- TMD Friction
- Akebono Brake Industry Co., Ltd.
- Nisshinbo Brake Inc.
- ADVICS Co., Ltd.
- Robert Bosch GmbH
- Continental AG
- Hitachi Astemo, Ltd.
- MAT Holdings, Inc.
- ITT Inc.
- Fras-le S.A.
- Sangsin Brake Co., Ltd.
- ICER Brakes
- EBC Brakes
- Hunan Boyun Automotive Brake Material Co., Ltd.
Frequently Asked Questions
The global automotive brake pad market is projected to be valued at US$4.6 billion in 2026.
The global market is expected to reach US$6.6 billion by 2033.
Key trends include the development of copper-free brake pads, low-dust friction materials, ceramic brake pads, electric vehicle-compatible braking components, and advanced friction technologies.
Semi-metallic brake pads represent the leading material category, accounting for approximately 46.5% of the global market share, supported by braking performance, durability, heat resistance, and broad vehicle compatibility.
The global automotive brake pad market is projected to expand at a CAGR of 5.3% between 2026 and 2033.
Major companies include Brembo, ZF Friedrichshafen, TMD Friction, Akebono Brake Industry, Nisshinbo Brake, ADVICS, Bosch, and Continental.


