




- Food Ingredients & Additives
- Africa Wheat Flour Market
Africa Wheat Flour Market Size, Share, Growth, and Forecast, 2026 to 2033
Africa Wheat Flour Market by Product Type (All-Purpose Flour, Semolina Flour, Whole-Wheat Flour, Bread Flour, Others), Nature (Organic, Conventional), Distribution Channel (B2B, B2C), and Country-wise Analysis for 2026 - 2033

Africa Wheat Flour Market Size & Trends Analysis
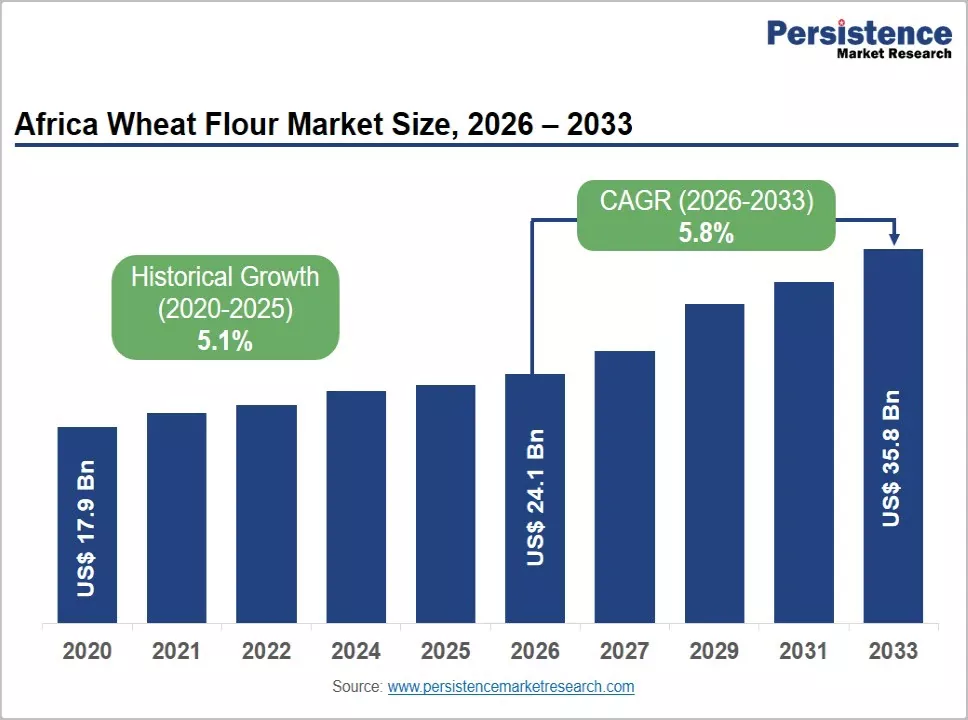
The Africa wheat flour market is expected to be valued at US$ 24.1 billion in 2026 and is projected to reach US$ 35.8 billion by 2033, growing at a CAGR of 5.8% between 2026 and 2033.
The market plays a critical role in supporting food security, urban food consumption, and the region’s expanding food processing sector. Wheat flour remains a staple ingredient in bread, pasta, noodles, biscuits, cakes, and numerous traditional baked products consumed across urban and rural populations.
Rapid population growth, urbanization, and changing dietary habits are driving sustained demand for flour-based foods throughout the continent. At the same time, investments in milling infrastructure, bakery expansion, and food manufacturing are strengthening market development. Governments and industry stakeholders are increasingly focusing on flour fortification initiatives to address nutritional deficiencies and improve public health outcomes. While import dependency creates supply chain challenges, ongoing investments in capacity expansion, product innovation, and value-added flour formulations continue to create attractive growth opportunities across Africa's wheat flour industry.
Key Industry Highlights
- Leading Country: South Africa is likely to lead the Africa wheat flour market with around 27% share in 2026, supported by a well-developed milling sector, advanced food processing infrastructure, extensive retail distribution networks, and strong demand for bakery products and packaged foods.
- Fastest-Growing Country: Nigeria represents the fastest-growing market, driven by rapid population growth, urbanization, increasing consumption of bread, pasta, and noodles, and expanding food manufacturing activities.
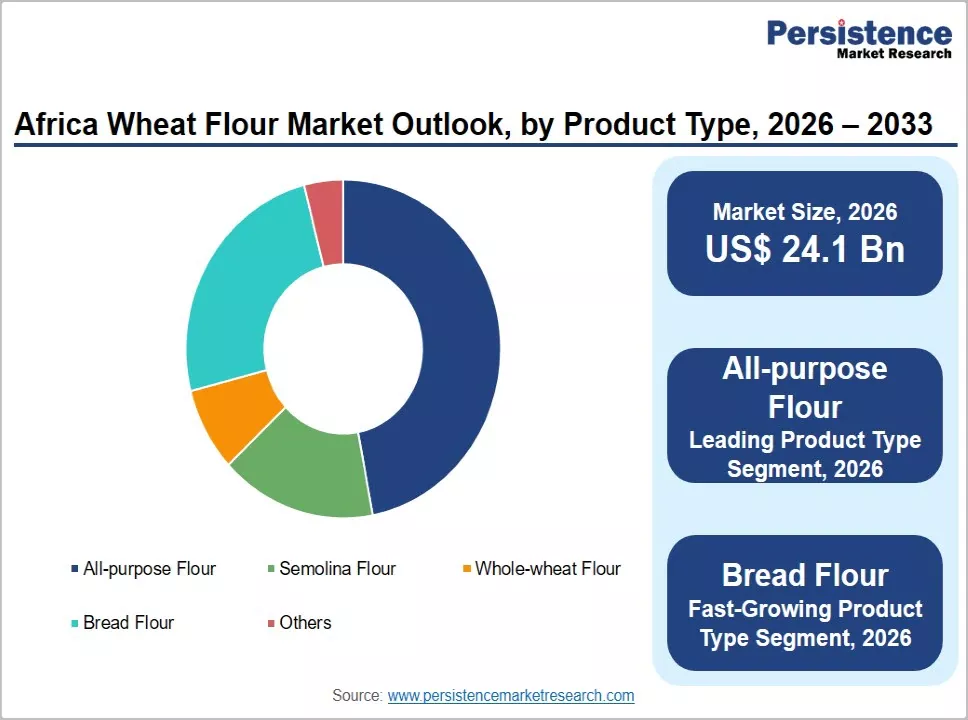
- Dominant Segment: All-purpose flour is the leading product type segment, holding around 47% share in 2026, supported by its versatility across household cooking, bakery products, foodservice applications, and processed food manufacturing.
- Fastest-Growing Segment: Organic wheat flour is the fastest-growing nature segment, driven by increasing consumer interest in natural, minimally processed, and certified organic food products, along with rising awareness of food quality and sustainable agricultural practices.
- Key Market Opportunity: Fortified and value-added wheat flour products offer significant growth opportunities, driven by increasing government focus on nutritional improvement, rising demand for micronutrient-enriched flour, and growing consumer interest in whole-grain, high-fiber, and specialty flour formulations.
- Market Driver: Rapid population growth and urbanization are increasing the consumption of bread, pasta, noodles, baked goods, and other wheat-based staple foods across African markets.
Market Dynamics
Driver: Rapid Population Growth and Urbanization Increasing Bread, Pasta, and Noodle Consumption
Rapid population growth and accelerating urbanization are key drivers of the Africa wheat flour market. Expanding urban populations are increasing demand for affordable, convenient, and staple food products such as bread, noodles, pasta, flatbreads, and baked snacks. Changing lifestyles and rising workforce participation are encouraging greater consumption of packaged and ready-to-eat foods that rely heavily on wheat flour. Commercial bakeries, quick-service restaurants, and food manufacturers are expanding production capacity to meet growing demand from urban consumers.
Additionally, rising disposable incomes in several African economies are supporting increased consumption of processed grain-based foods beyond traditional staples. Government and private-sector investments in food processing infrastructure are further strengthening flour utilization across the value chain. These trends collectively position wheat flour as a critical ingredient supporting Africa’s evolving dietary preferences and food security requirements.
Restraint: Dependence on Wheat Imports Exposing Millers to Price and Supply Shocks
A significant challenge facing the Africa wheat flour market is the region’s heavy dependence on imported wheat. Many African countries lack sufficient domestic wheat production to satisfy rising consumption requirements, making flour millers vulnerable to fluctuations in international grain markets. Global supply disruptions, adverse weather events, export restrictions, currency depreciation, and geopolitical tensions can significantly increase procurement costs and affect supply availability.
Import dependency also exposes millers to freight cost volatility and foreign exchange risks, which can reduce profit margins and create pricing uncertainty. Smaller processors are particularly vulnerable to these external pressures. As a result, manufacturers need to continuously optimize sourcing strategies, improve operational efficiency, and maintain inventory resilience to manage supply chain instability while ensuring affordable flour availability for consumers.
Opportunity: Fortified and Value-Added Flour Supporting Public Nutrition Goals
Fortified and value-added wheat flour products present a significant growth opportunity across Africa. Governments, health organizations, and industry stakeholders increasingly recognize flour fortification as an effective strategy for addressing nutritional deficiencies and improving public health outcomes. Wheat flour enriched with vitamins, iron, zinc, folic acid, and other micronutrients is gaining broader acceptance across public and private-sector food programs.
In addition, manufacturers are introducing premium products such as whole-grain flour, high-fiber formulations, and specialty baking blends that appeal to health-conscious consumers. Growing awareness of nutrition and food quality is encouraging bakeries and food processors to adopt value-added ingredients. As food security and nutritional improvement remain key policy priorities throughout Africa, flour producers offering differentiated nutritional solutions are expected to benefit from expanding market opportunities.
Category-Wise Analysis
Product Type Insights
All-purpose flour is the leading product type segment, holding around 47% share of the market in 2026. This dominance is attributed to its versatility and widespread use across household and commercial food applications. Consumers utilize all-purpose flour in bread, pastries, cakes, flatbreads, snacks, and traditional food preparations, making it one of the most commonly purchased flour categories in many African countries. Food manufacturers and bakeries also favor all-purpose flour because it supports diverse production requirements while offering cost efficiency and operational flexibility.
Strong demand from retail consumers and foodservice establishments further reinforces market leadership. In addition, broad availability through supermarkets, wholesalers, traditional retailers, and local distribution networks increases accessibility across urban and rural areas. These factors continue to support the segment’s leading position within the Africa wheat flour market.
Nature Insights
Conventional wheat flour is the leading segment, supported by its widespread availability, competitive pricing, and established consumption patterns across African markets. The segment benefits from extensive distribution networks, large-scale milling operations, and consistent demand from households, commercial bakeries, and food processing companies. Conventional flour remains the preferred choice for many consumers due to its affordability and suitability for preparing everyday staple foods, including bread, pasta, noodles, and other baked products.
Established sourcing and manufacturing infrastructure further supports its market position. These factors collectively reinforce the dominance of conventional wheat flour across the African market.
Organic wheat flour is expected to be the fastest-growing segment, expanding at a CAGR of 9.8% during the forecast period. Growth is being driven by increasing consumer interest in natural, minimally processed, and certified organic food products. Rising awareness regarding food quality, health, and sustainable agricultural practices is encouraging demand for organic ingredients among affluent urban consumers. Specialty bakeries, health-focused retailers, and premium food manufacturers are expanding organic product offerings to address this emerging market segment.
International export opportunities are also supporting production growth in select countries. In addition, growing investment in certified organic farming and traceability programs is helping improve product credibility and consumer confidence. As premium food consumption expands across major African urban centers, organic wheat flour is expected to experience accelerated demand growth.
Country-Wise Analysis
South Africa Wheat Flour Market Trends and Insights
South Africa is expected to lead the market with a 27% share in 2026. The country benefits from a highly developed milling industry, advanced food processing infrastructure, and extensive retail distribution networks. Wheat flour demand is supported by strong consumption of bread, baked goods, noodles, and packaged food products across urban and rural populations. Large-scale millers continue investing in capacity expansion, product innovation, and operational efficiency improvements to maintain competitiveness.
Growing demand for fortified flour products is also supporting market development. In addition, foodservice expansion and increasing preference for convenience foods are creating new growth opportunities. South Africa's established agricultural and food manufacturing ecosystem enables the country to maintain its leadership position within the broader African wheat flour industry.
Nigeria Wheat Flour Market Trends and Insights
Nigeria is expected to register a CAGR of 7.4% during the forecast period, supported by rapid population growth, urbanization, and increasing consumption of bread, pasta, noodles, and baked products. Wheat flour remains a fundamental ingredient for the country's large bakery and food manufacturing sectors.
Rising investments in milling infrastructure and food processing capacity are helping address growing domestic demand. Government initiatives focused on food security and agricultural development are also influencing industry dynamics. Furthermore, the expansion of modern retail formats and quick-service restaurant chains is increasing consumption of flour-based products. Despite ongoing dependence on imported wheat, strong consumer demand and expanding food manufacturing activities position Nigeria as one of Africa’s most attractive growth markets for wheat flour suppliers.
Competitive Landscape
The Africa wheat flour market is moderately consolidated, with competition led by large milling companies, integrated grain processors, and regional food manufacturers. Market participants compete primarily on flour quality, distribution reach, pricing efficiency, production capacity, and product diversification. Leading players are investing in milling modernization, capacity expansion, fortified flour programs, and supply chain optimization to strengthen their market positions.
Strategic partnerships with bakeries, foodservice operators, and retail chains play an important role in maintaining volume growth and customer loyalty. Companies are also introducing premium and specialty flour products to capture higher-margin opportunities. As consumer demand evolves and governments continue prioritizing food security and nutritional enhancement, firms with strong sourcing capabilities, efficient logistics networks, and value-added product portfolios are expected to be better positioned for sustained competitive growth.
Key Industry Developments:
- In October 2026, the Federal Government of Nigeria announced plans to launch Project WHEAT-NESS, a programme designed to strengthen the domestic wheat-based food industry.
- In July 2026, Kenya's millers launched a consumer awareness campaign promoting fortified flour and educating households about the nutritional benefits of consuming fortified wheat-based products.
Companies Covered in Africa Wheat Flour Market
- The Coca Cola Company
- Premier Foods
- Tiger Brands
- Unga Group
- Dar es Salaam Flour Mills
- Flour Mills of Nigeria
- Crown Flour Mills (Olam Agri)
- Bakhresa Group
- Seaboard Corporation
- Lesaffre
- Honeywell Flour Mills
- Dangote Flour Mills
- Grands Moulins
- National Milling Corporation
- Bakex Millers
- Capwell Industries
- Pioneer Foods
- Others
Frequently Asked Questions
The Africa wheat flour market is expected to be valued at US$ 24.1 billion in 2026 and is projected to reach US$ 35.8 billion by 2033, growing at a 5.8% CAGR through 2033.
Rapid population growth and ongoing urbanization are driving demand for bread, pasta, noodles, and other wheat-based products, thereby fueling growth in the market.
The development of fortified and value-added flour products to support public nutrition objectives represents a significant growth opportunity in the Africa wheat flour market.
Major participants in the market include Premier Foods, Tiger Brands, Unga Group, Dar es Salaam Flour Mills, Flour Mills of Nigeria, Crown Flour Mills (Olam Agri), and others.


