




- Medical Devices
- Urinary Tract Infection Testing Market
Urinary Tract Infection Testing Market Size, Share, and Growth Forecast 2026 - 2033
Urinary Tract Infection Testing Market by Tests (Urinalysis, Urine Cultures, Susceptibility Testing), Test Kits (Home Test Kits, Laboratory Test Kits), Indication (Cystitis, Urethritis, Pyelonephritis), End-User, and Regional Analysis for 2026 - 2033

Urinary Tract Infection Testing Market Size and Trends Analysis
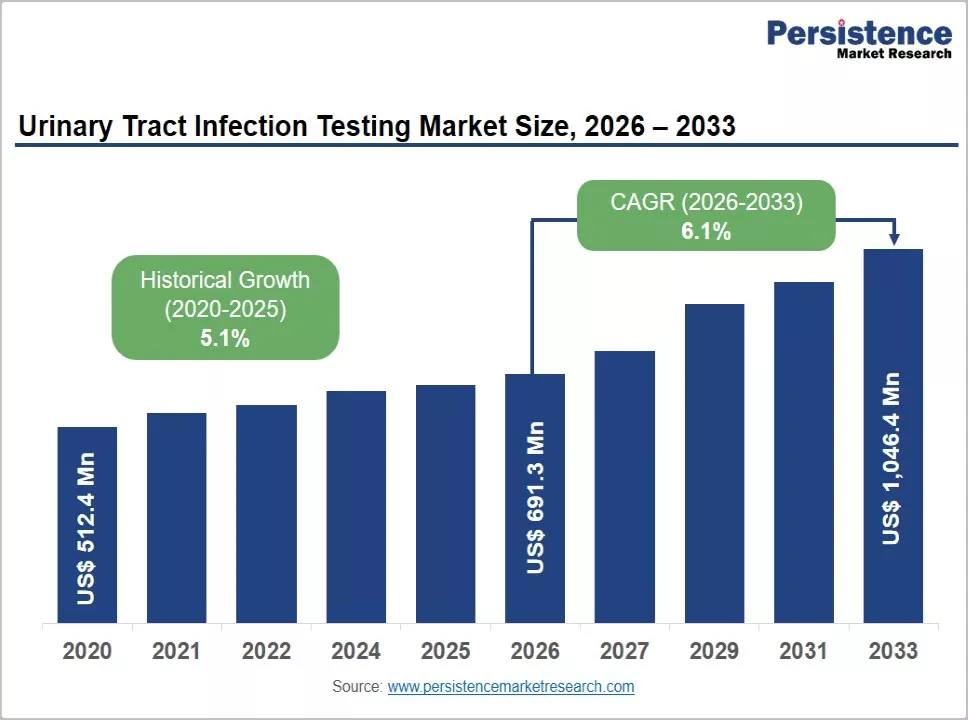
The global urinary tract infection testing market is expected to be valued at US$ 691.3 million in 2026 and is projected to reach US$ 1,046.4 million by 2033, growing at a CAGR of 6.1% between 2026 and 2033.
Market growth is primarily driven by the high and rising burden of urinary tract infections (UTIs), combined with the growing need for accurate, pathogen-specific diagnosis amid increasing antimicrobial resistance. UTIs are among the most common bacterial infections worldwide, and a Global Burden of Disease (GBD)-based analysis estimated 404.6 million UTI cases and more than 236,000 related deaths in 2019. Between 50% and 60% of women experience at least one UTI during their lifetime, sustaining demand for urinalysis and urine culture testing across hospitals, clinics, and diagnostic laboratories.
At the same time, guidance from the World Health Organization (WHO) and national antimicrobial stewardship programs emphasizes appropriate diagnosis and antimicrobial susceptibility testing to support informed antibiotic prescribing. Advances in rapid susceptibility testing and the growing availability of home-based testing solutions are expected to support market growth through 2033.
Key Industry Highlights
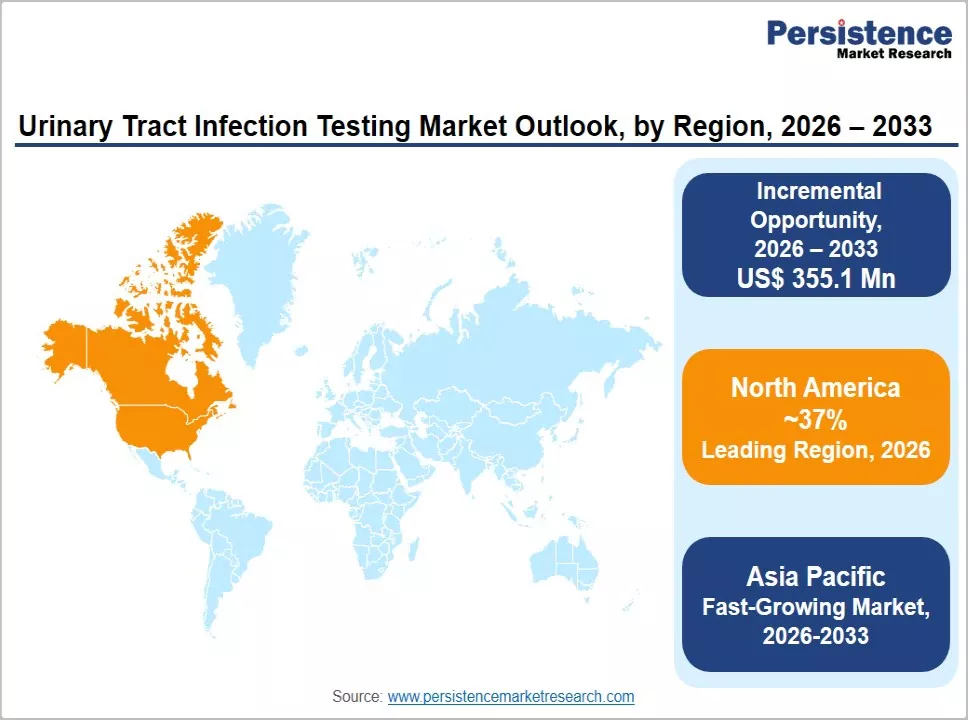
- Leading Region: North America is expected to lead the global market while holding around 37% share in 2026, supported by advanced laboratory infrastructure, established reimbursement systems, high UTI testing volumes, and antimicrobial stewardship initiatives promoted by organizations such as the CDC and The Joint Commission.
- Fastest-Growing Region: Asia Pacific is projected to register a CAGR of 7.6% during 2026 - 2033, driven by expanding healthcare access, rising diabetes prevalence, laboratory modernization, and increasing awareness of antimicrobial resistance.
- Dominant Segment: Laboratory test kits lead the test kit category with a 72% share in 2026, supported by their role in routine diagnostic workflows, the clinical importance of urine culture, and established laboratory infrastructure.
- Fastest-Growing Segment: Homecare is expected to be the fastest-growing end-user segment through 2033, supported by the growing availability of home-based testing solutions, telehealth adoption, pharmacy-based care models, and increasing demand for convenient healthcare services among older adults.
- Key Market Opportunity: Rapid antimicrobial susceptibility testing offers significant growth potential as antimicrobial resistance increases and clinicians seek faster diagnostic results to guide appropriate antibiotic selection.
Market Dynamics
Drivers - Rising Prevalence of UTIs Across Vulnerable Populations
The large and growing patient pool remains a major driver of UTI testing demand. UTIs affect an estimated 150 million people globally each year, with women disproportionately affected because of anatomical factors. Recurrence occurs in approximately 20% to 30% of women within six months of an initial infection, increasing the need for repeat testing. Population ageing is further expanding the burden, as the United Nations projects that the number of people aged 65 years and older is projected to increase from about 10% in 2022 to 16% by 2050.
Older adults are also more susceptible to complicated and catheter-associated UTIs. Diabetes represents another important risk factor, with the International Diabetes Federation reporting 589 million adults living with diabetes in 2024.
Hospitalization further supports testing volumes, particularly for catheter-associated infections. The Centers for Disease Control and Prevention (CDC) reports that approximately 75% of hospital-acquired UTIs are associated with urinary catheters, while 15% to 25% of hospitalized patients receive a catheter. These factors sustain demand for urine screening, culture, pathogen identification, and confirmatory testing across hospitals and diagnostic laboratories.
Antimicrobial Resistance and Stewardship Mandates Favoring Culture-Based Diagnosis
Rising antimicrobial resistance (AMR) is increasing the importance of accurate UTI diagnosis and susceptibility testing. A landmark study published in The Lancet estimated that 1.27 million deaths were directly attributable to bacterial AMR in 2019, while subsequent research projected more than 39 million AMR-attributable deaths between 2025 and 2050. Escherichia coli, the leading cause of UTIs, is a major concern because of increasing resistance to commonly prescribed antibiotics. The WHO Global Antimicrobial Resistance and Use Surveillance System (GLASS) has reported ciprofloxacin resistance in urinary E. coli isolates ranging from 8.4% to 92.9% across reporting countries.
Growing resistance is strengthening antimicrobial stewardship requirements across healthcare systems. Standards from organizations such as the Joint Commission and CDC encourage hospitals to use microbiological information, including urine cultures and antimicrobial susceptibility results, when selecting or adjusting therapy. This trend supports demand for urine culture media, automated microbial identification platforms, and antimicrobial susceptibility testing panels. As resistance patterns become more complex, laboratories are increasingly required to provide reliable pathogen and susceptibility information to support targeted treatment and reduce unnecessary antibiotic exposure.
Restraints - Reimbursement Pressure and Limited Laboratory Access in Low-Resource Settings
Reimbursement and pricing pressures can restrict investment in UTI testing, particularly among laboratories operating with limited financial resources. In the United States, laboratory payments under the Centers for Medicare & Medicaid Services (CMS) Clinical Laboratory Fee Schedule have faced reductions under the Protecting Access to Medicare Act (PAMA). Scheduled payment reductions of up to 15% per test have been repeatedly deferred, creating uncertainty around laboratory revenues and potentially limiting investments in advanced diagnostic platforms.
Regulatory uncertainty has also affected molecular UTI testing, particularly laboratory-developed tests (LDTs), following the U.S. Food and Drug Administration's (FDA) LDT final rule issued in May 2024 and its subsequent vacatur by a federal court in March 2025.
Access limitations are more significant in low- and middle-income countries, where diagnostic infrastructure remains inadequate. The Lancet Commission on Diagnostics reported in 2021 that approximately 47% of the global population has little or no access to diagnostics. Limited microbiology laboratories, shortages of trained personnel, and inadequate equipment restrict the availability of urine culture and antimicrobial susceptibility testing. Consequently, many suspected UTI cases are treated empirically without laboratory confirmation. This reduces testing volumes and limits adoption of sophisticated UTI diagnostic technologies in resource-constrained healthcare systems.
Opportunities - Rapid and Point-of-Care Antimicrobial Susceptibility Testing
Rapid antimicrobial susceptibility testing (AST) represents a significant opportunity as healthcare providers seek faster, evidence-based antibiotic selection. Conventional urine culture followed by susceptibility testing can require approximately 48 to 72 hours, during which clinicians often initiate empirical treatment. This delay can contribute to inappropriate antibiotic selection and prolonged exposure to ineffective therapies. Emerging phenotypic and molecular technologies are addressing this limitation by providing susceptibility information within substantially shorter timeframes.
For example, Sysmex Astrego's PA-100 AST System is designed to provide susceptibility results directly from urine in approximately 45 minutes, supporting treatment decisions during the initial clinical encounter.
The potential of rapid AST received significant international recognition when the PA-100 won the £8 million Longitude Prize on Antimicrobial Resistance in June 2024. Funding from organizations including CARB-X and the Biomedical Advanced Research and Development Authority (BARDA) is also supporting the development of rapid AMR diagnostic technologies. In addition, the introduction of new oral UTI antibiotics in the United States increases the clinical value of rapid susceptibility information. Faster AST can therefore improve targeted treatment, support antimicrobial stewardship, and create opportunities for point-of-care and decentralized UTI testing platforms.
Category-wise Analysis
Tests Insights
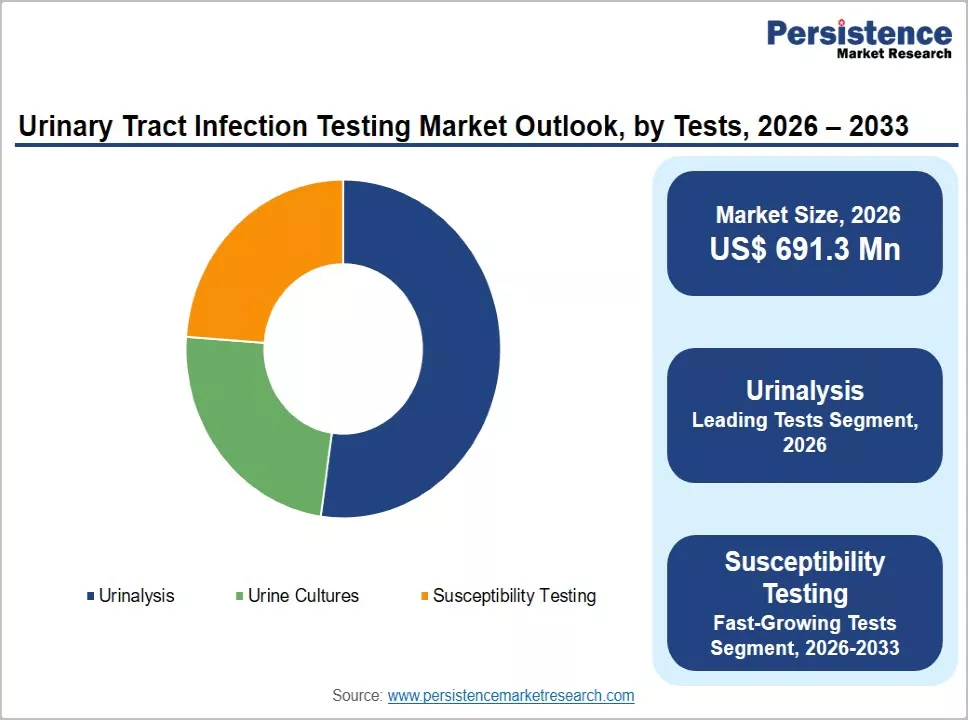
Urinalysis is expected to lead the tests segment, accounting for around 57% of the market share in 2026. It is a first-line diagnostic tool for suspected urinary tract infections (UTIs), combining dipstick testing with microscopic or automated particle analysis to detect indicators such as leukocytes, nitrites, red blood cells, and bacteria. Its low cost, rapid turnaround time, and suitability for Clinical Laboratory Improvement Amendments (CLIA)-waived settings support its routine use in emergency departments, primary care offices, and urgent care clinics.
Automation has strengthened the segment's position, with systems such as Siemens Healthineers' CLINITEK analyzers and Multistix reagent strips, Sysmex UF-Series analyzers, Roche's cobas u analyzers, and ARKRAY's AUTION systems supporting standardized and efficient testing in clinical laboratories. Urinalysis is also widely used as an initial screening tool to identify patients requiring further evaluation, including urine culture and antimicrobial susceptibility testing, sustaining recurring test volumes.
Antimicrobial susceptibility testing is expected to be the fastest-growing segment, driven by rising antimicrobial resistance and increasing emphasis on antimicrobial stewardship. The need to identify effective antibiotic treatments is encouraging the adoption of diagnostic methods that provide timely information on pathogen susceptibility.
Test Kits Insights
Laboratory test kits are expected to remain the dominant segment, accounting for around 72% of the market share in 2026. Hospitals and diagnostic laboratories process a substantial proportion of UTI samples, particularly those associated with complicated infections, pyelonephritis, catheter-associated infections, and cases requiring culture and susceptibility testing. Laboratory products, including urine culture media, microbial identification panels, and antimicrobial susceptibility panels used with automated platforms such as BD Phoenix, bioMérieux VITEK 2, and Beckman Coulter MicroScan WalkAway, support comprehensive diagnostic workflows. Their established clinical use, standardized testing procedures, and integration with laboratory infrastructure reinforce segment demand.
Clinical guidelines, including those of the European Association of Urology (EAU), recommend urine culture and susceptibility testing for recurrent, complicated, and upper urinary tract infections, further supporting laboratory-based testing. Reimbursement coverage under public and private insurance plans also contributes to the segment's market position.
Home test kits are expected to be the fastest-growing segment, supported by increasing interest in convenient testing, pharmacy-based care models, and telehealth services. Growing access to home-based screening solutions is expanding testing options, although laboratory confirmation remains important when identifying the causative pathogen and determining antibiotic susceptibility.
End-User Insights
Hospitals are expected to remain the dominant end-user segment, accounting for around 58% of the urinary tract infection testing market share in 2026. Hospitals manage many severe and complicated UTI cases, including pyelonephritis, urosepsis, and catheter-associated urinary tract infections (CAUTIs), which contribute to the burden of healthcare-associated infections. Emergency departments use urinalysis as part of the diagnostic evaluation of patients presenting with symptoms such as fever and abdominal pain, while selected patients require further microbiological testing.
Hospital laboratories are also equipped with automated urinalysis, culture, microbial identification, and susceptibility testing systems, supporting comprehensive in-house diagnostic capabilities. Infection prevention protocols and surveillance requirements, including CAUTI monitoring through the U.S. Centers for Disease Control and Prevention's National Healthcare Safety Network (NHSN), further support structured testing practices.
Homecare is expected to be the fastest-growing end-user segment, expanding at a projected CAGR of 8.5% between 2026 and 2033. Growth is supported by increasing availability of home-based screening solutions, wider telehealth adoption, and rising demand for convenient care among older adults and patients requiring ongoing healthcare support. Integration with remote consultations and pharmacy-based services is also improving access to initial assessment and follow-up care. However, suspected complicated infections and cases requiring pathogen identification or antimicrobial susceptibility results continue to rely on laboratory-based diagnostic testing.
Regional Analysis
North America Urinary Tract Infection Testing Market Trends and Insights
North America is expected to lead the global urinary tract infection testing market by holding around 37% share in 2026, supported by high diagnostic testing rates, well-established reimbursement systems, and advanced laboratory infrastructure. The region benefits from a large network of hospital laboratories and national reference laboratories operated by companies such as Labcorp and Quest Diagnostics, which process millions of urine specimens annually.
Key regional trends include widespread automation of urinalysis and microbiology workflows, rising use of molecular UTI panels in outpatient and long-term care settings, and growing adoption of telehealth-linked home testing. Antimicrobial stewardship requirements from the Joint Commission and the CDC are strengthening demand for culture and susceptibility testing, while Canada contributes steady demand through publicly funded laboratory services and provincial AMR surveillance programs. Regulatory clarity following court action on laboratory-developed tests in 2025 has also supported continued innovation in molecular and rapid diagnostics across the region.
U.S. Urinary Tract Infection Testing Market Size
The U.S. accounts for around 89% of the North American urinary tract infection testing market revenue. UTIs account for more than 10 million ambulatory care visits in the country each year, and the CDC recognizes catheter-associated UTIs as a major healthcare-associated infection tracked through the National Healthcare Safety Network (NHSN). The country's large Medicare population, with more than 67 million beneficiaries enrolled according to CMS, drives high testing volumes among older adults, who face elevated risks of complicated infections.
The FDA approvals of new oral antibiotics for uncomplicated UTIs, including GSK's Blujepa (gepotidacin) in 2025, increase the importance of susceptibility-guided prescribing. Opportunities exist in rapid AST, molecular panels for long-term care, and direct-to-consumer home testing linked to telehealth services.
Europe Urinary Tract Infection Testing Market Trends and Insights
Europe represents the second-largest market, accounting for an estimated 29% of the global market share in 2026. Regional market growth is supported by universal healthcare systems, an ageing population, and strong antimicrobial stewardship frameworks coordinated by the European Centre for Disease Prevention and Control (ECDC) through its European Antimicrobial Resistance Surveillance Network (EARS-Net). Guidelines from the European Association of Urology (EAU) promote culture-guided treatment for recurrent and complicated infections, supporting laboratory testing demand.
Key regional trends include laboratory consolidation into large centralized microbiology networks, adoption of total laboratory automation for urine culture, and expansion of pharmacy-based UTI services. Susceptibility testing across the region is standardized by the European Committee on Antimicrobial Susceptibility Testing (EUCAST), encouraging harmonized AST practices. The EU In Vitro Diagnostic Regulation (IVDR) is raising compliance requirements for manufacturers, favouring established suppliers with robust clinical evidence and quality systems.
Germany Urinary Tract Infection Testing Market Size
Germany is projected to hold roughly 24% share of the European market in 2026. The country has one of the oldest populations in the region, with more than 22% of residents aged 65 or older according to the Federal Statistical Office (Destatis), increasing the incidence of complicated and catheter-associated UTIs. Germany's extensive hospital network and statutory health insurance coverage support routine urinalysis and culture testing. National AMR surveillance through the Robert Koch Institute's Antibiotic Resistance Surveillance (ARS) system and the German Antimicrobial Resistance Strategy (DART 2030) encourage susceptibility-guided prescribing.
The presence of diagnostics leaders such as Siemens Healthineers and Roche Diagnostics operations further strengthens adoption of automated urinalysis platforms. Opportunities lie in rapid AST and laboratory automation in consolidated microbiology networks.
U.K. Urinary Tract Infection Testing Market Size
The U.K. is estimated to hold nearly 18% share of the European urinary tract infection testing market in 2026. The National Health Service (NHS) manages high UTI testing volumes across primary care, hospitals, and care homes, guided by UK Health Security Agency (UKHSA) diagnostic guidance on urine testing. The NHS Pharmacy First service, launched in January 2024, enables pharmacists to manage uncomplicated UTIs in women, expanding community testing pathways.
The government's UK National Action Plan for AMR 2024-2029 commits to reducing antimicrobial use and improving diagnostic stewardship, supporting culture and susceptibility testing. UKHSA surveillance data also show that E. coli bloodstream infections, frequently originating from the urinary tract, remain a major focus. Opportunities exist in point-of-care tests, digital dipstick readers, and rapid diagnostics for care homes.
Asia Pacific Urinary Tract Infection Testing Market Trends and Insights
Asia Pacific represents the fastest-growing market, projected to expand at a CAGR of 7.6% between 2026 and 2033. Growth is fueled by large populations, rising healthcare expenditure, expanding hospital and diagnostic laboratory networks, and growing awareness of antimicrobial resistance. China is the region's largest market, supported by its tiered healthcare reform, rapid growth of independent clinical laboratories, and national AMR surveillance through the China Antimicrobial Resistance Surveillance System (CARSS).
China's National Action Plan to Contain Antimicrobial Resistance (2022-2025) emphasizes rational antibiotic use, supporting culture-based diagnosis. Regional trends include automation of urinalysis in tertiary hospitals, rising diabetes prevalence that increases UTI risk, and strong demand for affordable dipstick and rapid tests in primary care. Domestic manufacturers are expanding cost-competitive urinalysis analyzers, while multinational companies are investing in distribution and local manufacturing across the region.
India Urinary Tract Infection Testing Market Size
India's urinary tract infection testing market is estimated at US$ 17 million in 2026. The country faces a high burden of drug-resistant infections, and the Indian Council of Medical Research (ICMR) Antimicrobial Resistance Surveillance Network has consistently reported high resistance among urinary E. coli and Klebsiella isolates to commonly used antibiotics. India's diabetic population, estimated by the IDF at about 89.8 million adults in 2024, further raises UTI risk. Expansion of Ayushman Bharat health insurance, the government's Free Diagnostics Service Initiative, and rapid growth of organized diagnostic chains are improving test access. Opportunities exist in affordable automated urinalysis, rapid susceptibility testing, and home test kits.
Japan Urinary Tract Infection Testing Market Size
Japan is anticipated to hold about 22% share of the Asia Pacific market in 2026. Japan has the world's oldest population, with about 29% of residents aged 65 or older according to the Statistics Bureau of Japan, driving high incidence of complicated, recurrent, and catheter-associated UTIs among older adults in hospitals and long-term care facilities. The country's universal health insurance system reimburses urinalysis and culture testing, supporting high testing rates.
Japan's National Action Plan on Antimicrobial Resistance promotes appropriate antibiotic use and diagnostic stewardship. Domestic leaders such as Sysmex Corporation and ARKRAY, Inc. are global pioneers in automated urinalysis, ensuring rapid adoption of advanced analyzers. Opportunities lie in rapid AST, automated urine particle analysis, and testing solutions for nursing care facilities.
Competitive Landscape
The global urinary tract infection testing market is moderately consolidated, with leading diagnostics companies such as F. Hoffmann-La Roche Ltd., Siemens Healthineers, Sysmex Corporation, Danaher Corporation, Abbott Laboratories, Thermo Fisher Scientific, Inc., and Bio-Rad Laboratories holding significant shares through broad urinalysis, microbiology, and molecular portfolios. Reference laboratories such as Labcorp strengthen competition in testing services, while ACON Laboratories and Cardinal Health compete in rapid tests and distribution.
Market leaders differentiate through high-throughput automated urinalysis analyzers, integrated microbiology workflows, validated reagent-instrument systems, and global service networks. Key strategies include investment in rapid antimicrobial susceptibility testing, molecular syndromic panels, laboratory automation, and digital connectivity. Emerging business models include reagent rental and pay-per-test agreements for hospital laboratories, direct-to-consumer home test kits linked to telehealth services, and partnerships with pharmacies supporting community-based UTI care pathways.
Key Industry Developments
- In September 2025, Biotia launched an advanced “Test-to-Treat” solution for recurrent urinary tract infections (UTIs), combining at-home urine sample collection, laboratory-based diagnostic testing, and targeted virtual care. The solution was designed to improve access to UTI diagnostics while enabling more personalized and efficient management of recurrent infections.
- In June 2025, bioMérieux acquired Day Zero Diagnostics, a U.S.-based infectious disease diagnostics company, to enhance its capabilities in next-generation sequencing and rapid diagnostic technologies. The acquisition strengthened bioMérieux’s infectious disease testing portfolio and supported the development of advanced solutions for antimicrobial stewardship and precision diagnostics.
Companies Covered in Urinary Tract Infection Testing Market
- LabCorp.
- Thermo Fisher Scientific, Inc.
- F. Hoffmann-La Roche
- ACON Laboratories Inc.
- Cardinal Health Inc.
- Danaher Corporation
- SYSMEX CORPORATION
- Abbott Laboratories
- Bio-Rad Laboratories
- Roche AG
- Siemens Healthineers
- Stryker Corporation
- Others
Frequently Asked Questions
The global urinary tract infection testing market is expected to be valued at US$ 691.3 million in 2026 and is projected to reach US$ 1,046.4 million by 2033, expanding at a 6.1% CAGR between 2026 and 2033.
Demand is driven by the high global UTI burden, population ageing, rising diabetes prevalence, antimicrobial resistance, and increasing emphasis on antimicrobial stewardship, diagnosis, and appropriate treatment across healthcare settings worldwide.
North America is likely to lead the urinary tract infection testing market by holding around 37% share in 2026.
Rising demand for rapid antimicrobial susceptibility testing creates immense opportunities in the market.
Key players include LabCorp, Thermo Fisher Scientific, Roche, ACON Laboratories, Cardinal Health, Danaher, Sysmex, Abbott Laboratories, Bio-Rad Laboratories, Siemens Healthineers, bioMérieux, and Becton Dickinson.


