




- Pharmaceuticals
- Rare Haematology Disorders Market
Rare Haematology Disorders Market Size, Share, and Growth Forecast, 2026 - 2033
Rare Haematology Disorders Market By Disease Type (Hemophilia A & B, Sickle Cell Disease, Thalassemia, Others), Treatment Modality (Factor Replacement Therapies, Gene Therapy, Others), End User and Regional Analysis for 2026 - 2033

Rare Haematology Disorders Market Size and Trends Analysis
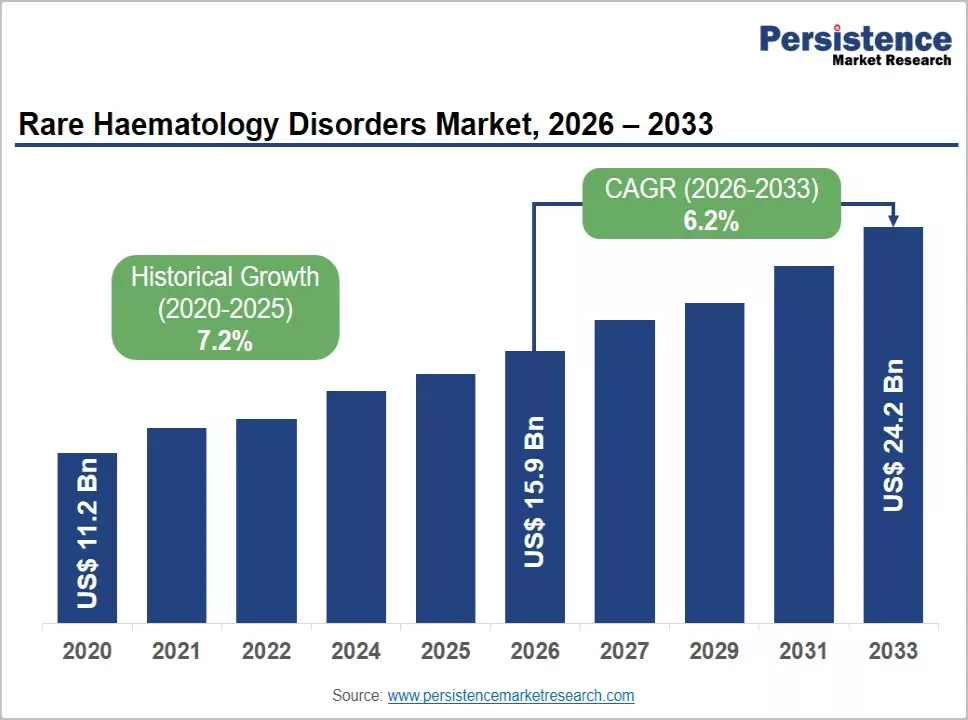
The global rare haematology disorders market size is likely to be valued at US$15.9 billion in 2026 and is expected to reach US$24.2 billion by 2033, growing at a CAGR of 6.2% between 2026 and 2033, driven by earlier diagnosis of inherited blood disorders, wider use of non-factor prophylaxis, and the commercial rollout of gene therapy and gene-editing treatments.
Health systems are shifting from lifelong factor replacement and regular transfusion toward therapies that reduce bleeding episodes, vaso-occlusive crises, and transfusion dependence.
Key Industry Highlights
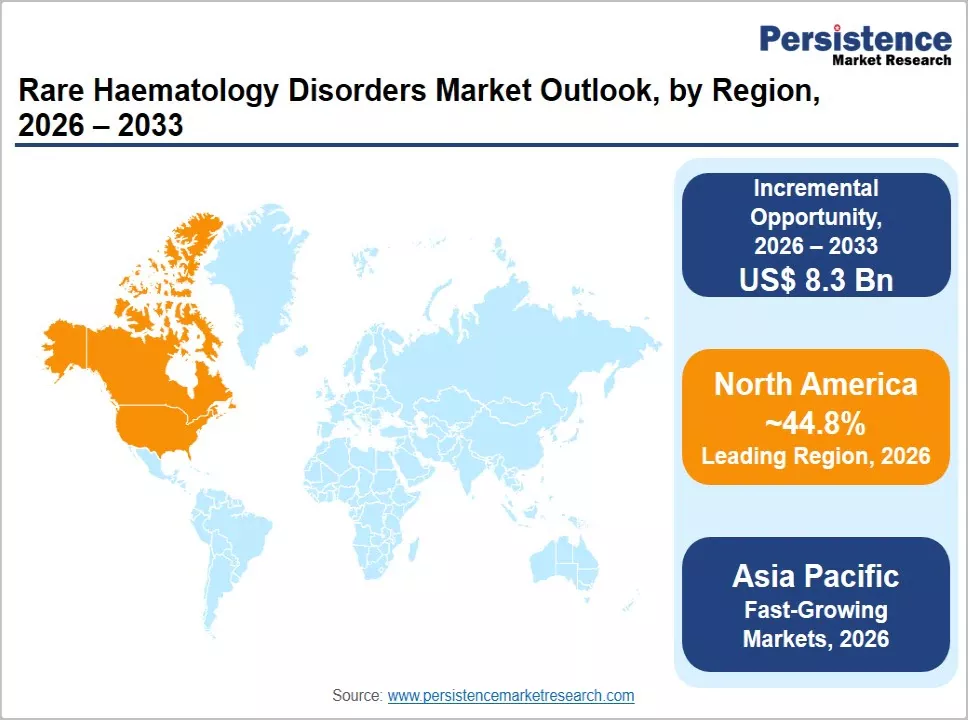
- Leading Region: North America, anticipated to account for approximately 44.8% of the market share, supported by early adoption of new therapies, established care networks, and structured reimbursement programs.
- Fastest-growing Region: Asia Pacific, driven by national screening programs, expanding rare disease policy support, and emerging domestic gene therapy developers.
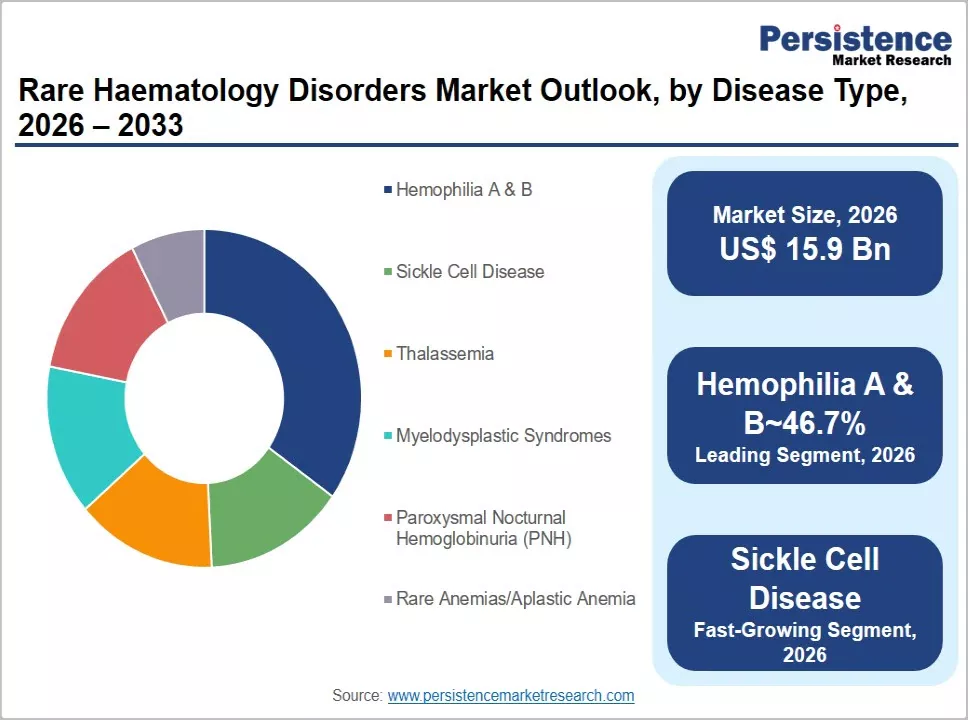
- Dominant Disease Type: Hemophilia A & B, anticipated to account for approximately 46.7% of the market share, driven by lifelong treatment requirements and a broad range of factor and non-factor products.
- Leading Treatment Modality: Factor replacement therapies, with plasma-derived products accounting for approximately 56.2% of the segment, supported by long clinical experience and broad availability.
DRO Analysis
Drivers - Non-Factor Prophylaxis and Gene-Based Therapies Are Reshaping Treatment Standards
Therapeutic innovation is changing care pathways in hemophilia and inherited red blood cell disorders. Roche reported Hemlibra sales of CHF 4.75 billion in 2025, up 11% at constant exchange rates, reflecting the shift from intravenous factor replacement toward subcutaneous prophylaxis. Sanofi's Qfitlia, approved by the U.S. FDA in March 2025, added the first siRNA therapy for hemophilia.
Regulatory expansion is widening treated populations. In June 2026, the FDA extended Pfizer's Hympavzi to children aged 6 to 11 years and patients with inhibitors, who represent roughly 20% of hemophilia A patients. Casgevy generated US$115.8 million in 2025 revenue compared with US$10 million in 2024.
Rising Diagnosis and Expanding Reimbursement Frameworks Are Increasing the Treated Patient Pool
Disease burden is large and diagnosis is improving. A Global Burden of Disease Study 2021 analysis in The Lancet Haematology reported 7.74 million people living with sickle cell disease in 2021, up 41.4% from 2000. The World Federation of Hemophilia estimates about 836,000 people with hemophilia worldwide, and its 2024 Annual Global Survey covered 135 countries.
Payer frameworks are adapting. The U.S. Cell and Gene Therapy Access Model includes 33 states, the District of Columbia, and Puerto Rico, covering approximately 84% of Medicaid beneficiaries with sickle cell disease, and links payment to clinical outcomes, supporting reimbursed access to gene therapy.
Restraint - High Treatment Costs and Commercial Viability Challenges Limit Access to Advanced Therapies
High costs and complex delivery requirements restrict adoption of advanced therapies. Casgevy is priced at approximately £1.65 million in England, and treatment requires conditioning and stem cell procedures at authorized hospital centers. Agios's Aqvesme is available only through a Risk Evaluation and Mitigation Strategy program because of hepatocellular injury risk.
Commercial risk is visible in hemophilia gene therapy. BioMarin recorded Roctavian sales of US$36 million in 2025 and a US$119 million inventory write-off before withdrawing the product in February 2026 for lack of a qualified buyer. These factors concentrate uptake in well-resourced health systems.
Opportunities - Pediatric and Inhibitor-Population Label Expansion Is Broadening the Treatable Patient Base
Label expansion into younger and harder-to-treat groups is creating new revenue pools. Pfizer's June 2026 approval made Hympavzi the first subcutaneous non-factor therapy for children aged 6 to 11 years with hemophilia B. Vertex has completed a U.S. submission for Casgevy in children aged 5 to under 12 years with sickle cell disease or transfusion-dependent beta thalassemia.
Earlier treatment is expected to reduce long-term complications such as joint damage and recurrent vaso-occlusive crises. Manufacturers with pediatric data, simplified dosing, and home-based administration are positioned to capture this demand. Inhibitor-complicated hemophilia represents a further underserved group.
Asia Pacific Offers Strong Expansion Potential through Screening Programs and Local Innovation
Asia Pacific presents substantial growth potential because of large patient populations and expanding government programs. India's National Sickle Cell Anaemia Elimination Mission, launched in July 2023 with an elimination target of 2047, has screened more than 57 million people aged 0 to 40.
Local innovation is lowering entry barriers. India introduced BIRSA-101, an indigenous CRISPR-based sickle cell therapy, in late 2025, while China approved its first hemophilia B gene therapy, BBM-H901, in April 2025. Together, these initiatives widen the diagnosed and treatable population and build regional capability to develop advanced therapies at lower cost.
Category-wise Analysis
Disease Type Insights
Hemophilia A & B is anticipated to account for approximately 46.7% of the market share. The segment benefits from lifelong treatment requirements, established prophylaxis protocols, and the broadest range of approved products. For example, Roche's Hemlibra, Pfizer's Hympavzi, and Sanofi's Qfitlia have expanded non-factor options, while factor concentrates continue to serve patients with and without inhibitors.
Sickle cell disease is anticipated to be the fastest-growing disease type, expanding at a CAGR of 11.3%, driven by large patient populations, screening programs, and gene-based therapies. For example, Casgevy and Lyfgenia received U.S. FDA approval in December 2023 as the first cell-based gene therapies for the disease, and Novo Nordisk's etavopivat is in Phase III development.
Treatment Modality Insights
Factor replacement therapies are anticipated to be the leading treatment modality, with plasma-derived products accounting for approximately 56.2% of the segment. These products remain central to hemophilia care because of long clinical experience, broad availability, and use in prophylaxis and on-demand settings. For example, Sanofi and Sobi's Altuviiio, approved by the FDA in February 2023, shows continued innovation in extended half-life factor therapy.
Gene therapy is anticipated to be the fastest-growing treatment modality, supported by one-time administration, expanding approvals, and new reimbursement frameworks. For example, Casgevy is approved in the United States, United Kingdom, European Union, and Canada, and CSL's Hemgenix established a gene therapy option for hemophilia B. BioMarin's 2026 withdrawal of Roctavian shows that adoption remains concentrated among therapies with clear payer pathways.
End User Insights
Hospitals are anticipated to account for approximately 53.9% of the market share. The segment includes hematology departments, transfusion services, and transplant centers that deliver complex therapies requiring monitoring and multidisciplinary care. For example, Casgevy involves stem cell collection, conditioning, and infusion at authorized treatment centers, with patients remaining in hospital until after infusion.
Specialty clinics are anticipated to be the fastest-growing end user, driven by the shift toward subcutaneous prophylaxis and outpatient disease management. For example, Hympavzi is administered once weekly through a prefilled auto-injector pen without routine treatment-related laboratory monitoring, supporting follow-up in specialty and home-supported settings.
Regional Insights
North America Rare Haematology Disorders Market Trends
North America is anticipated to account for approximately 44.8% of the market share, with the United States representing the largest share of regional demand. Early access to new therapies, established hemophilia treatment centers and sickle cell programs, and structured reimbursement mechanisms support regional leadership.
U.S. Rare Haematology Disorders Market Trends
The United States remains the dominant market in North America because of its large treated patient base and rapid adoption of approved therapies. More than 100,000 people are expected to be living with sickle cell disease in the country, and the Cell and Gene Therapy Access Model covers approximately 84% of Medicaid beneficiaries with the disease.
In December 2025, the FDA approved Agios's Aqvesme as the first oral therapy for anemia in alpha- or beta-thalassemia, covering both transfusion-dependent and non-transfusion-dependent disease, a population of approximately 6,000 diagnosed adults. In June 2026, the FDA expanded Pfizer's Hympavzi to children aged 6 to 11 years and patients with inhibitors.
Canada Rare Haematology Disorders Market Trends
Canada represents an important secondary market, supported by publicly funded healthcare and growing access to advanced therapies. Health Canada authorized Casgevy in September 2024 for patients aged 12 years and older, and Vertex estimates approximately 2,000 eligible patients in the country.
Approximately 6,000 Canadians live with sickle cell disease. Access depends on provincial and federal reimbursement decisions, and Vertex has submitted Casgevy for health technology assessment to Canada's Drug Agency and Quebec's INESSS.
Europe Rare Haematology Disorders Market Trends
Europe is a mature market characterized by established national hemophilia care networks, centralized regulatory approval through the European Medicines Agency, and country-level health technology assessment. Reimbursement negotiations for high-cost gene-based therapies increasingly determine the pace of regional adoption.
Germany Rare Haematology Disorders Market Trends
Germany represents a major European market because of its large statutory health insurance system and early access to newly approved medicines. In May 2026, Vertex signed a reimbursement agreement with the GKV-Spitzenverband for Casgevy, securing long-term access for eligible patients aged 12 years and older.
Germany joined Austria, Denmark, Italy, Saudi Arabia, the UAE, the United Kingdom, and the United States among countries reimbursing the therapy, indicating growing payer acceptance of one-time treatments.
United Kingdom Rare Haematology Disorders Market Trends
The United Kingdom remains an important market because of centralized NHS England decision-making and managed access mechanisms. NICE recommended Casgevy for sickle cell disease in January 2025, following an August 2024 agreement for transfusion-dependent beta thalassemia.
NHS England estimated that approximately 50 sickle cell disease patients per year would initially receive Casgevy, while NICE estimated about 460 eligible thalassemia patients. The price of approximately £1.65 million per patient reflects the cost-effectiveness scrutiny applied to curative therapies.
Asia Pacific Rare Haematology Disorders Market Trends
Asia Pacific is anticipated to be the fastest-growing regional market due to large patient populations, expanding national screening programs, rising rare disease policy support, and the emergence of domestic gene therapy developers.
India Rare Haematology Disorders Market Trends
India is emerging as a major growth market because of a high burden of sickle cell disease and thalassemia, particularly among tribal communities. The National Sickle Cell Anaemia Elimination Mission, launched in July 2023, aims to eliminate the disease as a public health problem by 2047.
In late 2025, India introduced BIRSA-101, its first indigenous CRISPR-based gene therapy for sickle cell disease, developed by CSIR-IGIB with Serum Institute of India. A Phase I trial is being prepared with AIIMS.
China Rare Haematology Disorders Market Trends
China continues to expand its rare disease framework, with a first national catalog covering 121 diseases in 2018 and a combined list reaching 207 diseases after the September 2023 update. PNH is included in the first catalog, and the 2024 reimbursement list added Novartis's Fabhalta.
In April 2025, the NMPA approved BBM-H901, developed by Belief BioMed and commercialized by Takeda China, as the first hemophilia B gene therapy in China and the first rAAV gene therapy developed and manufactured in Asia.
Competitive Landscape
Competition in the global rare haematology disorders market occurs among multinational biopharmaceutical companies, plasma-derived product manufacturers, and specialty rare disease developers. Hemophilia is concentrated among a limited number of suppliers, while sickle cell disease, thalassemia, PNH, and rare anemias include a broader mix of established and emerging participants. Companies compete based on portfolio breadth, clinical differentiation, regulatory approvals, reimbursement agreements, and treatment center networks.
Leading companies are focusing on label expansion, non-factor and gene-based innovation, portfolio acquisition, and outcomes-based reimbursement. Competitive differentiation increasingly depends on convenience of administration, durability of response, and access to specialized treatment centers.
Key Industry Developments
- In February 2026, BioMarin announced the voluntary withdrawal of Roctavian after failing to identify a qualified buyer, reflecting commercial challenges in one-time hemophilia gene therapy.
- In May 2026, Vertex signed a reimbursement agreement with Germany's GKV-Spitzenverband for Casgevy, securing long-term access for eligible patients with sickle cell disease and transfusion-dependent beta thalassemia.
- In May 2026, Biogen completed its acquisition of Apellis, announced in March 2026 at approximately US$5.6 billion, adding Empaveli for paroxysmal nocturnal hemoglobinuria.
- In June 2026, Pfizer received expanded FDA approval for Hympavzi in children aged 6 to 11 years and patients with inhibitors, strengthening its non-factor hemophilia position.
Companies Covered in Rare Haematology Disorders Market
- F. Hoffmann-La Roche Ltd
- Takeda Pharmaceutical Company Limited
- Sanofi S.A.
- Novo Nordisk A/S
- CSL Limited
- Pfizer Inc.
- Novartis AG
- AstraZeneca PLC (Alexion)
- Vertex Pharmaceuticals Incorporated
- Bristol Myers Squibb Company
- Bayer AG
- Grifols, S.A.
- Octapharma AG
- Swedish Orphan Biovitrum AB (Sobi)
- Agios Pharmaceuticals, Inc.
- BioMarin Pharmaceutical Inc.
Frequently Asked Questions
The global rare haematology disorders market is projected to be valued at US$ 15.9 billion in 2026.
The market is expected to reach US$ 24.2 billion by 2033.
Key trends include the growing adoption of non-factor prophylaxis, gene therapy and gene editing, expanded pediatric and inhibitor indications, outcomes-based reimbursement, and screening programs.
Hemophilia A & B is anticipated to remain the leading disease type segment, accounting for approximately 46.7% of the market.
The market is projected to expand at a CAGR of 6.2% between 2026 and 2033.
Major companies include Roche, Takeda, Sanofi, Novo Nordisk, and Pfizer.


