




- Specialty & Fine Chemicals
- Polyacrylic Acid Market
Polyacrylic Acid Market Size, Share, and Growth Forecast, 2026 - 2033
Polyacrylic Acid Market by Product Type (Co-Polymer, Homo-Polymer, Other), Application (Water & Wastewater Treatment, Detergents & Cleaners, Others), Form, End-Use Industry, and Regional Analysis for 2026 - 2033

Polyacrylic Acid Market Size and Trends Analysis
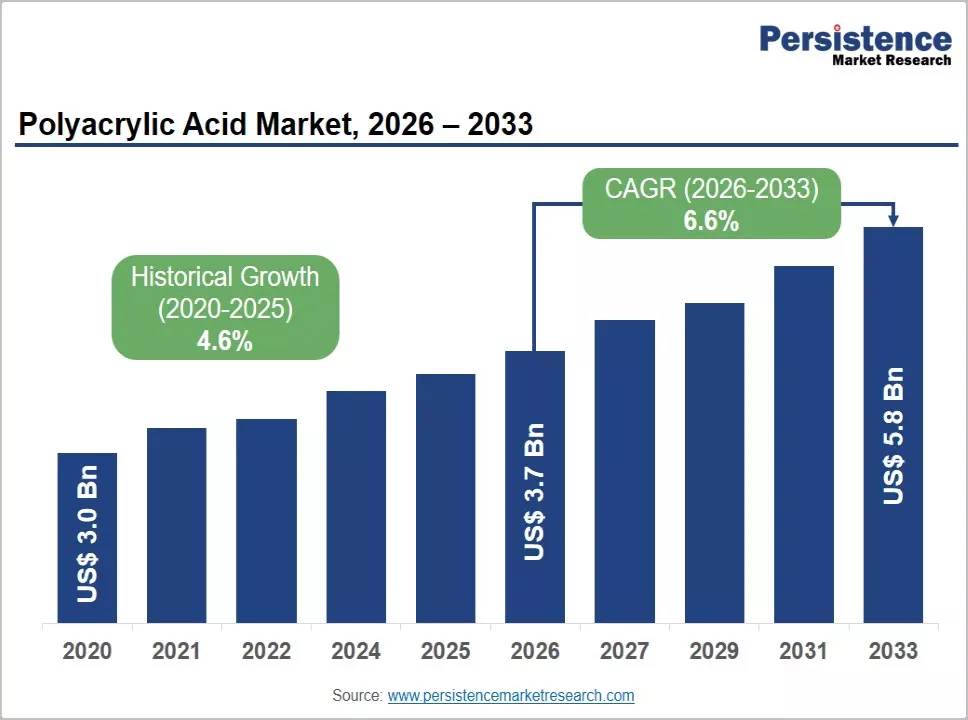
The global polyacrylic acid market size is likely to be valued at US$3.7 billion in 2026 and is expected to reach US$5.8 billion by 2033, growing at a CAGR of 6.6% between 2026 and 2033, driven by increasing demand for water and wastewater treatment, detergent formulations, personal care products, coatings, and specialty industrial applications. Polyacrylic acid provides dispersing, scale-control, thickening, stabilizing, emulsifying, and chelating functions across diverse formulations.
Rising investment in water infrastructure, increasing wastewater treatment requirements, and expanding industrial water reuse are strengthening demand for acrylic-based treatment polymers. Manufacturers are developing higher-performance grades with improved formulation stability, electrolyte tolerance, dosage efficiency, and sustainability characteristics.
Key Industry Highlights:
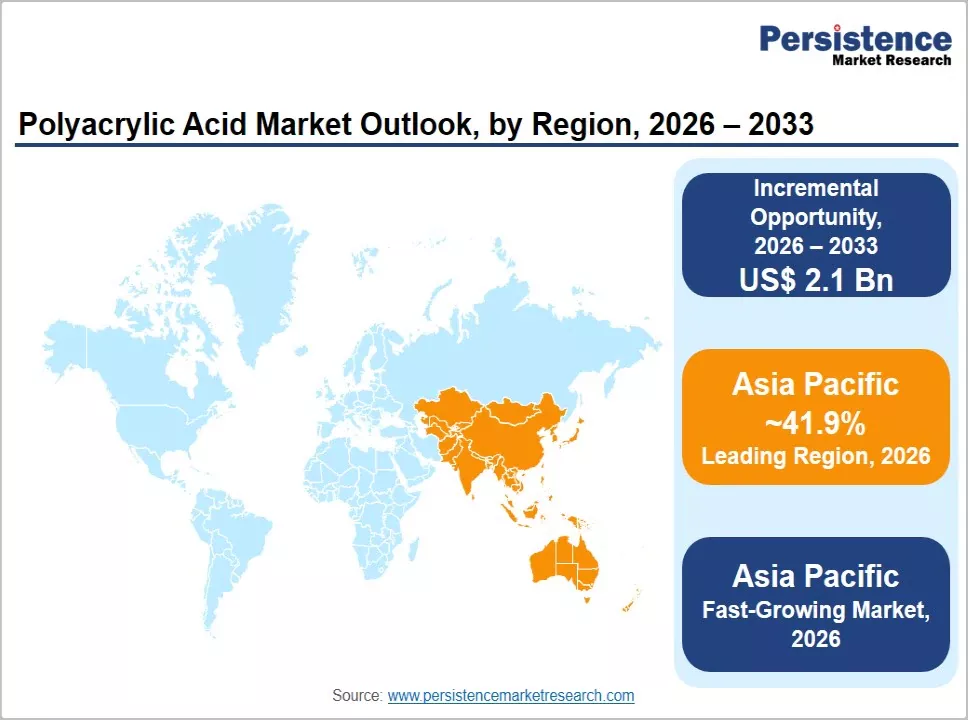
- Leading Region: Asia Pacific, accounting for approximately 41.9% of market revenue, supported by expanding wastewater treatment, industrial manufacturing, detergent production, and acrylic-chemical capacity.
- Fastest-growing Region: Asia Pacific, driven by rapid industrialization, urbanization, water-treatment infrastructure expansion, and increasing demand from China, India, and other emerging Asian economies.
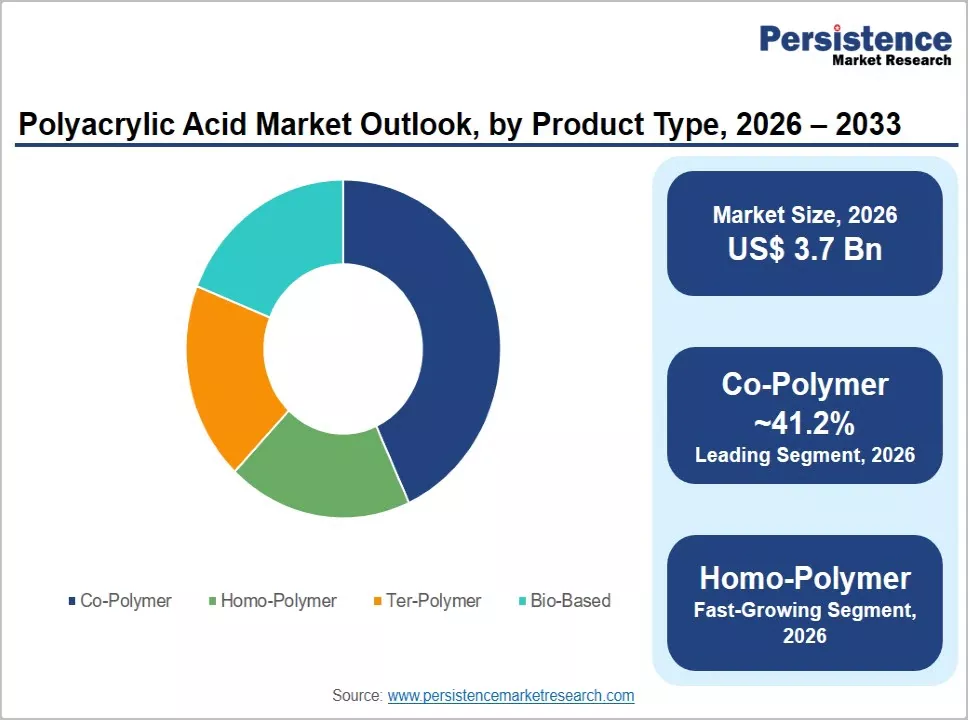
- Dominant Product Type: Co-polymer PAA, anticipated to account for 41.2% of the market, supported by broad use in water treatment, detergents, and specialty formulations requiring dispersion, scale inhibition, and formulation stability.
- Leading Application: Water & wastewater treatment, anticipated to account for 37.8% of the market, driven by increasing wastewater treatment requirements, industrial water reuse, scale control, and investment in water infrastructure.
DRO Analysis
Drivers - Expansion of Water and Wastewater Treatment Infrastructure
Water and wastewater treatment is a major demand center for polyacrylic acid because acrylic polymers provide dispersion, scale inhibition, sequestration, and deposit-control functions in industrial and municipal water systems. Global wastewater infrastructure faces significant treatment gaps. The World Health Organization reported that approximately 42% of household wastewater was not safely treated in 2022, representing about 113 billion cubic meters discharged with inadequate or no treatment. Governments are consequently increasing investments in wastewater collection, treatment, reuse, and pollution control.
In the U.S., federal water infrastructure programs continue to support treatment-system upgrades. The Environmental Protection Agency allocated approximately US$1.24 billion to the Clean Water State Revolving Fund for FY2025, while federal infrastructure legislation provided substantial multiyear funding for wastewater and water-quality projects.
Growth in Functional Formulations across Detergents, Personal Care, and Industrial Processing
Polyacrylic acid has a broad functional profile that allows manufacturers to use it across thickening, suspension, dispersion, emulsification, rheology modification, and scale-control applications. These characteristics support demand in detergents, cleaners, cosmetics, pharmaceuticals, paints, coatings, polishes, and industrial formulations.
The detergent industry is increasingly focused on concentrated formulations, improved cleaning efficiency, lower-phosphate systems, and products that maintain performance under varying water hardness. Acrylic polymers can help disperse inorganic particles, prevent redeposition, control mineral deposits, and improve formulation stability. In personal care, acrylic polymers provide viscosity and texture control and help stabilize emulsions and suspensions.
Restraint - Acrylic Acid Feedstock Exposure and Regulatory Compliance Costs
Polyacrylic acid production remains closely linked to the availability and pricing of acrylic acid, its primary monomer. Acrylic acid production is connected to petrochemical feedstocks, energy consumption, plant utilization, and transportation costs. Variations in feedstock prices and energy costs can therefore affect polymer manufacturing economics and contract pricing.
Regulatory requirements also influence production and formulation strategies. European chemical regulations increasingly address polymer composition, environmental persistence, emissions, and the use of intentionally added synthetic polymer microparticles. Manufacturers must maintain tighter control over raw materials, residual monomers, product specifications, labeling, and documentation.
Opportunities - Sustainable and Bio-Based Acrylic Polymer Development
Sustainability requirements are creating opportunities for manufacturers to develop polymers using bio-derived, recycled, or certified mass-balance feedstocks. In March 2025, Lubrizol and Suzano announced the pre-launch of Carbopol BioSense in Brazil, a polymer containing more than 98% natural-origin content and based on microfibrillated cellulose. The development combines polymer formulation expertise with renewable biomass technology and targets personal-care applications.
The move reflects a broader transition toward materials with lower environmental footprints, particularly in personal care, cosmetics, household products, and specialty formulations. Toagosei also obtained ISCC PLUS certification in 2025, supporting the use of recycled and biomass-derived raw materials across applicable chemical production pathways.
Water Reuse, Micropollutant Treatment, and Advanced Water Management
Water reuse is creating additional demand opportunities as municipalities and industrial facilities seek alternative water supplies and improved resource efficiency. European wastewater regulations are moving toward more advanced treatment, including nutrient removal, micropollutant treatment, water reuse, and improved energy performance. Larger treatment plants are also being pushed toward greater energy neutrality.
Industrial facilities provide another growth avenue through cooling-water systems, boilers, process-water treatment, and wastewater recycling. In 2025, Kemira acquired Water Engineering to expand its industrial water-treatment service capabilities in the United States, covering applications across manufacturing, food and beverage, healthcare, and other industrial sectors.
Category-wise Analysis
Product Type Insights
Co-polymer PAA is anticipated to account for 41.2% of the market share in 2026. Its position is supported by the ability to tailor polymer characteristics through different monomers, enabling improvements in dispersion, scale inhibition, chelation, stability, and electrolyte tolerance. For example, acrylic copolymers are widely used in industrial water treatment, cooling-water systems, detergents, and specialty formulations where multiple performance functions are required.
Copolymers are particularly relevant in water treatment and detergent formulations containing inorganic salts, surfactants, and builders. They help disperse particles and reduce mineral deposits, supporting equipment efficiency and formulation stability.
Products such as Lubrizol's Noverite polymer range demonstrate the use of acrylic copolymer and terpolymer chemistry in home care and industrial applications. The broad performance range of copolymers allows manufacturers to develop application-specific grades. As water-treatment systems become more demanding and detergent and personal-care formulations become more concentrated, demand for polymers offering consistent performance under challenging chemical conditions is expected to increase.
Homo-polymer PAA is anticipated to be the fastest-growing, supported by demand for dispersants, scale-control agents, thickeners, and formulation stabilizers. Its relatively simple polymer structure enables predictable performance in applications requiring consistent viscosity, dispersion, or deposit control. Homo-polymer acrylic systems are also widely used in personal care, pharmaceuticals, coatings, and industrial formulations.
Crosslinked acrylic polymers such as carbomer-type materials provide viscosity modification, suspension stabilization, and emulsion control in products including gels, creams, lotions, and pharmaceutical formulations. Industrial applications further benefit from consistent scale inhibition and dispersion performance. Meanwhile, ter-polymers remain important for specialized applications requiring multiple functions, while bio-based acrylic polymer systems are emerging as manufacturers respond to renewable-feedstock and sustainability requirements.
Application Insights
Water & wastewater treatment is anticipated to account for approximately 37.8% of the market share. PAA is used for mineral precipitation control and dispersion in cooling-water circuits, boilers, industrial process-water systems, desalination facilities, and wastewater treatment plants. Its ability to interact with mineral particles and inhibit deposits such as calcium carbonate and calcium sulfate helps maintain heat-transfer efficiency and reduce maintenance requirements. For example, acrylic polymers are used in cooling towers and boiler-water treatment programs to control scale and maintain system performance.
Demand is supported by expanding wastewater treatment infrastructure, industrial water recycling, and stricter water-quality requirements. Suppliers are also developing higher-performance polymers that provide effective treatment at lower dosages and under high-mineral or high-temperature conditions.
The detergents & cleaners segment is anticipated to be the fastest-growing application, driven by concentrated formulations, improved cleaning performance, and demand for multifunctional ingredients. Acrylic polymers provide anti-redeposition, dispersion, chelation, builder, and scale-control properties in household and industrial cleaning products. For example, Lubrizol's Noverite K-797 is an acrylic terpolymer used in dish care, fabric care, hard-surface cleaning, and automotive care. It provides builder, chelation, and anti-redeposition functions that support cleaning performance.
Growth is also linked to detergent formulations designed for varying water hardness and lower-phosphate systems. Paints, coatings, and inks remain important applications because acrylic polymers support dispersion and rheological control, while polyacrylate-based materials also serve specialized roles in superabsorbent polymers and personal-care formulations.
Regional Insights
North America Polyacrylic Acid Market Trends
North America represents a mature and diversified market for polyacrylic acid, supported by established water-treatment infrastructure, industrial chemical consumption, detergent and personal-care manufacturing, and specialty-polymer capabilities. The U.S. is the principal demand center, while Canada provides additional opportunities through industrial water treatment, mining, chemicals, and municipal infrastructure.
U.S. Polyacrylic Acid Market Trends
The U.S. market is supported by continued investment in wastewater and water infrastructure. The FY2025 federal budget included approximately US$1.24 billion for the Clean Water State Revolving Fund, supporting wastewater, sewer, stormwater, and water-quality projects. Aging treatment systems and industrial facilities are also encouraging investment in scale control, water recycling, and process-water optimization. PAA suppliers can benefit from demand across cooling systems, boilers, food processing, chemicals, and manufacturing, while specialty-polymer producers are developing grades with improved dosage efficiency, formulation stability, and rheological control.
Canada Polyacrylic Acid Market Trends
Canada's market is shaped by municipal wastewater upgrades, industrial water management, and environmental compliance across manufacturing, mining, pulp and paper, and energy. Demand for treatment polymers is increasingly connected to water reuse and operational efficiency. Companies supplying dispersants, scale inhibitors, and formulation polymers can address both municipal and industrial requirements, while regional customers increasingly value technical support alongside chemical supply.
Europe Polyacrylic Acid Market Trends
Europe remains a significant market due to its established chemical industry, advanced wastewater infrastructure, detergent production, personal-care manufacturing, and stringent environmental requirements. Germany and France are important chemical and specialty-material centers, while the U.K. and Spain contribute substantial demand from water treatment and industrial applications.
Germany Polyacrylic Acid Market Trends
Germany benefits from its large chemical manufacturing base and demand for industrial water treatment, detergents, coatings, and specialty polymers. Sustainability requirements are also encouraging manufacturers to reduce energy use and carbon intensity. Across the acrylic value chain, this favors higher-efficiency production and lower-impact feedstocks. European wastewater regulations are further encouraging utilities to adopt advanced treatment and improve resource efficiency, creating opportunities for high-performance polymers and integrated treatment solutions.
France Polyacrylic Acid Market Trends
France has a strong acrylic-chemicals industry, illustrated by Arkema's €130 million investment at its Carling site. The project involves a new acrylic-acid purification process designed to increase production capacity while reducing site energy consumption by 25% and carbon intensity by 20%, with start-up planned for 2026. Acrylic acid from the site serves downstream applications including coatings, adhesives, superabsorbents, and water-treatment products. This investment strengthens regional acrylic supply while linking production expansion with decarbonization.
Asia Pacific Polyacrylic Acid Market Trends
Asia Pacific is likely to be the leading and fastest-growing regional market, accounting for 41.9% of market revenue. Its position reflects large-scale manufacturing, expanding wastewater infrastructure, detergent production, industrial water demand, and established acrylic-chemical supply chains.
China Polyacrylic Acid Market Trends
China is the region's largest country market, supported by extensive chemical manufacturing and growing demand for water-treatment chemicals. A major recent development is BASF's Zhanjiang acrylics complex, where mechanical completion of glacial acrylic acid and butyl acrylate plants was achieved in July 2025. The facilities are designed to provide approximately 400,000 metric tons of annual butyl acrylate capacity, improving regional acrylic supply and shortening customer lead times. The investment strengthens China's position as both a major consumer and production hub for acrylic-based materials.
India Polyacrylic Acid Market Trends
India represents a high-growth market as urbanization and industrialization increase wastewater-treatment requirements. Under AMRUT, substantial sewage-treatment capacity has been added through municipal sewerage and septage projects, creating opportunities for water-treatment chemicals and polymers. Industrial expansion in chemicals, textiles, food processing, pharmaceuticals, and manufacturing further supports demand for process-water treatment. Growing domestic treatment capacity and water-reuse initiatives are therefore broadening the addressable market for PAA-based scale-control and dispersion solutions.
Competitive Landscape
The global polyacrylic acid market is characterized by a concentrated group of global chemical producers alongside regional specialty-polymer manufacturers. BASF and Dow maintain significant positions, while Arkema, Lubrizol, Evonik, Ashland, Nippon Shokubai, Toagosei, SNF, Sumitomo Seika, Kemira, and other suppliers compete across specific applications and geographies.
Leading companies are focusing on specialty-grade development, upstream integration, geographic expansion, sustainable feedstocks, and application-specific technical support. Product differentiation increasingly depends on polymer architecture, formulation compatibility, dosage efficiency, and performance under demanding operating conditions. Suppliers are also expanding service-based models involving monitoring, dosing optimization, technical consulting, and long-term water-management programs.
Key Industry Developments:
- In September 2025, Kemira announced an agreement to acquire Water Engineering, Inc. for approximately US$150 million, expanding its industrial water-treatment services in the United States.
Companies Covered in Polyacrylic Acid Market
- BASF SE
- Dow Inc.
- Arkema S.A.
- The Lubrizol Corporation
- SNF Group
- Evonik Industries AG
- Nippon Shokubai Co., Ltd.
- Kemira Oyj
- Toagosei Co., Ltd.
- Sumitomo Seika Chemicals Co., Ltd.
- LG Chem Ltd.
- Ashland Inc.
- Sanyo Chemical Industries, Ltd.
- Wanhua Chemical Group Co., Ltd.
- Formosa Plastics Corporation
- Kao Corporation
Frequently Asked Questions
The global polyacrylic acid market is likely to be valued at US$ 3.7 billion in 2026.
The polyacrylic acid market is expected to reach US$ 5.8 billion by 2033.
Key trends include rising demand for water and wastewater treatment polymers, concentrated detergent formulations, specialty acrylic polymers, sustainable and bio-based materials, and high-performance grades with improved dosage efficiency and formulation stability.
By product type, co-polymer PAA is the leading segment, anticipated to account for approximately 41.2% of the market.
The polyacrylic acid market is projected to grow at a CAGR of 6.6% between 2026 and 2033.
Major companies include BASF SE, Dow, Arkema, The Lubrizol Corporation, and Evonik Industries AG.


