




- Pharmaceuticals
- Anti-Aging Medicine Market
Anti-Aging Medicine Market Size, Share and Growth Forecast, 2026 - 2033
Anti-Aging Medicine Market by Product Type (Hormone Replacement Therapy, Immune Enhancement Therapy, Antioxidant Therapy), Route of Administration (Oral, Injectable, Topical), Distribution Channel, and Regional Analysis for 2026 - 2033

Anti-Aging Medicine Market Size and Trends Analysis
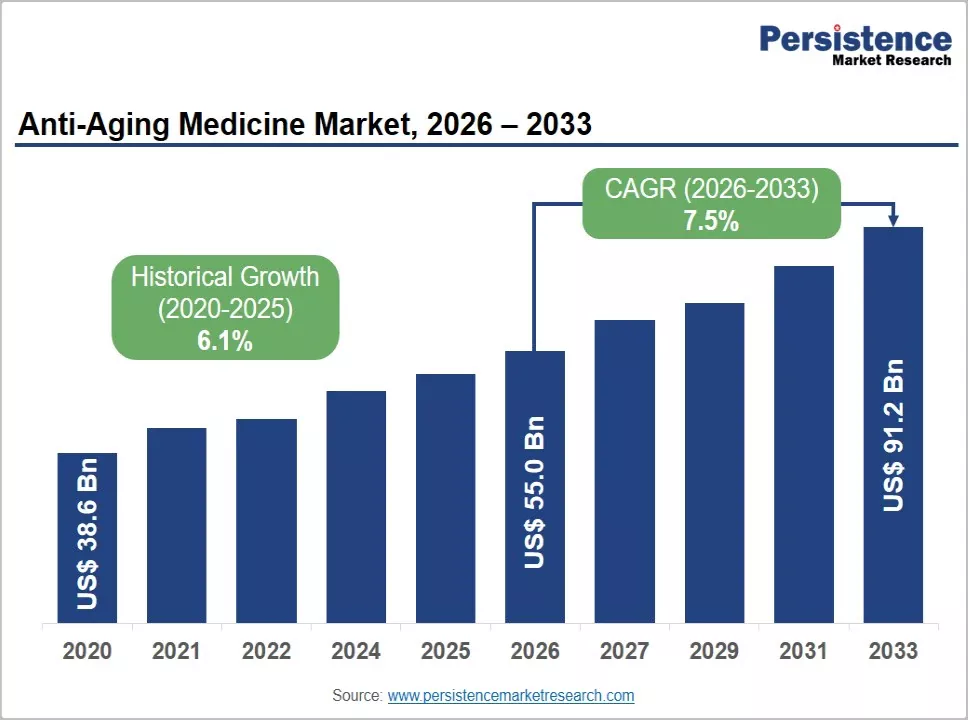
The global anti-aging medicine market size is likely to be valued at US$ 55.0 billion in 2026 and is projected to reach US$ 91.2 billion by 2033, growing at a CAGR of 7.5% during the forecast period 2026 - 2033, driven by population aging, rising demand for healthy aging interventions, and growing adoption of hormone-based and antioxidant therapies.
According to the World Health Organization, by 2030, one in six people globally is expected to be aged 60 years or older, expanding the addressable population for longevity medicine and preventive healthcare.
The market is shifting beyond cosmetic anti-aging toward hormonal management, immune support, antioxidant therapy, and personalized health monitoring. North America remains a key innovation hub, while Asia Pacific offers strong growth potential supported by aging populations, improving healthcare access, and expanding pharmaceutical capabilities.
Key Industry Highlights:
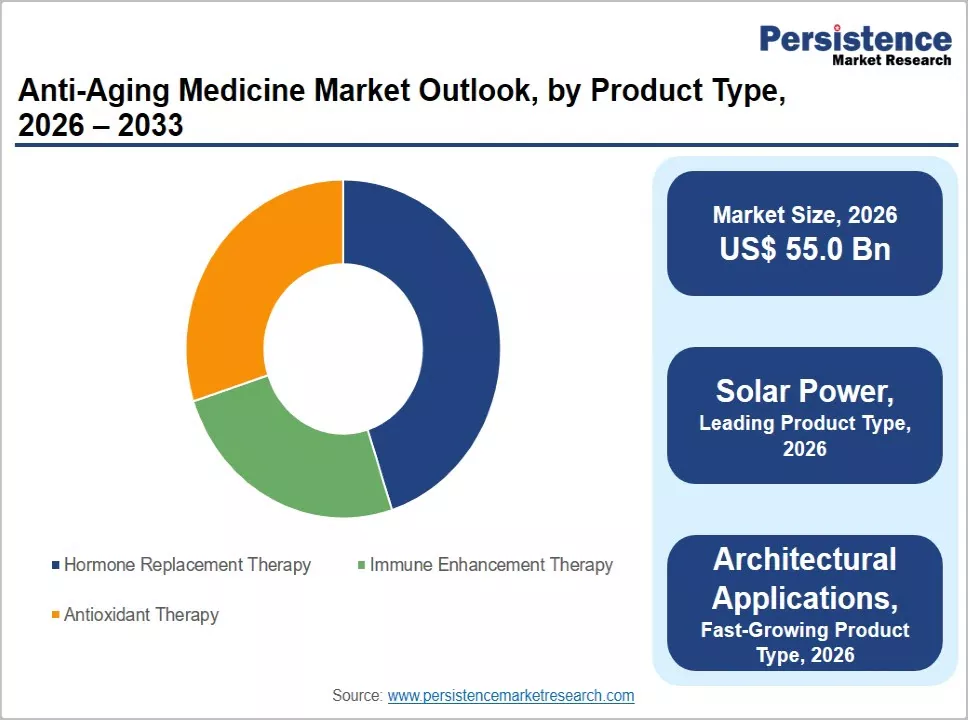
- Hormone replacement therapy is estimated to lead the product type segment with approximately 45% share in 2026, supported by established clinical applications and broad therapeutic adoption.
- Oral administration is estimated to account for approximately 40% of the market in 2026, consistent with the established preference for convenient, non-invasive treatment delivery. External HRT benchmarks report oral shares of about 40% in 2025.
- E-commerce is estimated to represent approximately 27% of distribution channel sales in 2026 and is positioned as the fastest-growing channel, supported by telehealth, digital pharmacy adoption, and recurring online healthcare purchasing.
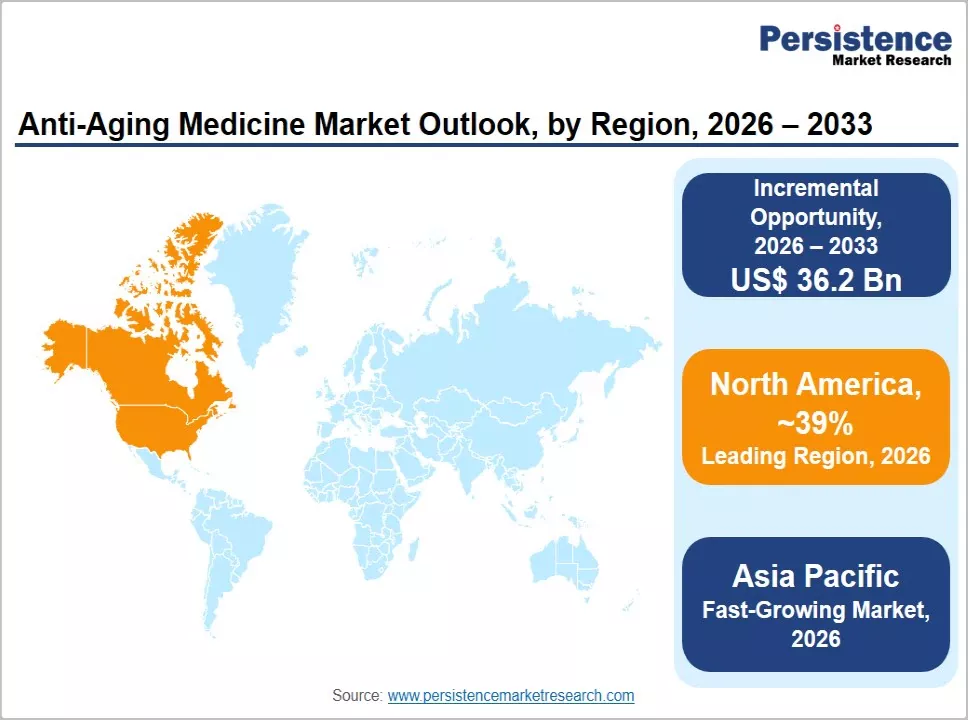
- North America remains the leading regional market, estimated at approximately 39% of global revenue in 2026, supported by advanced healthcare infrastructure, pharmaceutical innovation, and high adoption of longevity-focused treatments.
- Asia Pacific is expected to record the fastest regional expansion, supported by rapidly aging populations, increasing healthcare expenditure, and expanding pharmaceutical manufacturing. Comparable HRT and anti-aging pharmaceutical markets project Asia Pacific CAGRs of approximately 7% to 11%.
- 2026 market activity is increasingly centered on hormone-therapy labeling changes, digital longevity services, personalized treatment, and consumer health platforms, strengthening the integration of pharmaceutical therapies with preventive and healthy aging models.
DRO Analysis
Driver: Rapid population aging is expanding the addressable patient base
Population aging represents the strongest structural driver for the anti-aging medicine market because the incidence of age-associated physiological decline rises as the older population expands. The World Health Organization estimates that the global population aged 60 years and older will increase from 1.0 billion in 2020 to 1.4 billion by 2030 and 2.1 billion by 2050. The WHO also reports that global life expectancy at birth reached 73.3 years in 2024, up 8.4 years from 1995. This demographic shift increases demand for therapies addressing hormonal decline, oxidative stress, immune deterioration, and age-associated conditions.
The commercial implication is a larger population seeking to maintain functionality rather than simply treating established disease. In the U.S., adults aged 65 years and older reached 61.2 million in 2024, representing 18.0% of the population. China had 323.4 million people aged 60 years and older in 2025, equivalent to 23.0% of its population. These trends support sustained demand for healthy aging, preventive medicine, hormone management, and longevity-focused treatment models.
Restraint: Regulatory uncertainty and clinical evidence requirements constrain therapeutic adoption
A structural restraint is the distinction between therapies that treat recognized medical conditions and products marketed broadly as interventions against aging itself. Regulators generally require evidence for a defined disease or medical indication, which can complicate development and commercialization of therapies positioned around biological aging. Hormone replacement therapy illustrates this complexity. In February 2025, the U.S. Food and Drug Administration required testosterone products to incorporate findings from the TRAVERSE trial and postmarket blood-pressure studies while retaining limitations around age-related hypogonadism.
The evidence burden also raises development costs and lengthens commercialization timelines for emerging anti-aging therapies, particularly senolytics, cellular therapies, and other interventions that target mechanisms of aging rather than a single disease. Safety monitoring can further limit adoption of invasive or systemic treatments. Consequently, established therapies with defined indications and long-standing clinical use retain an advantage over experimental longevity interventions, while manufacturers must demonstrate measurable clinical outcomes and maintain stringent pharmacovigilance.
Opportunity: Integration of longevity medicine with personalized preventive healthcare
The convergence of diagnostics, digital health, nutrition, hormonal assessment, and therapeutic interventions creates an opportunity to develop integrated personalized medicine models. Instead of selling a single anti-aging product, providers can combine biological-age assessments, metabolic monitoring, hormone evaluation, nutrition programs, and physician-supervised treatments. This approach aligns with the shift toward prevention as populations live longer and seek to maintain physical and cognitive function.
The opportunity is particularly strong in Asia Pacific. China had more than 323 million people aged 60 years and older in 2025, while Japan's population aged 65 years and older represented 29.3% of the population in 2024. India is expected to see its elderly population exceed 20% of the total population by 2050. These large aging populations create significant potential for preventive longevity clinics, pharmaceutical therapies, digital monitoring, and specialized anti-aging medicine services.
Category-wise Analysis
Product Type Insights
Hormone replacement therapy is estimated to remain the leading product type, accounting for approximately 45% of the global anti-aging medicine market in 2026. Its leadership is supported by established clinical use in managing hormone deficiencies and menopausal symptoms, alongside a broad range of approved estrogen, progestogen, and testosterone formulations. The availability of oral, injectable, transdermal, and topical products also provides physicians with multiple treatment options, strengthening adoption across different patient groups.
Immune enhancement therapy is estimated to register faster growth as aging populations increase demand for interventions that support immune resilience and healthy aging. Antioxidant therapy is also expected to maintain a substantial position because oxidative stress is associated with cellular aging and chronic disease. Growth is increasingly supported by products combining immune or antioxidant mechanisms with personalized health assessment and preventive-care programs, broadening their role beyond conventional supplementation.
Route of Administration Insights
Oral administration is estimated to lead the route segment with approximately 40% share in 2026, supported by ease of administration, patient convenience, established pharmaceutical manufacturing, and suitability for long-term treatment. Oral formulations are widely applicable across hormone replacement and antioxidant therapies and can generally be administered without clinical supervision. These characteristics make oral products particularly suitable for recurring treatment and home-based healthcare.
Injectable administration is estimated to be the fastest-growing route as demand increases for physician-supervised therapies requiring systemic or targeted delivery. Injectable products are particularly relevant to hormone replacement and emerging longevity interventions where controlled dosing and clinical monitoring are important. Expansion of specialized longevity clinics, increasing acceptance of minimally invasive treatment, and development of longer-acting formulations are expected to support adoption, although regulatory requirements and administration costs can moderate penetration.
Distribution Channel Insights
Retail pharmacies are estimated to remain the leading distribution channel, accounting for approximately 34% of the market in 2026. Their position is supported by extensive physical networks, pharmacist access, established prescription fulfillment systems, and consumer familiarity. Retail pharmacies are particularly important for approved hormone therapies and other products requiring professional guidance but not necessarily hospital-based administration, providing a practical channel for recurring treatment.
E-commerce is estimated to be the fastest-growing distribution channel as digital pharmacies, telehealth, and online consultation platforms increasingly connect consumers with healthcare products. The channel offers convenient home delivery, recurring purchasing, broader product access, and integration with digital health services. Adoption is also gaining traction across emerging markets as internet penetration and digital healthcare infrastructure improve. In India, the expansion of e-pharmacy and telemedicine services is strengthening the digital pathway for health and wellness purchases.
Regional Insights
North America Anti-Aging Medicine Market Trends
North America is estimated to remain the leading regional market, accounting for approximately 39% of the global anti-aging medicine market in 2026. The region benefits from advanced pharmaceutical R&D, high healthcare spending, established hormone-therapy infrastructure, and a growing longevity medicine ecosystem. Beyond population aging, demand is increasingly shaped by younger consumers adopting preventive wellness and anti-aging practices earlier in life.
The U.S. is estimated to account for approximately 87% of North American demand. The market is increasingly influenced by Gen Z and millennial consumers who treat wellness as a continuous, personalized activity rather than an occasional healthcare purchase.
McKinsey reported in 2025 that nearly 30% of U.S. Gen Z and millennial consumers said they were prioritizing wellness much more than a year earlier, while these groups represented 36% of U.S. adults but more than 41% of wellness spending. Their stronger interest in appearance, skin health, nutrition, biomonitoring, and preventive treatments is expanding the consumer base for longevity-oriented products. Product innovation is also moving toward personalized anti-aging solutions, including biomarker testing, biological-age assessment, AI-supported health analysis, advanced supplements, and longevity-focused skincare.
Canada is estimated to represent approximately 13% of the regional market. Demand is supported by preventive healthcare adoption and an aging consumer base, while digital health is improving access to specialist services outside major urban centers. Canadian consumers are also participating in the broader shift toward wellness products that combine nutrition, fitness, skin health, and healthy-aging objectives. This creates opportunities for digital-first longevity services and evidence-based functional products rather than conventional age-focused treatments alone.
Europe Anti-Aging Medicine Market Trends
Europe is estimated to account for approximately 28% of the global anti-aging medicine market in 2026, supported by established healthcare systems, pharmaceutical expertise, high life expectancy, and growing consumer interest in preventive health. Germany and the U.K. are estimated to represent approximately 24% and 19% of European demand, respectively. The regional market is increasingly moving toward evidence-backed healthy aging, personalized healthcare, and products that combine medical, nutritional, aesthetic, and digital-health functions.
Germany is estimated to account for approximately 24% of European demand. The country combines a large aging population with strong pharmaceutical and biotechnology capabilities, creating demand for hormone management, preventive diagnostics, and therapies addressing age-associated conditions.
Product innovation is increasingly extending into scientifically formulated longevity products and personalized health monitoring. The broader European consumer trend is also moving away from purely appearance-driven anti-aging toward products positioned around overall wellbeing, skin health, nutrition, and healthy aging. McKinsey's 2025 wellness research found that younger consumers increasingly prioritize skin and hair care, appearance, functional nutrition, and preventive wellness.
The U.K. is estimated to represent approximately 19% of the European market in 2026. The country has a strong biotechnology and digital-health ecosystem, supporting development of personalized aging interventions and consumer health platforms. Younger consumers are increasingly engaging with wellness through social media, digital services, supplements, fitness, and appearance-focused products, creating demand for convenient and personalized anti-aging solutions. Product development is also shifting toward longevity cosmeceuticals, which target biological mechanisms of skin aging rather than only visible signs.
Asia Pacific Anti-Aging Medicine Market Trends
Asia Pacific is estimated to represent approximately 23% of the global anti-aging medicine market in 2026 and is expected to record the fastest regional growth through 2033. China and Japan are estimated to account for approximately 38% and 27% of regional demand, respectively. Alongside population aging, the region is seeing stronger integration of digital health, preventive medicine, functional nutrition, aesthetic healthcare, and technology-enabled longevity services. Expanding pharmaceutical manufacturing also provides a cost and production advantage for new products.
China is estimated to account for approximately 38% of Asia Pacific demand. The country's market is moving beyond conventional age-related healthcare toward digitally enabled healthy aging, combining artificial intelligence, big-data analysis, telemedicine, and integrated care. A 2026 review of digital healthy aging in China identified AI, big data, and telemedicine as important components of emerging healthy-aging service models. This technology shift creates opportunities for personalized health monitoring, biological-age assessment, digital therapeutics, and data-driven recommendations alongside conventional anti-aging medicines.
Japan is estimated to account for approximately 27% of Asia Pacific demand and represents one of the region's most mature healthy-aging markets. Japan's longevity ecosystem increasingly combines preventive healthcare, nutrition, physical activity, community-based care, and research into aging biology. The 2025 World Longevity Summit in Kyotango emphasized healthy life expectancy, lifestyle medicine, dietary patterns, physical activity, and social connectedness as components of healthy longevity.
Japan is also experiencing a broader consumer shift toward healthy aging rather than simply looking younger. This supports demand for functional nutrition, skin-health products, diagnostics, supplements, and personalized wellness services.
Competitive Landscape
The global anti-aging medicine market is fragmented and highly diversified, with competition spanning pharmaceutical companies, biotechnology firms, consumer health brands, longevity-focused companies, and specialized clinics. The market covers hormone replacement, immune enhancement, antioxidant interventions, regenerative therapies, and personalized longevity programs, with pharmaceutical companies focusing on established therapies and regulatory compliance, while biotechnology and longevity companies emphasize novel mechanisms, biomarkers, cellular health, and next-generation treatments.
Leading players include AbbVie, Pfizer, Bayer, Novo Nordisk, Eli Lilly and Company, Viatris, Merck KGaA, Elysium Health, Life Extension, Juvenescence, and Cambrian BioPharma, with competition centered on clinical validation, product innovation, physician-led treatment models, personalized health monitoring, digital platforms, and broader access to longevity-focused therapies.
Key Industry Developments:
- In June 2026, Rohto Pharmaceutical joined the ASAGI Labs Longevity Consortium to advance collaboration among companies, academia, hospitals, and clinics focused on longevity research and commercialization. This supports the development of longevity technologies for preventive healthcare and consumer health.
- In April 2026, Life Biosciences raised US$80 million in Series D financing to support its ER-100 Phase 1 program and advance its partial epigenetic reprogramming pipeline. The funding strengthens cellular rejuvenation research and clinical development.
Companies Covered in Anti-Aging Medicine Market
- Pfizer Inc.
- Eli Lilly and Company
- Novo Nordisk A/S
- Bayer AG
- Viatris Inc.
- Merck KGaA
- Elysium Health
- Life Extension
- Juvenescence
- Cambrian BioPharma
- Unity Biotechnology
- Longevity Health Holdings
- Jupiter Neurosciences
- Prenetics Global
Frequently Asked Questions
The global anti-aging medicine market is estimated at US$55.0 billion in 2026.
The anti-aging medicine market is expected to be driven by the growing aging population, increasing focus on healthy aging and preventive healthcare, rising demand for hormone-based therapies, and advances in personalized longevity medicine. Growing consumer interest in wellness, biomarker-based health monitoring, antioxidant therapies, and digital health platforms is also supporting market development.
The anti-aging medicine market is projected to register a CAGR of 7.5% during the forecast period 2026 - 2033.
Expansion of personalized anti-aging therapies, development of advanced hormone and immune enhancement treatments, integration of biomarkers and artificial intelligence into longevity care, growth of digital health and telemedicine platforms, and increasing availability of anti-aging products through e-commerce channels are expected to create significant growth opportunities.
Key participants include AbbVie, Pfizer, Bayer, Novo Nordisk, Eli Lilly and Company, Viatris, Merck KGaA, Elysium Health, Life Extension, Juvenescence, Cambrian BioPharma, and Longevity Health Holdings.


