




- Pharmaceuticals
- Urothelial Cancer Drugs Market
Urothelial Cancer Drugs Market Size, Share, and Growth Forecast, 2026 - 2033
Urothelial Cancer Drugs Market by Drug Class (PD-1/PD-L1 Immune Checkpoint Inhibitors, Antibody-Drug Conjugates (ADCs), Others), Cancer Type (Urothelial Carcinoma (transitional cell carcinoma), Squamous Cell Carcinoma, Others), Line of Therapy and Regional Analysis for 2026 - 2033

Urothelial Cancer Drugs Market Size and Trends Analysis
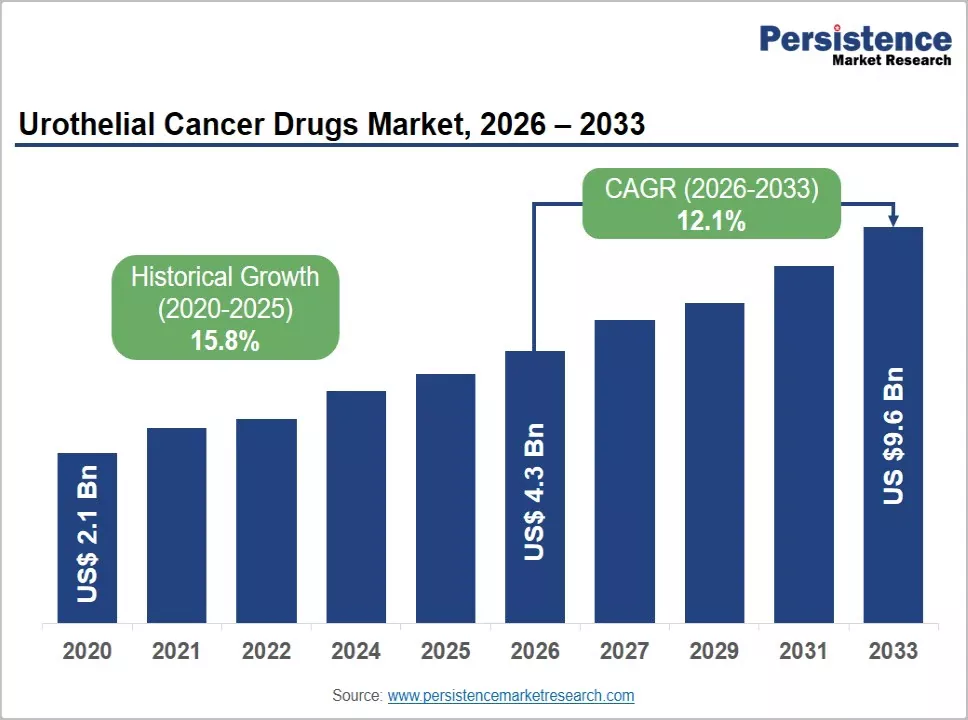
The global urothelial cancer drugs market size is likely to be valued at US$ 4.3 billion in 2026 and is expected to reach US$ 9.6 billion by 2033, growing at a CAGR of 12.1% between 2026 and 2033, driven by increasing use of immune checkpoint inhibitors, antibody-drug conjugates (ADCs), and biomarker-directed treatments.
Regulatory approvals are extending treatment options into earlier disease settings, including perioperative management of muscle-invasive bladder cancer. Treatment costs, reimbursement differences, and clinical safety requirements will influence commercial adoption.
Key Industry Highlights:
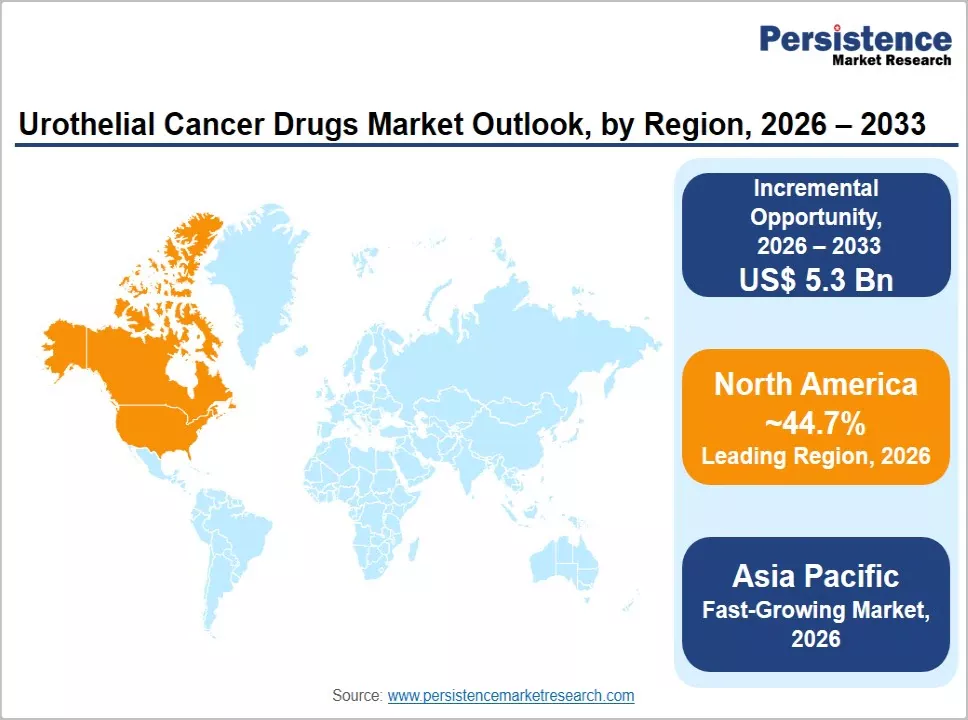
- Leading Region: North America, accounting for an anticipated 44.7% of the market share, supported by advanced oncology infrastructure, access to innovative therapies, and strong clinical research capabilities.
- Fastest-growing Region: Asia Pacific, driven by expanding oncology services, increasing access to advanced treatments, and broader adoption of immunotherapy and antibody-drug conjugate combinations.
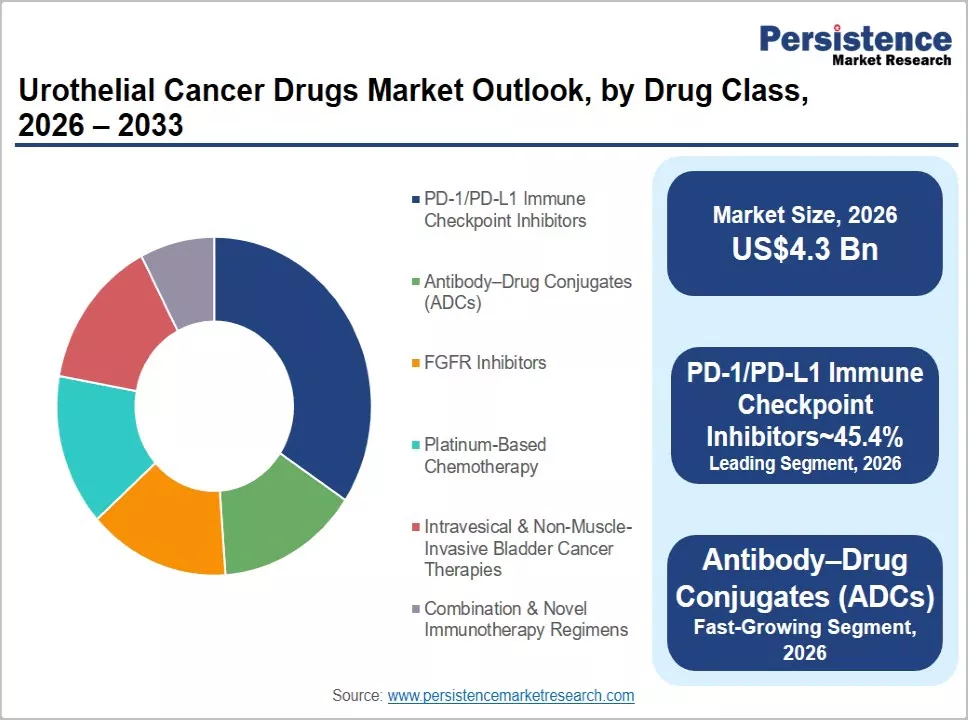
- Dominant Drug Class: PD-1/PD-L1 immune checkpoint inhibitors, anticipated to account for 45.4% of market revenue, supported by therapies such as pembrolizumab, nivolumab, durvalumab, and avelumab.
- Leading Cancer Type: Urothelial carcinoma, anticipated to represent 86.7% of market revenue, reflecting its predominance among bladder cancers and the availability of multiple treatment options across disease stages.
DRO Analysis
Drivers - Increasing Disease Burden and Demand for Advanced Treatment
Bladder cancer remains a substantial global healthcare burden. The International Agency for Research on Cancer estimated 614,298 new bladder cancer cases and 220,596 deaths worldwide in 2022. In the United States, the American Cancer Society estimates 84,530 new cases and 17,870 deaths in 2026.
Tobacco exposure, occupational exposure to certain chemicals, and population aging contribute to the disease burden. Urothelial carcinoma accounts for more than 90% of bladder cancers, creating a substantial treatment population for systemic and intravesical therapies. These epidemiological trends support demand for treatments that control recurrence, delay progression, and improve survival. As clinical management becomes more individualized, demand is also increasing for therapies selected according to tumor characteristics, previous treatment, and patient eligibility.
Clinical Advances and Expansion of Combination Therapies
Immunotherapy and ADC combinations are changing treatment patterns in advanced urothelial carcinoma. In the phase III EV-302 trial, enfortumab vedotin combined with pembrolizumab achieved a median overall survival of 31.5 months, compared with 16.1 months for platinum-based chemotherapy.
The combination reduced the risk of death by approximately 53% compared with chemotherapy. The U.S. Food and Drug Administration (FDA) approved the combination for locally advanced or metastatic urothelial cancer in December 2023. Subsequent approvals have expanded its use into muscle-invasive disease managed around surgery. These developments increase the role of advanced oncology medicines while creating opportunities for biomarker testing, infusion services, adverse-event monitoring, and combination-treatment development.
Restraint - High Treatment Costs and Clinical Management Requirements
Modern urothelial cancer treatment increasingly involves biologics, ADCs, companion diagnostics, and combination regimens that require specialized clinical infrastructure. Drug acquisition costs can be compounded by infusion administration, imaging, laboratory monitoring, and management of adverse events. Checkpoint inhibitors can cause immune-mediated toxicities, while enfortumab vedotin can cause skin reactions, peripheral neuropathy, and hyperglycemia.
FGFR-directed therapy requires molecular testing to identify eligible patients. These requirements can complicate treatment delivery, particularly in healthcare systems with limited specialist capacity or inconsistent reimbursement. The commercial impact is not limited to drug prices: treatment access also depends on diagnostic availability, institutional budgets, payer decisions, and the patient's ability to complete the prescribed regimen.
Opportunities - Expansion into Perioperative and Earlier-Stage Treatment
The treatment landscape is expanding beyond metastatic disease into neoadjuvant and adjuvant settings. In March 2025, the FDA approved durvalumab with gemcitabine and cisplatin before surgery, followed by durvalumab after surgery, for muscle-invasive bladder cancer.
In November 2025, the FDA approved enfortumab vedotin plus pembrolizumab as perioperative treatment for eligible patients with muscle-invasive bladder cancer who were ineligible for cisplatin. In July 2026, the FDA expanded this perioperative combination to patients undergoing cystectomy who were eligible for cisplatin as well. These developments expand the potential treatment population and create opportunities for longer treatment pathways. Manufacturers with established oncology portfolios can strengthen their positions through clinical evidence, coordinated care programs, and broader access.
Biomarker-Directed Treatment and Regional Market Development
Molecular profiling creates opportunities for targeted treatment in patients with specific tumor alterations. Erdafitinib, for example, is approved in the United States for selected advanced urothelial carcinomas with susceptible FGFR3 genetic alterations after prior systemic treatment, subject to the approved prescribing criteria. Wider access to testing can improve identification of eligible patients and support more efficient treatment selection. Asia Pacific offers additional potential through its large population base and growing oncology infrastructure.
China recorded an estimated 92,883 new bladder cancer cases in 2022, while Japan recorded 34,568. Manufacturers can pursue regional growth through regulatory submissions, local distribution partnerships, clinical research, and differentiated pricing strategies. Execution will depend on healthcare affordability, diagnostic access, local approval requirements, and reimbursement conditions.
Category-wise Analysis
Drug Class Insights
PD-1/PD-L1 immune checkpoint inhibitors are anticipated to account for approximately 45.4% of market revenue. Key therapies include pembrolizumab, nivolumab, durvalumab, and avelumab. These drugs are used across selected perioperative, locally advanced, metastatic, and maintenance settings. For example, avelumab is used as first-line maintenance therapy for eligible patients whose disease has not progressed after platinum-based chemotherapy, while pembrolizumab is used in approved monotherapy and combination regimens. Their established clinical roles and broad treatment applications support the segment's leading position.
Antibody-drug conjugates (ADCs) are likely to be the fastest-growing drug class. Enfortumab vedotin, which targets Nectin-4, is a key commercial example, particularly in combination with pembrolizumab. Results from the EV-302 trial and subsequent regulatory expansions have strengthened prospects for this combination in advanced disease and perioperative treatment. ADC adoption remains subject to safety monitoring, manufacturing complexity, and pricing pressures. Sacituzumab govitecan is not considered an active U.S. urothelial cancer product following withdrawal of its U.S. indication in November 2024.
Cancer Type Insights
Urothelial carcinoma is anticipated to account for approximately 86.7% of market revenue in 2026. Also known as transitional cell carcinoma, it represents the predominant form of bladder cancer and is treated through multiple therapeutic approaches. Examples include pembrolizumab-based regimens, enfortumab vedotin combinations, platinum-based chemotherapy, and intravesical treatments, depending on disease stage and clinical eligibility. Its large patient population and broad range of treatment options underpin its dominant market position.
Squamous cell carcinoma is anticipated to grow at a CAGR of 10.2%, although it remains smaller than urothelial carcinoma. Its growth outlook reflects potential treatment needs and research opportunities in less common bladder cancer histologies, rather than a shift in the dominant cancer type. Pure squamous cell carcinoma should be distinguished from urothelial carcinoma with squamous differentiation because their clinical characteristics and treatment approaches may differ.
Other categories include adenocarcinoma, small-cell or neuroendocrine bladder carcinoma, and upper-tract urothelial carcinoma. Smaller patient populations and limited clinical-trial data can constrain treatment development and commercial growth in these groups.
Regional Insights
North America Urothelial Cancer Drugs Market Trends
North America is the leading regional market, with an anticipated 44.7% share in 2026, supported by high-value oncology treatments, specialist cancer centers, molecular diagnostics, and clinical research. The U.S. is the region’s principal market, while Canada contributes through its established oncology services and public reimbursement systems.
U.S. Urothelial Cancer Drugs Market Trends
The American Cancer Society estimates 84,530 new bladder cancer cases and 17,870 deaths in the United States in 2026. Recent treatment expansions are reshaping demand. In March 2025, the FDA approved AstraZeneca’s Imfinzi (durvalumab) with chemotherapy before surgery, followed by durvalumab after surgery, for eligible patients with muscle-invasive bladder cancer. In May 2026, it approved Imfinzi with BCG for certain patients with high-risk non-muscle-invasive disease. These decisions extend immunotherapy into different treatment stages and broaden its commercial applications.
Canada Urothelial Cancer Drugs Market Trends
Canada’s opportunity is supported by specialist urology services and access to advanced oncology medicines. However, public reimbursement assessments and provincial funding decisions influence how quickly new therapies reach patients. Companies such as Merck, AstraZeneca, Astellas, and Pfizer benefit from established oncology portfolios, while the cost of combination regimens remains important to healthcare budgets.
Europe Urothelial Cancer Drugs Market Trends
Europe is a major market because of its specialist cancer infrastructure and shared EU marketing-authorization framework. However, national health technology assessments, pricing negotiations, and hospital funding influence uptake across member states. The United Kingdom operates a separate regulatory and reimbursement system.
Germany Urothelial Cancer Drugs Market Trends
Germany’s established hospital network and specialist oncology services support adoption of innovative treatments. In June 2026, the European Commission authorized Padcev (enfortumab vedotin), developed by Astellas and Pfizer, and Keytruda (pembrolizumab), marketed by Merck, as perioperative treatment for eligible patients with resectable muscle-invasive bladder cancer who cannot receive cisplatin. This creates another treatment option around surgery, although reimbursement and clinical implementation remain important to uptake.
U.K. Urothelial Cancer Drugs Market Trends
The U.K. offers opportunities through specialist cancer centers and national treatment pathways, but access depends on regulatory decisions and health technology assessments. Evidence demonstrating improved outcomes and cost-effectiveness can influence whether new combinations become routinely funded. This makes clinical data, pricing strategy, and engagement with healthcare decision-makers central to manufacturers’ commercial plans.
Asia Pacific Urothelial Cancer Drugs Market Trends
Asia Pacific is anticipated to be the fastest-growing regional market, driven by expanding oncology infrastructure, a large patient population, and wider access to advanced therapies. However, affordability, diagnostic availability, and differences in national reimbursement systems will shape the pace of adoption.
China Urothelial Cancer Drugs Market Trends
China’s market is supported by growing oncology capacity and increasing access to innovative medicines. In January 2025, Astellas and Pfizer’s Padcev plus Merck’s Keytruda received approval for locally advanced or metastatic urothelial cancer, expanding access to the combination beyond earlier treatment pathways. In July 2026, China’s drug evaluation authorities accepted an application for its use as perioperative treatment for muscle-invasive bladder cancer. This was an application milestone rather than an approval, but it signals potential expansion into earlier-stage treatment and could strengthen future demand if authorized.
Japan Urothelial Cancer Drugs Market Trends
Japan has a mature pharmaceutical market, established specialist care, and a regulatory system that supports access to advanced oncology medicines. In September 2024, Japan approved Padcev with Keytruda for first-line treatment of unresectable urothelial carcinoma. The decision expanded treatment options for advanced disease and reinforced the role of ADC-immunotherapy combinations in the region. Further growth will depend on clinical adoption, treatment affordability, and the ability of manufacturers such as Astellas and Merck to demonstrate value within Japan’s healthcare system.
Across Asia Pacific, pharmaceutical companies can pursue growth through local regulatory submissions, clinical research, and distribution partnerships. Nevertheless, high-cost combinations may initially remain concentrated in major urban hospitals and private healthcare settings, making affordability and wider treatment access key factors in long-term market expansion.
Competitive Landscape
The global urothelial cancer drugs market combines established multinational pharmaceutical companies with specialized biotechnology firms and manufacturers of traditional chemotherapy and intravesical products. Merck & Co., Astellas Pharma, Pfizer, AstraZeneca, and Johnson & Johnson have influential positions through approved immunotherapies, ADCs, and targeted treatments. Market positioning increasingly depends on the breadth of approved indications, clinical outcomes, regulatory execution, and access to specialist treatment centers.
Market leaders are prioritizing indication expansion, combination therapy, biomarker-directed treatment, and lifecycle management of established oncology brands. ADC developers emphasize targeted delivery and clinical differentiation, while immunotherapy companies seek to establish use across multiple treatment settings. Partnerships help share development costs and commercial capabilities. Emerging approaches include localized treatment for non-muscle-invasive disease, regional distribution agreements, companion diagnostics, and patient-access programs. Future differentiation will depend on clinical outcomes, safety, affordability, and reimbursement execution.
Key Industry Developments:
- In July 2026, Astellas Pharma and Pfizer announced that the U.S. FDA had expanded approval of Padcev (enfortumab vedotin) plus Keytruda (pembrolizumab) as treatment before and after surgery for muscle-invasive bladder cancer, regardless of cisplatin eligibility.
- In May 2026, AstraZeneca announced FDA approval of Imfinzi (durvalumab) combined with Bacillus Calmette-Guérin (BCG) for adults with BCG-naïve, high-risk
Companies Covered in Urothelial Cancer Drugs Market
- Merck & Co., Inc.
- Astellas Pharma Inc.
- Pfizer Inc.
- AstraZeneca plc
- Johnson & Johnson
- Bristol Myers Squibb
- F. Hoffmann-La Roche Ltd.
- Merck KGaA
- ImmunityBio, Inc.
- Ferring Pharmaceuticals
- UroGen Pharma Ltd.
- CG Oncology, Inc.
- Ono Pharmaceutical Co., Ltd.
- Gilead Sciences, Inc.
- Shanghai Junshi Biosciences Co., Ltd.
- Sun Pharmaceutical Industries Ltd.
Frequently Asked Questions
The global urothelial cancer drugs market is anticipated to reach US$4.3 billion in 2026.
The urothelial cancer drugs market is projected to reach US$9.6 billion by 2033.
Key trends include the growing use of immune checkpoint inhibitors, increased adoption of antibody-drug conjugates (ADCs), expansion into perioperative treatment, and the development of biomarker-directed therapies.
PD-1/PD-L1 immune checkpoint inhibitors are anticipated to lead the drug-class segment with approximately 45.4% market share.
The urothelial cancer drugs market is anticipated to grow at a CAGR of 12.1% from 2026 to 2033.
Major companies include Merck & Co., Inc., Astellas Pharma Inc., Pfizer Inc., AstraZeneca plc, and Johnson & Johnson.


