



- Off-Road Equipment & Machinery
- Mining Vehicle Attachments Market
Mining Vehicle Attachments Market Size, Share, and Growth Forecast 2026 - 2033
Mining Vehicle Attachments Market by Product Type (Augers, Hammers, Vibrators, Buckets, Blades, Dozers, Cutters, Others), Vehicle Type (Excavators, Loader Backhoes, Crawlers, Scoop Trams, Wheel Loaders, Continuous Miners, Others), and Regional Analysis for 2026 - 2033

Mining Vehicle Attachments Market Size and Trends Analysis
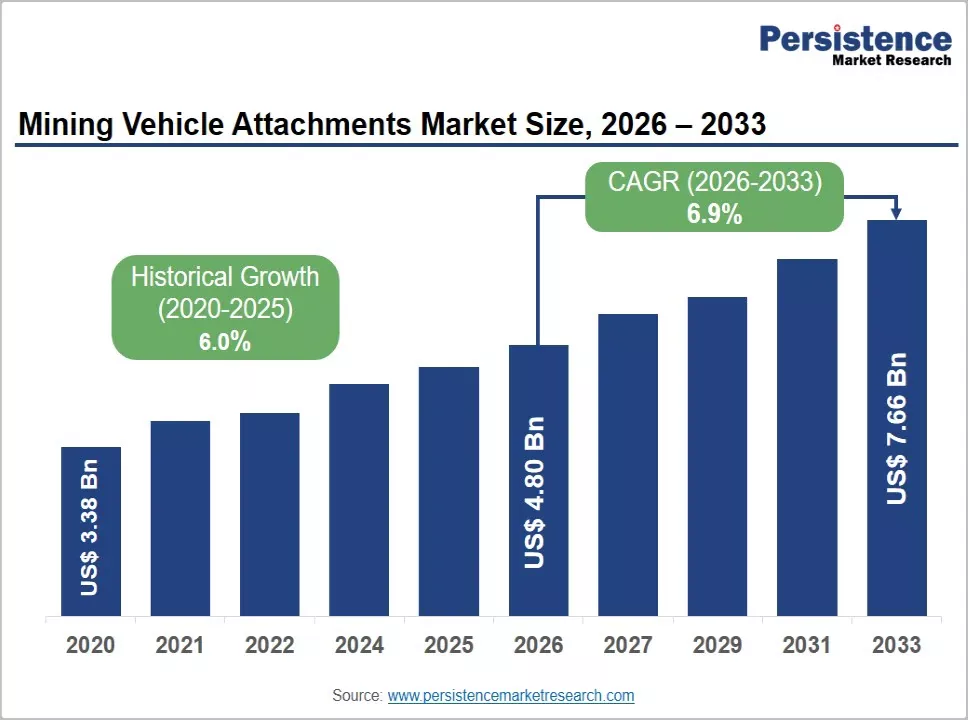
The global mining vehicle attachments market size is expected to be valued at US$ 4.80 billion in 2026 and is projected to reach US$ 7.66 billion by 2033, growing at a CAGR of 6.9% during the forecast period from 2026 to 2033.
This growth trajectory reflects a convergence of rising critical mineral demand, reinforced by the International Energy Agency (IEA)'s projections of substantial increases in lithium and cobalt supply requirements by 2030 to meet battery supply chain needs, and a structural shift toward modular, quick-coupler attachment systems that extend machine versatility without proportional capital expenditure. OEM strategists, procurement directors, and institutional investors with exposure to mining equipment are increasingly focusing on attachment demand as mining operators prioritize fleet utilization, operational flexibility, and equipment productivity.
Key Industry Highlights
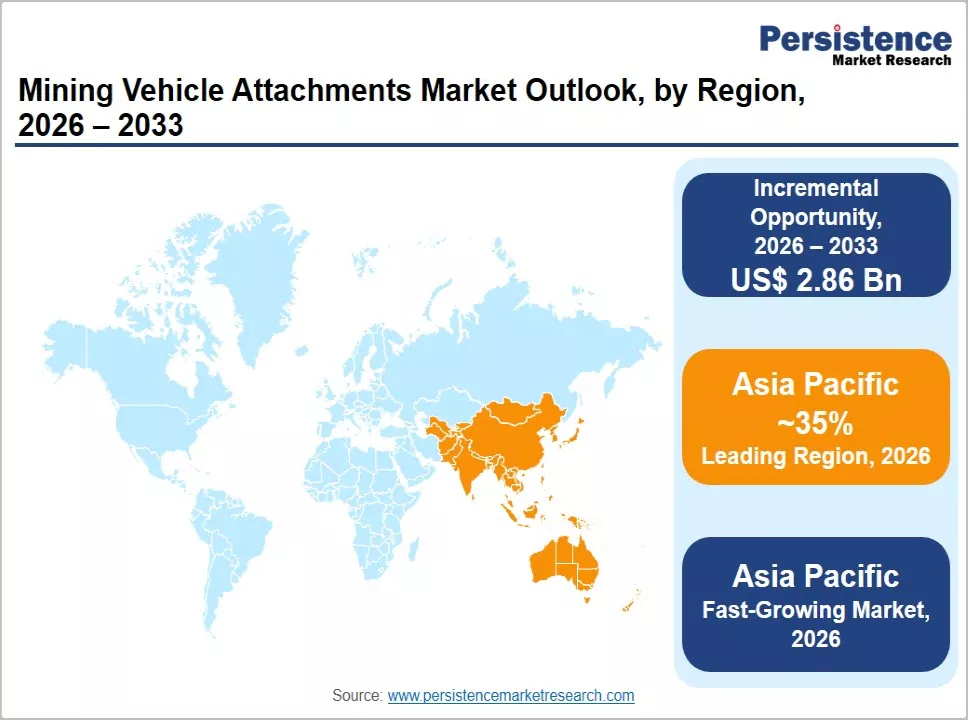
- Dominant Region: Asia Pacific is expected to lead the global market, accounting for 35% of the market share in 2026, driven by China's coal mine safety modernization initiatives and India's Coal India Limited expansion program. Both demand drivers are supported by long-term industrial and mining development priorities, making the region a key growth market for attachment suppliers.
- Leading Product Type: Buckets are the leading product type segment, holding a 52.0% share of the market in 2026, supported by their widespread application across mining operations and frequent replacement requirements arising from abrasive wear. Large fleet populations across open-pit iron ore, copper, and gold operations create a recurring revenue stream for attachment manufacturers.
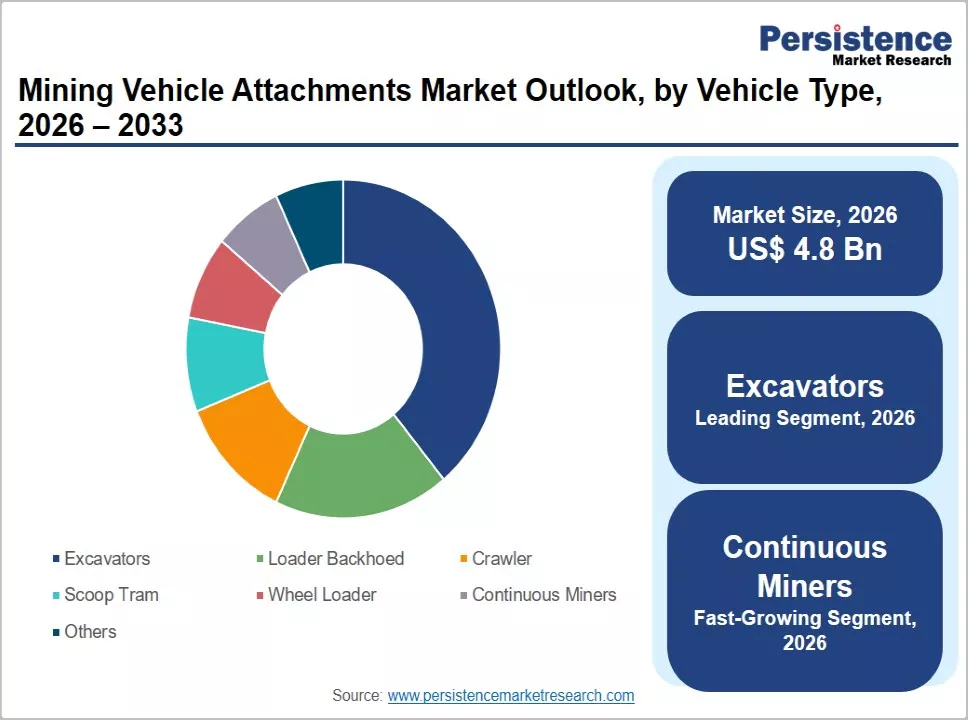
- Leading Vehicle Type: Excavators represent the leading vehicle type segment, supported by their versatility and compatibility with a broad range of attachments, including hydraulic breakers, buckets, and cutting tools. Their extensive deployment across surface mining operations sustains demand through OEM and aftermarket procurement channels.
- Fastest-Growing Vehicle Type: Continuous miners are likely to be the fastest-growing vehicle type segment, as underground coal, potash, and evaporite operations increasingly prioritize mechanized continuous excavation. Developments in cutter drums and pick-block configurations are supporting productivity improvements and replacement demand.
- Key Market Opportunity: Electrification of underground mining fleets represents a significant structural opportunity for the mining vehicle attachments market through 2033. As battery-electric machines from Sandvik, Epiroc, and Normet gain traction, attachment manufacturers are focusing on compatibility with electric hydraulic systems and revised power specifications. Suppliers that develop and validate compatible attachment systems are positioned to secure long-term supply agreements and strengthen their competitive positions.
Market Dynamics
Driver - Surging Critical Mineral Extraction Programs
Governments across North America, Europe, and the Indo-Pacific have designated critical mineral supply chains as strategic infrastructure, directly supporting permitted mine expansions and greenfield project development. The United States Geological Survey (USGS) identified 50 minerals as critical in its 2022 list, while subsequent legislation, including provisions within the Inflation Reduction Act (IRA), strengthened incentives for domestic critical mineral supply chains. This policy momentum creates sustained demand for excavation, loading, and material-handling attachments, including hydraulic rock hammers, high-capacity buckets, and precision auger assemblies. Mine operators are increasingly diversifying attachment inventories rather than purchasing additional base machines, supporting attachment procurement and improving existing fleet utilization.
Restraint - Compatibility Fragmentation Across OEM Platforms
The mining vehicle attachments sector has not converged on universal hydraulic and mechanical interface standards. Attachments engineered for Komatsu platforms are not readily transferable to Liebherr or Sandvik base machines without compatible adapter assemblies, increasing total ownership costs and complicating fleet management. This fragmentation discourages cross-platform purchasing and compels operators to maintain separate attachment inventories, tying up working capital. Standards bodies, including the International Organization for Standardization (ISO), have published guidelines under ISO 24410 for coupler safety, but OEM-specific interface designs continue to limit interoperability in practice.
Opportunity - Electrification of Underground Mining Fleets
The transition to battery-electric underground mining vehicles is reshaping attachment design requirements and creating a product replacement cycle across the mining vehicle attachments industry. Electric loaders and haul trucks have different hydraulic flow, pressure, and power integration requirements compared with diesel-powered equipment, necessitating modifications to attachment hydraulics and control systems.
Sandvik AB introduced its LH518B battery-electric loader, supporting the development of compatible equipment and attachment configurations. Suppliers that develop attachment families validated for electric base machine integration, particularly those meeting applicable machinery safety requirements under EU Machinery Directive 2006/42/EC during its applicable transition period, are positioned to capture early demand and secure long-term supply agreements.
Category-Wise Analysis
Product Type Insights
Why Do Buckets Command the Largest Share of the Mining Vehicle Attachments Market?
Buckets are projected to dominate the product type category, accounting for 52.0% of the market share in 2026, as no other attachment category offers comparable applicability across mining types, material classifications, and base machine configurations. Open-pit copper and iron ore operators rely on ground-engaging tool (GET)-equipped buckets for primary loading operations, while underground gold mines deploy narrow-profile mucking buckets on scoop trams to clear blasted rock from confined stopes. The combination of frequent replacement requirements driven by abrasive wear against hard rock and ore, along with large fleet populations, makes buckets the dominant revenue contributor. Hardox wear-plate specifications and lip-and-tooth system upgrades further sustain recurring aftermarket expenditure beyond the initial purchase.
Cutters are likely to be the fastest-growing product segment, supported by expanding tunnel development and selective mining applications where drill-and-blast methods are restricted or operationally impractical. Epiroc AB's introduction of its MC 11 mobile selective cutter in 2024 targeted selective excavation applications, demonstrating the broader development of cutting technologies for specialized mining and underground excavation environments.
Vehicle Type Insights
Excavators are expected to lead the vehicle type category, capturing nearly 39.0% of the market share in 2026, as their hydraulic architecture supports a wide range of interchangeable attachments, including hydraulic hammers, rotating cutters, and specialized buckets. Surface coal and copper operations routinely use the same excavator base machine across multiple attachment configurations within a single shift, switching between hydraulic breakers for secondary fragmentation and high-capacity buckets for material loading. This multi-attachment operating model concentrates procurement activity around excavator-compatible products and generates sustained demand across both OEM and aftermarket channels.
Continuous miners are likely to be the fastest-growing vehicle type segment, driven by expanding underground coal and potash operations prioritizing mechanized continuous excavation over conventional drill-and-blast methods. Komatsu Mining Corp., through its 14CM and 12CM series, has continued developing cutter drum and pick-block configurations, supporting higher excavation productivity in suitable underground mining conditions and stimulating replacement demand for cutting components in room-and-pillar operations.
Regional Analysis
North America Mining Vehicle Attachments Market Trends And Insights
North America is expected to hold around 25.0% of the global market share in 2026. The region's position is supported by a substantial base of operating surface and underground mines across the western United States and Canadian Shield, reinforced by IRA-linked critical mineral investments that are extending mine development activity and supporting fleet expansion. Near-term growth is expected to be shaped by permitting progress and the pace of copper and lithium project development through 2028.
U.S. Mining Vehicle Attachments Market Size
The U.S. is estimated to hold nearly 84.0% of the North American market share in 2026. Demand is concentrated in Arizona and Nevada copper operations and Wyoming coal basins, where large-scale surface excavation sustains recurring bucket and blade replacement requirements. Infrastructure investments and domestic critical mineral development initiatives are expected to support capital equipment and attachment procurement through the forecast period.
Canada Mining Vehicle Attachments Market Size
Canada is projected to account for nearly 16.0% of the North American market share in 2026. Ontario and British Columbia gold and base-metal operations anchor domestic demand, with underground excavation attachments, particularly rock hammers and auger assemblies, contributing to the core procurement mix. Continued development of the Ring of Fire chromite and nickel corridor is expected to introduce additional attachment demand as infrastructure development and mining projects progress.
Europe Mining Vehicle Attachments Market Trends And Insights
Europe is expected to account for 20.0% of the global market share in 2026. The European Commission's Critical Raw Materials Act, which entered into force in 2024, establishes 2030 benchmarks for domestic extraction, processing, and recycling of strategic raw materials. These targets are supporting renewed interest in lithium, phosphate, and rare earth mining projects across Scandinavia, the Iberian Peninsula, and Eastern Europe. Regulatory priorities and domestic supply chain objectives are supporting project development and attachment demand across mining operations.
Germany Mining Vehicle Attachments Market Size
Germany is anticipated to lead the European market, commanding nearly 35.0% of the regional market share in 2026. Germany's position reflects its established potash and salt mining industry, with operators including K+S AG generating consistent demand for continuous miner cutting components and loading attachments across its Werra and Weser mining operations. Aftermarket demand associated with the mechanization and modernization of underground mining operations provides a sustained growth opportunity for attachment suppliers.
U.K. Mining Vehicle Attachments Market Size
The U.K. is projected to account for 29.0% of the European market share in 2026. Aggregate, construction stone, and potash-related mining activities, including development of Anglo American's Woodsmith Project, support demand for specialized excavation and material-handling equipment. The project's development activities are expected to generate additional demand for underground excavation equipment and associated attachments as construction and mining operations advance.
What Makes Asia Pacific the Dominant Region in the Global Mining Vehicle Attachments Market?
Asia Pacific is expected to dominate the global market by holding around 35.0% share in 2026. Its dominant position reflects the concentration of high-volume coal, iron ore, and copper extraction activities across the region. China's state-directed mine modernization initiatives and India's expanding coal production programs generate sustained attachment procurement demand at a scale that few other regions can match. The region is also projected to expand at an estimated CAGR of 6.2% through 2033, supported by infrastructure-led mineral demand and mining investments across Southeast Asian economies.
China Mining Vehicle Attachments Market Size
China is expected to hold nearly 37.0% share of the Asia Pacific market in 2026. The National Development and Reform Commission (NDRC)'s ongoing coal mine safety and capacity modernization initiatives are encouraging operators to upgrade attachment inventories, particularly hydraulic rock breakers and mechanized loading buckets, as mining operations adopt more advanced equipment and safety practices. Continued expansion of rare earth and tungsten extraction projects in Inner Mongolia is expected to sustain attachment demand through the forecast period.
India Mining Vehicle Attachments Market Size
India is estimated to command nearly 30.0% share of the Asia Pacific market in 2026. Coal India Limited (CIL), the world's largest coal producer, is executing a multi-year surface mining expansion program targeting annual production capacity of one billion tons, directly supporting procurement of dragline, shovel, and wheel loader bucket attachments. Revisions to mining policies under India's Mines and Minerals (Development and Regulation) framework are also supporting private-sector participation and mine development, broadening the attachment procurement base beyond CIL.
Competitive Landscape
The global mining vehicle attachments market operates as a moderately consolidated market at the premium tier, anchored by global OEMs Caterpillar, Komatsu Limited, Sandvik AB, Liebherr, and Hitachi Construction Machinery Co. Ltd. which leverage integrated service networks and proprietary coupling systems to retain key accounts. Mid-market competition intensifies around Paladin Attachments, NPK Construction Equipment, Inc., and Rockland Manufacturing Company, each competing on price-performance, lead time, and aftermarket parts availability.
Specialist regional players including Jaws Pty Ltd. and Mining Attachments QLD Pty Ltd. hold defensible positions in the Australian market by offering custom engineering for hard-rock and narrow-vein applications that global catalogues do not address. Winning in this landscape ultimately comes down to wear-life performance data, coupler compatibility breadth, and the depth of technical field support.
Key Industry Developments
- In October 2026, ONERugged, a brand of Emdoor Information, expanded its Vehicle PC portfolio with rugged vehicle-mount computers designed for precision agriculture and autonomous mining. The company introduced smart farming and mining vehicle tablets that supported automated steering, centimeter-level positioning, real-time equipment monitoring, and data-driven operations. The farming tablets integrated with seeders, fertilizer spreaders, and crop sprayers to improve field precision and resource utilization.
- In September 2026, Hexagon launched its next-generation Vehicle Intervention System (VIS) to help surface mining operators prevent vehicle collisions and improve operational safety. The system integrated autonomous collision prevention, safety rule enforcement, and fail-safe protection within an EMESRT Level 9 solution. Following successful completion of the University of Pretoria independent Technology Readiness Level 4 (TRL4) validation program, VIS became the first open-pit Level 9 solution to achieve this milestone. The technology automatically inhibited propulsion, applied braking or retardation, enforced safe following distances, controlled overspeed conditions, and placed vehicles in a safe state when critical system faults occurred.
Companies Covered in Mining Vehicle Attachments Market
- Rockland Manufacturing Company
- Komatsu Limited
- Liebherr
- Caterpillar
- Paladin Attachments
- NPK Construction Equipment, Inc.
- Sandvik AB
- Hitachi Construction Machinery Co. Ltd.
- Jaws Pty Ltd.
- Mining attachments qld pty ltd
Frequently Asked Questions
The global mining vehicle attachments market is expected to be valued at US$ 4.80 billion in 2026.
Government-mandated critical mineral extraction programs formalized through instruments such as the European Commission's Critical Raw Materials Act and the rapid adoption of hydraulic quick-coupler systems that allow operators to deploy multiple attachment types on a single base machine, improving fleet utilization and reducing capital expenditure per task cycle.
Buckets hold the largest market share of 52.0% in 2026, owing to their universal applicability across open-pit and underground operations and their high replacement frequency due to abrasive wear against ore and hard rock.
Asia Pacific is likely to lead the market with a 35% share in 2026, supported by China's state-directed coal mine modernization program and India's ongoing surface mine expansion under Coal India Limited.
The most significant opportunity lies in developing attachment systems certified for battery-electric underground mining platforms, as OEMs including Epiroc AB and Sandvik AB scale electric loader and drill fleets toward commercial mainstream adoption.
Leading companies include Caterpillar, Komatsu Limited, Sandvik AB, Liebherr, Hitachi Construction Machinery Co. Ltd., Paladin Attachments, and NPK Construction Equipment, Inc.


