




- Biotechnology
- Bioengineered Protein Drugs Market
Bioengineered Protein Drugs Market Size, Share, and Growth Forecast 2026 - 2033
Bioengineered Protein Drugs Market by Drug Type (Monoclonal Antibodies, Recombinant Proteins, Therapeutic Enzymes, Peptide Hormones, Fusion Proteins, Blood Factors, Others), Application (Cancer, Diabetes, Autoimmune Diseases, Blood Disorders, Infectious Diseases, Others), Route of Administration (Injectable, Oral, Others), End-User (Hospitals, Specialty Clinics, Pharmaceutical & Biotechnology Companies, Research Institutes, Others), and Regional Analysis for 2026 - 2033

Bioengineered Protein Drugs Market Size and Trends Analysis
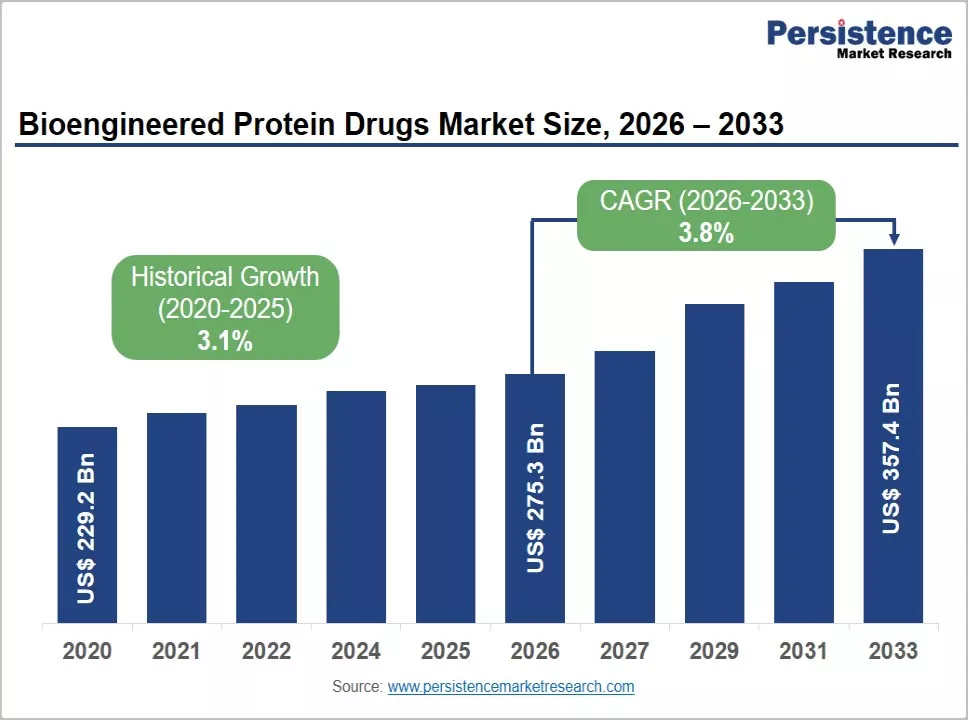
The global bioengineered protein drugs market is expected to be valued at US$ 275.3 billion in 2026 and is projected to reach US$ 357.4 billion by 2033, growing at a CAGR of 3.8% between 2026 and 2033. The rising burden of cancer, diabetes, obesity, and autoimmune diseases is a key factor sustaining demand for protein-based therapeutics.
The International Agency for Research on Cancer (IARC) recorded around 20 million new cancer cases in 2022, while the International Diabetes Federation (IDF) estimated that 589 million adults were living with diabetes in 2024. Monoclonal antibodies, GLP-1 peptide hormones, and fusion proteins offer high target specificity and established clinical benefits, supporting their use across these conditions. Market growth is further supported by the development of next-generation bispecific antibodies, long-acting peptides, and subcutaneous formulations. However, pricing reforms and patent expiries are expected to moderate overall market value growth.
Key Industry Highlights
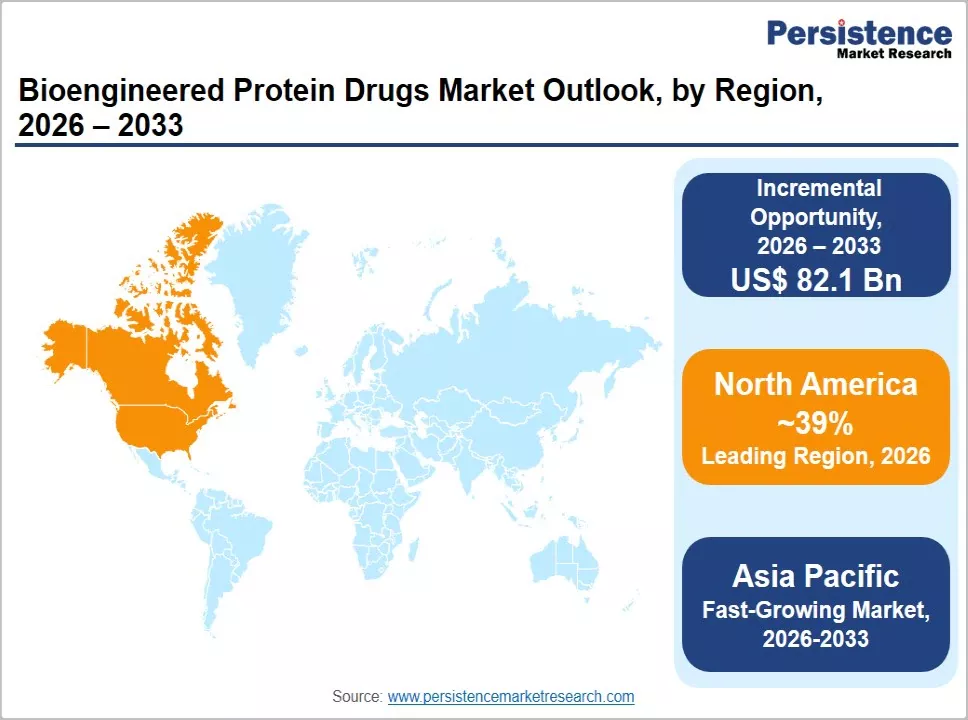
- Leading Region: North America is expected to hold around 39% share of the market in 2026, supported by high biologics spending, strong innovation pipelines, early access to new therapies, and a high prevalence of cancer, diabetes, and obesity.
- Fastest-Growing Region: Asia Pacific is projected to register a CAGR of around 5.6% between 2026 and 2033, driven by China's expanding biotechnology sector, broader National Reimbursement Drug List (NRDL) coverage, biosimilar manufacturing capabilities, and improving access to healthcare.
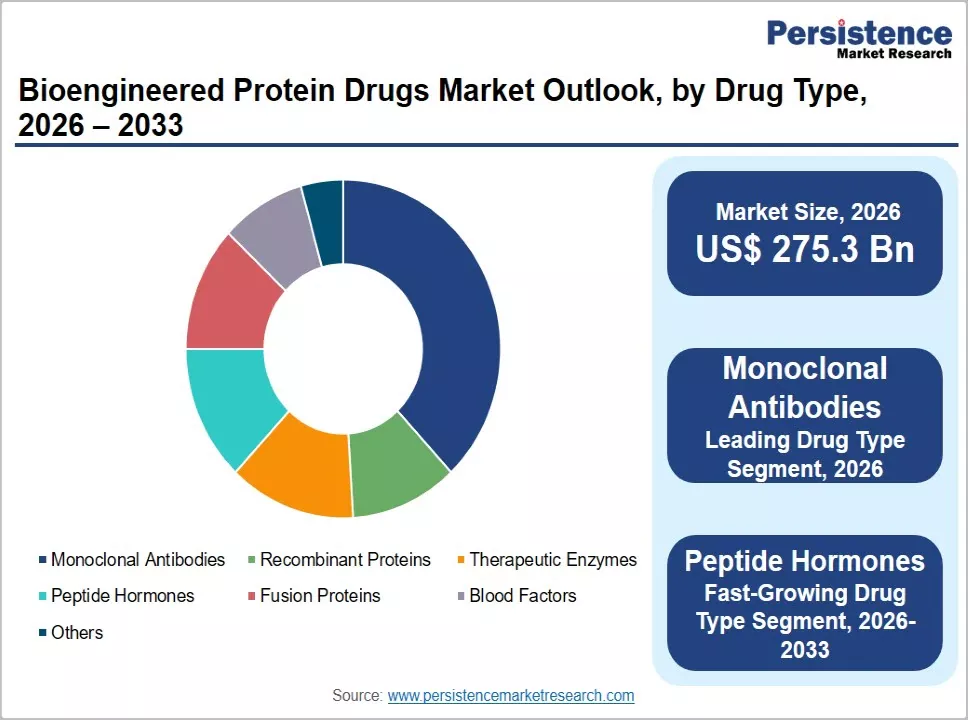
- Dominant Segment: Monoclonal antibodies represent the leading drug type category, holding a 33% market share in 2026, owing to established blockbuster therapies in oncology and immunology, broad clinical applications, and premium pricing.
- Fastest-Growing Segment: Peptide hormones represent the fastest-growing drug type, driven by increasing adoption of GLP-1 and dual incretin therapies for obesity and diabetes, alongside their expanding role in cardiovascular risk reduction and sleep apnea management.
- Key Market Opportunity: Rising demand for bispecific antibodies, antibody-drug conjugates, and long-acting peptides offers a significant opportunity, supported by partnerships with Asia Pacific biotechnology innovators and investment in subcutaneous and oral drug delivery technologies.
Market Dynamics
Drivers - Rising Prevalence of Chronic and Life-Threatening Diseases
The growing global burden of chronic disease is a key demand catalyst for bioengineered protein drugs. IARC projects that annual new cancer cases are projected to exceed 35 million by 2050, a 77% increase from 2022, and antibody-based immunotherapies are now used across dozens of tumor types. The IDF Diabetes Atlas expects the number of adults with diabetes to reach 853 million by 2050, sustaining long-term demand for insulin analogs and GLP-1 receptor agonists.
Obesity adds another large patient pool, with the World Health Organization (WHO) reporting that 890 million adults were living with obesity in 2022. Autoimmune conditions such as rheumatoid arthritis, psoriasis, and inflammatory bowel disease also require lifelong biologic therapy, creating recurring, predictable demand for monoclonal antibodies and fusion proteins across hospital and specialty care settings worldwide.
Strong Regulatory Approval Pipeline and Technological Advances
A steady flow of regulatory approvals and advances in protein engineering are expanding the range of treatable diseases. The U.S. Food and Drug Administration (FDA) Center for Drug Evaluation and Research approved 50 novel drugs in 2024, roughly one-third of which were biologics, and the agency marked its 100th monoclonal antibody approval in 2021. Engineering platforms now enable bispecific antibodies, antibody-drug conjugates, Fc-modified long-acting proteins, and enzyme-enabled subcutaneous formulations that improve efficacy and convenience.
Recent examples include the FDA approvals of subcutaneous Opdivo Qvantig in December 2024 and Keytruda Qlex in September 2025, which shorten administration time for cancer patients. Continuous manufacturing, high-titer cell lines, and single-use bioreactors are also lowering production costs, helping companies scale biologics supply and broaden access in both developed and emerging healthcare systems.
Restraints - Biosimilar Competition and Patent Expiries
Loss of exclusivity for major biologics is eroding revenue across established product classes. In the U.S., biosimilars of Humira launched in 2023, and biosimilars of Stelara entered the market in 2025, while the FDA has approved more than 60 biosimilars in total. Europe has an even longer track record, with the European Medicines Agency (EMA) authorizing its first biosimilar in 2006 and more than 100 since. Several blockbuster antibodies, including pembrolizumab, nivolumab, and denosumab, face patent expiries or biosimilar entry before 2030. Biosimilar uptake programs in Europe have delivered price reductions often exceeding 50% for originator molecules. These dynamics shift volume to lower-priced products and compress the value growth of the overall market even as patient numbers continue rising steadily.
High Development Costs and Pricing Pressure
Protein drug development remains expensive and risky, while governments are intensifying pricing controls. A study by the Biotechnology Innovation Organization (BIO) found that only about 7.9% of drug candidates entering Phase I clinical trials between 2011 and 2020 eventually gained approval, and complex biologics require costly cell-culture manufacturing, purification, and cold-chain logistics.
Under the Inflation Reduction Act, the Centers for Medicare & Medicaid Services (CMS) negotiated prices for Enbrel, Stelara, and insulin products Fiasp and NovoLog effective January 2026, and selected semaglutide products for the second negotiation cycle. China's volume-based procurement of insulin in 2021 cut average prices by about 48%. Such measures reduce revenue per patient and can discourage investment in certain therapeutic areas.
Opportunities – Rising Demand for Peptide Hormones for Obesity and Cardiometabolic Disease
Rising demand for peptide hormones creates opportunities, supported by the proven success of GLP-1 and dual incretin therapies. Novo Nordisk gained FDA approval in March 2024 for Wegovy to reduce the risk of major adverse cardiovascular events, based on the SELECT trial that showed a 20% risk reduction, while Eli Lilly and Company secured FDA approval for Zepbound in obstructive sleep apnea in December 2024. Label expansions into heart failure, chronic kidney disease, and metabolic dysfunction-associated steatohepatitis are widening the eligible population.
The Centers for Disease Control and Prevention (CDC) reports adult obesity prevalence of about 40% in the U.S., and similar trends are emerging in Asia and the Middle East. Companies investing in oral peptides, monthly injectables, and expanded manufacturing capacity are well positioned to capture this rapidly growing segment of the weight loss drugs space.
Bispecific Antibodies, ADCs, and Asia Pacific Innovation
Next-generation antibody formats and the rise of Asia Pacific innovators offer substantial growth potential. Bispecific antibodies and antibody-drug conjugates combine multiple mechanisms or targeted payload delivery, improving outcomes in hard-to-treat cancers. In 2024, the Phase III HARMONi-2 trial showed that Akeso's PD-1/VEGF bispecific ivonescimab reduced the risk of disease progression or death by 49% compared with pembrolizumab in PD-L1-positive non-small cell lung cancer, attracting global attention.
China's biotech sector has become a major source of in-licensed assets for Western companies, giving multinationals access to novel molecules at earlier and lower-cost stages. Meanwhile, expanding biologics manufacturing in South Korea, India, and Singapore supports biosimilar and contract manufacturing growth. Companies that combine novel antibody platforms with regional partnerships and local production can capture strong demand in the oncology drugs space through 2033.
Category-wise Analysis
Drug Type Insights
Monoclonal antibodies lead the drug type category with an estimated 33% market share in 2026, supported by their broad therapeutic applications and established clinical value. Medicines such as Keytruda, Dupixent, Darzalex, Opdivo, and Skyrizi are widely used to treat cancer, atopic dermatitis, asthma, multiple myeloma, psoriasis, and inflammatory bowel disease. Merck's Keytruda has more than 40 approved indications in the U.S., demonstrating the potential of a single antibody to address multiple patient populations. The FDA recorded its 100th monoclonal antibody approval in 2021, reflecting the growing role of antibodies in therapeutic development. Their target specificity, long half-life, and established clinical efficacy support premium pricing and sustained treatment demand.
Peptide hormones are projected to be the fastest-growing drug type segment through 2033, driven by rising adoption of GLP-1 and dual incretin therapies for obesity and diabetes. Expanding clinical applications, growing awareness of obesity-related complications, and continued development of next-generation peptide therapies further support segment growth.
Application Insights
Cancer leads the application category with an estimated 30% share in 2026, driven by the growing role of antibody-based immunotherapies and targeted biologics in oncology. The International Agency for Research on Cancer reported around 9.7 million cancer deaths in 2022. Immune checkpoint inhibitors, HER2-targeted antibodies, antibody-drug conjugates, and bispecific T-cell engagers are established treatment options across several cancers, including lung, breast, melanoma, gastrointestinal, and hematologic malignancies.
Clinical guidelines from the National Comprehensive Cancer Network and the American Society of Clinical Oncology increasingly support biologic therapies in earlier treatment settings, including neoadjuvant and adjuvant care. These developments extend treatment opportunities and support the segment's market value, alongside demand for premium oncology therapies.
Route of Administration Insights
Injectable dominates the route of administration category, accounting for an estimated 92% market share in 2026. Protein drugs are large, structurally complex molecules that are generally degraded by stomach acid and digestive enzymes, making intravenous and subcutaneous delivery essential for most antibodies, insulins, enzymes, and blood factors. Oral peptide bioavailability remains low for many molecules, even with absorption-enhancing technologies, limiting oral delivery to a smaller group of therapies, including oral semaglutide (Rybelsus).
The shift from intravenous infusion to subcutaneous administration further supports segmental growth. Products such as Opdivo Qvantig and Keytruda Qlex, along with autoinjectors and prefilled pens, support faster administration and greater convenience, including treatment in outpatient and home-care settings where appropriate.
End-User Analysis
Hospitals are expected to hold the position in the market while capturing around 46% share in 2026, supported by the administration of high-value protein drugs through oncology departments, infusion suites, and inpatient care facilities. Intravenous monoclonal antibodies, blood factors used in bleeding emergencies, thrombolytics, and enzyme replacement therapies often require trained healthcare professionals, monitoring for infusion reactions, and controlled storage conditions. Hospital pharmacies also manage high-cost biologics through formulary oversight and group purchasing arrangements, while hospital outpatient departments in the U.S. remain important treatment settings for cancer immunotherapy.
Specialty clinics are expected to be the fastest-growing end-user segment between 2026 and 2033, driven by the expansion of independent infusion centers, obesity and metabolic clinics, and rheumatology and dermatology practices. The shift toward lower-cost outpatient care, growing demand for specialized treatment, and wider use of biologics for chronic conditions further support adoption through specialty clinics.
Regional Analysis
North America Bioengineered Protein Drugs Market Trends and Insights
North America is expected to lead the global bioengineered protein drugs market with around 39% share in 2026, supported by high biologics spending, broad insurance coverage, and early access to innovative therapies. The region has a strong concentration of biotechnology companies, clinical trials, and biomanufacturing facilities, enabling early launches of novel antibodies and peptide hormones.
Key trends include rising adoption of GLP-1 therapies for obesity, increased use of subcutaneous antibody formulations, and broader biosimilar uptake following patent expirations. Major manufacturers are also investing in domestic production to strengthen supply chain resilience. Although Medicare price negotiations and payer cost controls are expected to moderate pricing, robust innovation pipelines and the high prevalence of chronic diseases are likely to sustain North America's market leadership through 2033.
U.S. Bioengineered Protein Drugs Market Size
The U.S. bioengineered protein drugs market is estimated at about US$ 99 billion in 2026. The CDC reports adult obesity prevalence of around 40% and more than 38 million Americans living with diabetes, while the American Cancer Society estimates about 2 million new cancer cases annually. These patient populations support demand for immunotherapies, insulins, and GLP-1 therapies. The FDA's role in biologics approvals and investments by companies such as Eli Lilly and Company and Amgen Inc. in U.S. manufacturing further strengthen the market.
Although Inflation Reduction Act price negotiations and biosimilar competition are expected to put pressure on prices, label expansions and new product launches are likely to support the country's position as the world's largest market. Growth in specialty pharmacies and home infusion services is also improving patient access.
Europe Bioengineered Protein Drugs Market Trends and Insights
Europe is projected to account for around 27% of the bioengineered protein drugs market in 2026, supported by broad healthcare coverage, established biopharmaceutical research clusters, and centralized marketing authorization through the European Medicines Agency (EMA). The region has a mature biosimilar market, with more than 100 biosimilars authorized, supporting treatment affordability and patient access while intensifying price competition for originator products. Key trends include rising demand for oncology and immunology biologics, the gradual integration of obesity medicines into public healthcare budgets, and continued investment in regional biomanufacturing.
Proposed reforms to EU pharmaceutical legislation, including changes to regulatory data protection periods, are expected to influence product launch strategies and competition between originator and biosimilar developers. Rising cancer incidence among ageing populations further supports long-term demand.
Germany Bioengineered Protein Drugs Market Size
Germany's bioengineered protein drugs market is estimated at about US$ 18 billion in 2026. Statutory health insurance covers nearly 90% of residents, supporting access to biologics prescribed for cancer, autoimmune diseases, and diabetes. The German Diabetes Society (DDG) estimates that more than eight million people in Germany live with diabetes. The AMNOG benefit assessment process, managed by the Federal Joint Committee (G-BA), influences the pricing of new biologics, while policies encouraging biosimilar adoption help contain treatment costs.
Germany's established biotechnology base, including major manufacturing operations associated with Roche, Sanofi, and Boehringer Ingelheim, further supports market development. A strong network of university hospitals and oncology centers also facilitates the adoption of innovative antibodies and participation in multinational clinical trials, sustaining demand for advanced protein therapies through 2033.
U.K. Bioengineered Protein Drugs Market Size
The U.K. bioengineered protein drugs market is estimated at US$ 10 billion in 2026. NHS England has been an early adopter of biosimilar switching, with savings from adalimumab biosimilars helping release healthcare budgets for newer therapies. Following the National Institute for Health and Care Excellence (NICE) recommendation of tirzepatide for obesity, the NHS began a phased rollout in 2025, with plans to reach around 220,000 people over three years.
Strong life sciences research, supported by the Medicines and Healthcare products Regulatory Agency (MHRA) and leading universities, continues to attract biologics investment and clinical trials. The government's Life Sciences Vision also aims to strengthen domestic research and manufacturing while improving patient access to innovative medicines across the NHS.
France Bioengineered Protein Drugs Market Size
France's bioengineered protein drugs market is projected to reach US$ 11 billion in 2026. Assurance Maladie provides full reimbursement for eligible treatment of long-term conditions such as cancer and diabetes, supporting access to high-cost biologics. The government's Innovation Santé 2030 plan, backed by around €7.5 billion, aims to strengthen France's position in health innovation and biomanufacturing. Sanofi S.A., headquartered in Paris, operates major biologics production facilities in France and continues to invest in flexible manufacturing capacity.
France's early access program also enables eligible patients to receive promising therapies before full reimbursement, supporting the uptake of new antibodies and peptide hormones. The French National Cancer Institute (INCa) estimated more than 430,000 new cancer cases in 2023, reinforcing long-term demand for oncology biologics.
Asia Pacific Bioengineered Protein Drugs Market Trends and Insights
Asia Pacific is the fastest-growing region, projected to expand at a CAGR of around 5.6% between 2026 and 2033. China is a major growth driver, with the International Diabetes Federation estimating around 148 million adults with diabetes and the National Medical Products Administration (NMPA) approving a growing number of domestically developed antibodies. Inclusion of biologics in China's National Reimbursement Drug List (NRDL) has expanded patient access, although volume-based procurement has increased price competition.
Across the region, key trends include the expansion of biosimilar manufacturing in South Korea and India, broader healthcare coverage, and increased out-licensing of Chinese bispecific antibodies and antibody-drug conjugates to global pharmaceutical companies. These developments strengthen Asia Pacific's role in biologics innovation and manufacturing. Ageing populations in Japan, South Korea, and China further support demand for cancer, autoimmune, and metabolic therapies.
India Bioengineered Protein Drugs Market Size
India's bioengineered protein drugs market is estimated at US$ 6 billion in 2026. The International Diabetes Federation estimates that around 90 million adults in India live with diabetes, supporting demand for insulins and GLP-1 therapies. India is also a major biosimilar producer, with companies such as Biocon Biologics, Dr. Reddy's Laboratories, and Intas Pharmaceuticals supplying affordable antibodies and insulins to domestic and international markets.
Government initiatives such as Ayushman Bharat PM-JAY and the Production Linked Incentive (PLI) scheme for pharmaceuticals support healthcare access and local manufacturing capacity. The Indian Council of Medical Research (ICMR) estimated around 1.46 million cancer cases in 2022, increasing the need for oncology biologics. Lower-cost biosimilars of trastuzumab, bevacizumab, and rituximab are also expanding treatment access across public and private hospitals.
Japan Bioengineered Protein Drugs Market Size
Japan's bioengineered protein drugs market is estimated at about US$ 18 billion in 2026. The Ministry of Internal Affairs and Communications reports that around 29% of the population is aged 65 years or older, supporting demand for therapies targeting cancer, autoimmune diseases, and metabolic conditions. Universal health insurance provides broad treatment coverage, while the Ministry of Health, Labour and Welfare (MHLW) aims for biosimilars to account for at least 80% of eligible molecules by FY2029.
Domestic innovators such as Chugai Pharmaceutical and Takeda continue to invest in antibody research, supporting market development despite periodic drug price revisions. Growing adoption of GLP-1 therapies and subcutaneous antibody formulations, alongside regulatory reviews by the Pharmaceuticals and Medical Devices Agency (PMDA), further supports the uptake of innovative protein drugs across hospitals and clinics.
Southeast Asia Bioengineered Protein Drugs Market Size
Southeast Asia's bioengineered protein drugs market is estimated at US$ 5 billion in 2026. Rising chronic disease prevalence is a key growth driver, with Malaysia's National Health and Morbidity Survey reporting diabetes prevalence of around 18% among adults. Expanding healthcare coverage through Indonesia's Jaminan Kesehatan Nasional (JKN) and Thailand's Universal Coverage Scheme is improving access to biologic therapies. Singapore is also strengthening its position as a regional biomanufacturing hub, supported by investments such as Sanofi's around EUR 400 million modular vaccine and biologics facility.
Increasing biosimilar availability, local partnerships, and streamlined regulatory pathways are expected to support market growth through 2033. Rising cancer incidence across Indonesia, Vietnam, and the Philippines, combined with a growing middle class and greater access to private healthcare, is further increasing demand for monoclonal antibodies and insulin analogs.
Competitive Landscape
The global bioengineered protein drugs market is moderately consolidated, with a group of large multinational companies, including Merck & Co., Inc., Roche, AbbVie Inc., Johnson & Johnson, Novo Nordisk A/S, Eli Lilly and Company, and Amgen Inc., generating a significant share of revenue through blockbuster antibodies, insulins, and peptide hormones. Leaders differentiate through large Phase III outcome trials, broad label expansion, subcutaneous and long-acting formulations, and proprietary engineering platforms for bispecifics and antibody-drug conjugates.
Companies are investing heavily in manufacturing capacity, highlighted by Novo Holdings' acquisition of Catalent in December 2024, to secure supply for fast-growing GLP-1 demand. Emerging business models include in-licensing novel molecules from Chinese biotechs, co-development alliances, and biosimilar portfolios run by companies such as Amgen and Sandoz. Lifecycle management strategies are also used to defend franchises ahead of patent expiries.
Key Industry Developments
- In April 2026, researchers at the University of Pennsylvania developed a bioengineered chewing gum containing the antiviral protein FRIL and antimicrobial peptide protegrin, which reduced HPV levels by up to 93% and reduced P. gingivalis and F. nucleatum bacteria to almost zero in oral cancer samples.
- In August 2026, UCLA bioengineer Jason Zhang developed generative AI-based approaches to design entirely new proteins that do not occur naturally, with potential applications in drug development, cancer research, and precision medicine.
Companies Covered in Bioengineered Protein Drugs Market
- AbbVie Inc.
- Amgen Inc.
- AstraZeneca PLC
- Eli Lilly and Company
- F. Hoffmann-La Roche Ltd.
- Johnson & Johnson
- Novartis AG
- Novo Nordisk A/S
- Sanofi S.A.
- Pfizer Inc.
- Merck & Co., Inc.
- Bristol Myers Squibb
- Biogen Inc.
- Regeneron Pharmaceuticals, Inc.
Frequently Asked Questions
The global bioengineered protein drugs market is expected to be valued at US$ 275.3 billion in 2026 and is projected to reach US$ 357.4 billion by 2033, growing at a CAGR of 3.8%.
Demand is driven by the rising burden of cancer, diabetes, obesity, and autoimmune disease. IARC recorded about 20 million new cancer cases in 2022, and the IDF estimates 589 million adults live with diabetes. Advances in antibody engineering and subcutaneous delivery are further widening treatment options.
North America is likely to lead the global market with an estimated 39% share in 2026, supported by high biologics spending, early adoption of innovative therapies, strong biotechnology and manufacturing infrastructure, and high prevalence of cancer, obesity, and diabetes.
Rising demand for peptide hormones for obesity and cardiometabolic disease and bispecific antibodies and antibody-drug conjugates in oncology create immense opportunities.
Key players in the market include AbbVie Inc., Amgen Inc., AstraZeneca PLC, Eli Lilly and Company, F. Hoffmann-La Roche Ltd., Johnson & Johnson, Novartis AG, Novo Nordisk A/S, Sanofi S.A., Pfizer Inc., Merck & Co., Inc., Bristol Myers Squibb, Biogen Inc., and Regeneron Pharmaceuticals, Inc.


