




- Animal Feed & Additives
- Chelated Iron Agricultural Micronutrient Market
Chelated Iron Agricultural Micronutrient Market Size, Share, and Growth Forecast 2026 - 2033
Chelated Iron Agricultural Micronutrient Market by Chelated Iron Type (EDTA-Fe, EDDHA-Fe, DTPA-Fe, IDHA-Fe, Others), Chelating Agent (Synthetic Ligands, Biodegradable), Form (Liquid, Powder, Granular), End-User (Commercial Agriculture, Horticulture, Floriculture, Smallholder Farming, Turf Management), and Regional Analysis, 2026-2033

Chelated Iron Agricultural Micronutrient Market Size and Trends Analysis
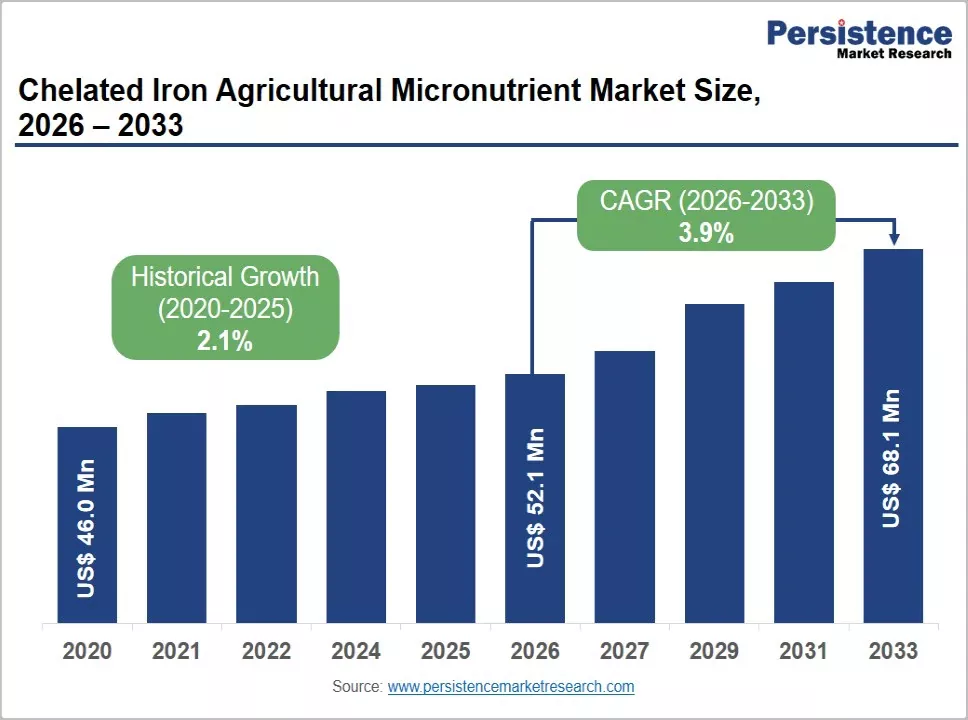
The global chelated iron agricultural micronutrient market size is expected to reach US$68.1 million by 2033, up from US$52.1 million in 2026, registering a CAGR of 3.9% during 2026–2033, driven by rising soil iron deficiency across intensive farming regions. Greater awareness of iron chlorosis and related yield losses is encouraging growers to use chelated iron for better nutrient uptake.
The adoption is also expanding with precision agriculture, soil testing, and targeted fertilization practices. These trends are increasing demand for soil-specific micronutrient solutions and supporting steady market expansion through 2033, especially across high-value crop production.
Key Industry Highlights:
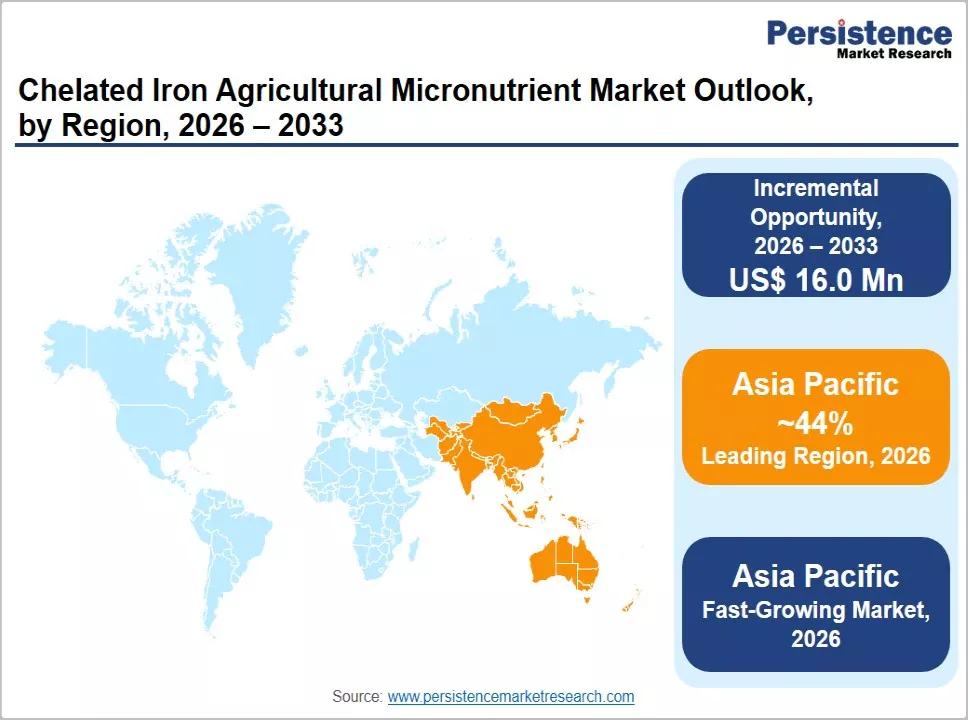
- Leading Region: Asia Pacific is expected to lead with a 44% share in 2026, driven by expanding commercial farming and horticultural cultivation across China and India supporting strong demand.
- Fastest-Growing Region: Asia Pacific is likely to be the fastest-growing region through 2033, supported by rising government-backed balanced fertilization programs and expanding horticultural exports.
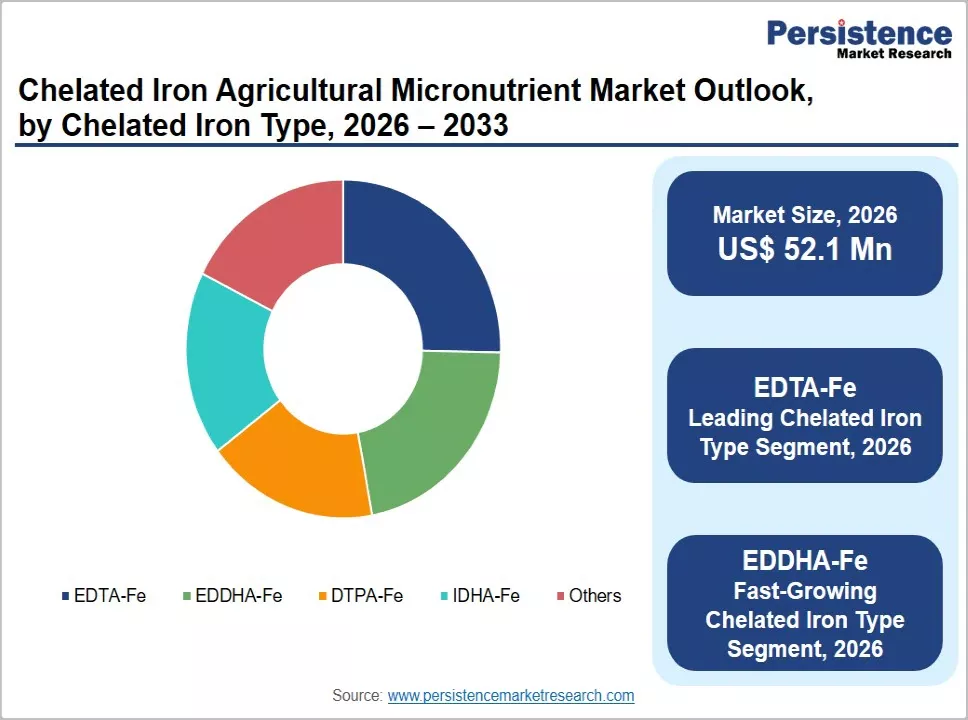
- Dominant Segment: EDTA-Fe is expected to dominate chelated iron type with a 36% share in 2026, favored for its affordability and proven effectiveness in moderately alkaline soils.
- Fastest-Growing Segment: EDDHA-Fe is expected to be the fastest-growing chelated iron type, driven by demand for reliable performance in highly alkaline and calcareous soil conditions.
- Key Market Opportunity: Rising demand for biodegradable chelating agents offers manufacturers a clear opportunity to align products with sustainability certifications and export market requirements.
Market Dynamics
Drivers - Rising Iron Chlorosis across High-Value Crop Production
Iron deficiency often appears as chlorosis in crops grown on alkaline and calcareous soils. It can reduce yields and crop quality in fruits, vegetables, and ornamental plants. Growers are adopting chelated iron because it remains stable and available to plant roots under high pH conditions. This supports better iron uptake than many conventional sources. Demand is rising among commercial farms producing iron-sensitive crops such as citrus, grapes, and soybeans.
Agricultural extension services and soil testing programs are helping farmers detect iron deficiency earlier and apply nutrients more precisely. Expansion of high-value fruit and vegetable cultivation in alkaline-soil regions, including parts of the Mediterranean and the Americas, is also supporting demand. As growers focus on consistent crop quality and marketable yields, chelated iron is becoming a regular input in integrated soil fertility programs. Its reliable performance supports wider use across intensive farming systems.
Expanding High-Value Horticulture and Fruit Cultivation Worldwide
Growing demand for fruits, vegetables, and ornamental plants is encouraging farmers to expand horticultural production, including in soils with low available iron. Chelated iron helps maintain plant health and produce quality, supporting its use across commercial farming systems. Demand is also increasing in regions expanding citrus, berry, and greenhouse vegetable production for domestic consumption and export markets.
Investment in greenhouse and protected cultivation is creating stronger demand for precise and soluble micronutrient inputs. Chelated iron can provide reliable nutrient availability under controlled production systems. Horticultural exporters are also facing stricter quality standards, encouraging growers to use dependable nutrient programs that reduce visible deficiency symptoms. As international fruit and vegetable trade expands, growers are intensifying production to meet market needs. This trend is expected to support wider use of chelated iron across high-value horticultural crops and protected farming operations.
Restraints - High Product Costs Compared with Conventional Iron Fertilizers
Chelated iron products generally cost more than conventional iron sulfate and other non-chelated iron sources. This price difference can limit adoption among cost-sensitive growers, especially smallholder farmers in developing regions. Many farmers continue using lower-cost alternatives, even when these products may provide weaker performance in alkaline soils. As a result, higher product prices can restrict market penetration across low-income farming areas and smaller agricultural operations.
Manufacturing chelated iron requires specialized chelating agents and controlled production processes, which increase costs compared with basic mineral fertilizers. Limited local production capacity in some developing regions can also add import, transport, and distribution expenses. These factors raise the final cost paid by farmers and distributors. Cost pressure remains a key barrier for farms with limited input budgets. Many low-margin farming operations therefore continue relying on conventional iron correction methods instead of adopting higher-priced chelated formulations.
Complex Application Requirements and Limited Farmer Awareness
Effective chelated iron application requires suitable soil testing, product selection, dosage, and application timing. These steps can be difficult for farmers without access to technical advice. Incorrect product selection or application may reduce nutrient effectiveness and increase input waste. Such challenges can discourage regular use of chelated micronutrients, particularly among small farms and less organized agricultural operations with limited access to agronomic support.
Limited availability of agricultural advisory services in developing farming regions further restricts knowledge of soil-specific micronutrient needs. Farmers may not fully understand when chelated iron is required or which formulation suits a particular crop and soil condition. Input dealers may also have limited technical training for product recommendations. Without stronger extension services, soil testing support, and farmer education, knowledge gaps can continue slowing adoption. This restraint is more relevant in smallholder and mixed-farming systems.
Opportunities - Precision Agriculture Enables More Targeted Chelated Iron Application
Growing adoption of precision agriculture is creating opportunities for targeted chelated iron application. Tools such as soil mapping, field sensors, and variable-rate technology can help farmers identify areas with iron deficiency. Farmers can then apply chelated iron only where required, improving input use and reducing unnecessary application. This approach supports better cost control and creates demand for micronutrient products suited to precision farming systems.
Agricultural technology providers are linking soil nutrient data with fertilizer recommendation platforms and digital farm management tools. These systems can help growers make better decisions on nutrient timing, dosage, and field placement. Rising investment in digital agriculture is supporting wider use of soil-specific nutrition programs across commercial farms. As precision farming expands, chelated iron suppliers can develop formulations and application systems that fit data-driven farm practices. This creates new opportunities for suppliers across large-scale and technology-focused agricultural operations.
Rising Demand for Biodegradable and Sustainable Chelating Agents
Growing concern about environmental impacts from synthetic chelating agents is creating opportunities for biodegradable chelated iron products. Farmers and agricultural buyers are showing greater interest in inputs that support sustainable farming practices and environmental goals. This shift is encouraging manufacturers to develop biodegradable formulations that maintain nutrient availability while reducing environmental concerns. Such products can support demand among farms targeting sustainability-focused production standards.
Regulatory attention toward chemical runoff and soil health is also increasing interest in lower-impact agricultural inputs. In some markets, commercial farms and exporters are seeking nutrient programs that align with sustainability requirements and buyer expectations. Consumer demand for sustainably produced fruits and vegetables may further encourage adoption of greener farm inputs. As sustainability standards become more relevant across major agricultural export markets, biodegradable chelating technologies can create new product opportunities. Manufacturers investing in these formulations may expand their presence in environmentally focused farming segments.
Category-wise Insights
Which Chelated Iron Type Leads the Market?
EDTA-Fe is set to lead the chelated iron type segment with a 36% share in 2026, supported by its wide availability, lower relative cost, and proven performance across moderately alkaline soils. Growers use EDTA-Fe in common crop nutrition programs because it provides a practical balance between effectiveness and affordability. Its established use across commercial agriculture and horticulture also supports steady demand. Broad product availability and farmer familiarity further strengthen its position across major agricultural markets.
EDDHA-Fe is likely to be the fastest-growing type through 2033, supported by its stronger stability in highly alkaline and calcareous soils. It performs better than EDTA-Fe under difficult soil conditions where iron availability is low. Rising cultivation of high-value fruits and vegetables on challenging soils is increasing demand for EDDHA-Fe. Growers seeking reliable iron correction are gradually adopting these formulations for demanding crop and soil conditions.
Chelating Agent Analysis
Synthetic ligands are expected to lead with a 68% share in 2026, supported by their long-established use, consistent performance, and lower production costs. Growers and distributors rely on these agents as they provide dependable iron availability across a wide range of agricultural soils. Established manufacturing capacity and broad farmer familiarity also support their leading position. Their use across commercial farming and horticulture continues to sustain demand.
Biodegradable chelating agents are likely to be the fastest-growing segment through 2033, driven by rising environmental awareness and stronger demand for sustainable agricultural inputs. Export markets and sustainability certifications are encouraging growers to consider lower-impact micronutrient products. Evolving environmental requirements are also supporting interest in biodegradable formulations. As buyers place greater focus on sustainable farming practices, adoption of biodegradable chelating agents is expected to increase across environmentally focused agricultural operations.
Form Analysis
Liquid chelated iron products are expected to lead the form segment with a 57% share in 2026, supported by their ease of application through irrigation, fertigation, and foliar spraying. Liquid products allow growers to control dosage and distribute nutrients more evenly across crops. Their compatibility with modern irrigation systems also supports wider use in commercial farming. Faster nutrient delivery further strengthens demand for liquid formulations across intensive agricultural operations.
Granular chelated iron is likely to be the fastest-growing form through 2033, supported by rising adoption in large-scale mechanized farming. Granular products can be applied using existing farm equipment and are easier to store, transport, and handle than many liquid alternatives. Uniform soil distribution also supports their use across extensive field areas. These practical benefits are encouraging commercial growers to adopt granular formulations for large-scale crop production and routine soil nutrient management.
Which End-User Segment Drives Chelated Iron Demand?
Commercial agriculture is likely to lead the end-user segment with a 61% share in 2026, supported by large-scale cultivation of iron-sensitive crops such as soybeans, citrus, and grapes. Commercial growers often follow structured fertility programs that include micronutrient applications to protect yield and crop quality. Strong distribution networks, technical support, and access to soil testing further support chelated iron adoption across large farming operations.
Horticulture is expected to be the fastest-growing end-user segment through 2033, driven by expanding production of fruits, vegetables, and ornamental plants that are sensitive to iron deficiency. Rising demand for high-value produce is encouraging growers to use more consistent micronutrient programs. Greenhouse and protected cultivation also support precise nutrient application. Greater focus on crop appearance, quality, and marketability is expected to drive faster chelated iron adoption across horticultural operations.
Regional Insights
North America Chelated Iron Market Trends and Insights
North America is expected to account for 26% of the global chelated iron market in 2026, supported by large-scale commercial agriculture and established horticultural production. Growers in regions with alkaline soils use chelated iron to improve crop yield and quality. Strong demand from citrus, fruit, and vegetable production supports steady product consumption. Commercial farms also benefit from structured fertility programs and access to agronomic services. Increasing adoption of soil testing and precision agriculture is enabling more targeted micronutrient application. As precision fertilization expands, North America is expected to maintain steady demand for chelated iron through 2033. Growing emphasis on crop quality and efficient nutrient use will further support regional adoption.
- U.S. Chelated Iron Market Size
The U.S. is likely to account for 84% of North America's chelated iron market in 2026, making it the region's largest national market. Extensive commercial agriculture, citrus production, vineyards, and fruit cultivation support strong demand for chelated iron products. Growers managing iron-sensitive crops on alkaline soils use these products to improve nutrient availability and protect crop quality. Established agricultural distribution networks also support product access across major farming regions. Growing adoption of precision fertilization, soil testing, and targeted nutrient application is creating additional demand. The U.S. market is expected to maintain steady growth through 2033 as commercial growers place greater focus on efficient soil-specific nutrition programs.
Europe Chelated Iron Market Trends and Insights
Europe is expected to hold a 22% share of the global chelated iron market in 2026, supported by strict agricultural input requirements and growing emphasis on sustainable farming. Growers are increasingly selecting micronutrient products that support environmental compliance and efficient nutrient management. Demand from fruit, vegetable, vineyard, and ornamental production remains strong across calcareous soil regions. Regulatory focus on chemical use and runoff is also encouraging greater attention to responsible fertilizer application. Commercial growers are adopting soil testing and targeted nutrition programs to improve input efficiency. Through 2033, Europe's chelated iron market is expected to grow steadily as sustainability requirements, crop quality goals, and soil-specific fertilization continue shaping agricultural input choices.
- Germany Chelated Iron Market Size
Germany is expected to account for 31% of Europe's chelated iron market in 2026, supported by its structured agricultural sector and strong focus on fertilizer quality and environmental compliance. Commercial growers increasingly use targeted nutrient programs to maintain crop health and manage soil deficiencies. Demand for reliable micronutrient products is also supported by horticultural production and quality-focused farming practices. Strong awareness of sustainable agriculture encourages growers to select products that support efficient nutrient use and responsible application. Germany's established agricultural infrastructure and technical support network further aid adoption. The market is expected to maintain steady growth through 2033 as sustainability standards and soil-specific nutrient management gain greater importance.
- U.K. Chelated Iron Market Size
The U.K. is likely to represent 21% of Europe's chelated iron market in 2026, supported by its established horticultural sector and increasing use of soil-specific nutrition programs. Fruit, vegetable, ornamental, and protected cultivation contribute to regional product demand. Growers are placing greater focus on crop quality and consistent produce standards, encouraging regular use of micronutrients where iron deficiency affects plant performance. Precision farming and improved soil testing are also helping growers identify nutrient requirements more accurately. These practices support targeted chelated iron application and better input management. The U.K. market is expected to grow steadily through 2033 as horticultural production and precision agriculture continue expanding across commercial farming operations.
- France Chelated Iron Market Size
France is expected to contribute 18% of Europe's chelated iron market in 2026, supported by substantial fruit, vineyard, and vegetable cultivation across regions with calcareous soils. Commercial growers use chelated iron to address iron availability issues and maintain crop quality. Demand is also supported by export-oriented horticulture, where consistent produce standards are important for market access. Growing interest in soil-specific fertility management is encouraging farmers to combine soil testing with targeted micronutrient applications. Sustainable farming practices are further shaping fertilizer choices across the agricultural sector. France's chelated iron market is expected to record steady growth through 2033 as growers focus on efficient nutrient use, crop quality, and responsible soil management.
Which Region Is Leading the Chelated Iron Market?
Asia Pacific is expected to lead the global chelated iron market with a 44% share in 2026 and is also the fastest-growing region through 2033. Expanding commercial farming and horticultural production across China and India are increasing demand for micronutrient solutions. Rising awareness of soil iron deficiencies is encouraging growers to adopt more targeted fertility programs. Government efforts supporting balanced fertilization are also improving awareness of micronutrient management. Growth in fruit, vegetable, and export-oriented agriculture is creating additional demand across the region. Through 2033, Asia Pacific is expected to remain the primary demand center as commercial growers increase precision fertilization and focus more closely on crop quality and soil health.
- China Chelated Iron Market Size
China is likely to account for 52% of Asia Pacific's chelated iron market in 2026, supported by its large commercial farming base and expanding high-value fruit and vegetable cultivation. Growers increasingly use micronutrient products to address soil deficiencies and maintain consistent crop quality. Government efforts promoting balanced fertilization are also supporting greater awareness of micronutrient use across agricultural regions. Export-oriented horticulture is creating additional demand for reliable nutrient management as producers seek consistent produce standards. Precision agriculture and soil testing are gradually strengthening targeted fertilizer application. China's chelated iron market is expected to expand through 2033 as commercial farms increase focus on productivity, crop quality, and efficient soil nutrient management.
- India Chelated Iron Market Size
India is anticipated to hold 22% of Asia Pacific's chelated iron market in 2026, supported by its large horticultural sector and rising awareness of soil micronutrient deficiencies. Commercial growers are increasing the use of targeted fertilizers to improve crop productivity and quality. Government support for balanced fertilization is also encouraging wider attention to micronutrient management. Expanding fruit, vegetable, and export-oriented horticulture is creating additional demand for chelated iron products. Growing adoption of soil testing and precision farming is helping farmers identify nutrient deficiencies and apply inputs more efficiently. India's market is expected to grow through 2033 as horticultural production, commercial farming, and demand for higher-quality agricultural output continue expanding.
- Japan Chelated Iron Market Size
Japan is expected to represent 11% of Asia Pacific's chelated iron market in 2026, supported by its structured horticultural sector and strong focus on crop quality. Commercial growers use precise nutrient programs to maintain consistent produce standards and manage soil nutrient deficiencies. Demand is supported by fruit, vegetable, protected cultivation, and other high-value agricultural activities. Advanced farming practices and strong awareness of soil management encourage targeted micronutrient application. Growers are also placing greater emphasis on efficient fertilizer use and consistent crop performance. Japan's chelated iron market is expected to record steady growth through 2033 as precision agriculture, controlled cultivation, and quality-focused horticultural production continue supporting demand.
<
Competitive Landscape
The global chelated iron agricultural micronutrient market is moderately consolidated, with competition shaped by product performance, chelate stability, formulation expertise, and agronomic knowledge. Established manufacturers focus on developing products suited to different soil conditions and crop needs. Strong distributor relationships with commercial growers also support market access and customer retention across major agricultural regions.
Leading companies are investing in biodegradable chelating technology and formulations compatible with precision agriculture to meet growing sustainability needs. This supports established players with strong research and development capabilities. Smaller companies are finding opportunities through regional distribution networks and cost-focused products designed for smallholder farmers, rather than competing directly in premium chelated iron categories.
Key Industry Developments:
- In April 2025, Yara International expanded its specialty micronutrient portfolio to strengthen chelated iron supply for horticultural markets across Europe and Asia. The move supported growing demand for reliable iron nutrition solutions in high-value crops and strengthened its position in specialty agricultural inputs.
- In November 2024, Haifa Group introduced enhanced chelated iron formulations designed to improve stability under high pH soil conditions. The formulations aimed to support more reliable iron availability in alkaline soils, helping growers manage iron deficiencies across horticultural and commercial crop production.
- In July 2024, ICL Group advanced its specialty agriculture division through continued investment in sustainable micronutrient production technology. The initiative supported the development of lower-impact agricultural inputs while addressing growing demand for efficient and environmentally responsible nutrient solutions across commercial farming markets.
Companies Covered in Chelated Iron Agricultural Micronutrient Market
- Yara International
- BASF
- Haifa Group
- Nouryon
- ICL Group
- Syngenta
- Nutrien
- UPL
- Coromandel International
- Nufarm
- Valagro
- COMPO EXPERT
- Aries Agro
- BMS Micro-Nutrients
- Compass Minerals
Frequently Asked Questions
The global chelated iron agricultural micronutrient market is likely to be valued at US$52.1 Million in 2026, supported by rising soil iron deficiency management across commercial farming operations worldwide.
Rising incidence of iron chlorosis in high-value crops is the main demand driver, as growers seek reliable nutrient correction on alkaline and calcareous soils.
Asia Pacific is expected to lead the market with a 44% share in 2026, supported by expanding commercial farming and horticultural cultivation across China and India.
Rising demand for biodegradable chelating agents is the key opportunity, as growers and exporters seek sustainable inputs that meet environmental certification requirements.
Key players include Yara International ASA, Haifa Group, ICL Group Ltd., Nouryon, and BASF SE, competing through formulation expertise and distribution reach.


