




- Animal Feed & Additives
- Feed Acidulants Market
Feed Acidulants Market Size, Share, and Growth Forecast, 2026 - 2033
Feed Acidulants Market by Acid Type (Propionic Acid, Lactic Acid, Others), Form (Dry/Powder Acidulants, Liquid Acidulants, Others), Animal, Function and Regional Analysis for 2026 - 2033

Feed Acidulants Market Size and Trends Analysis
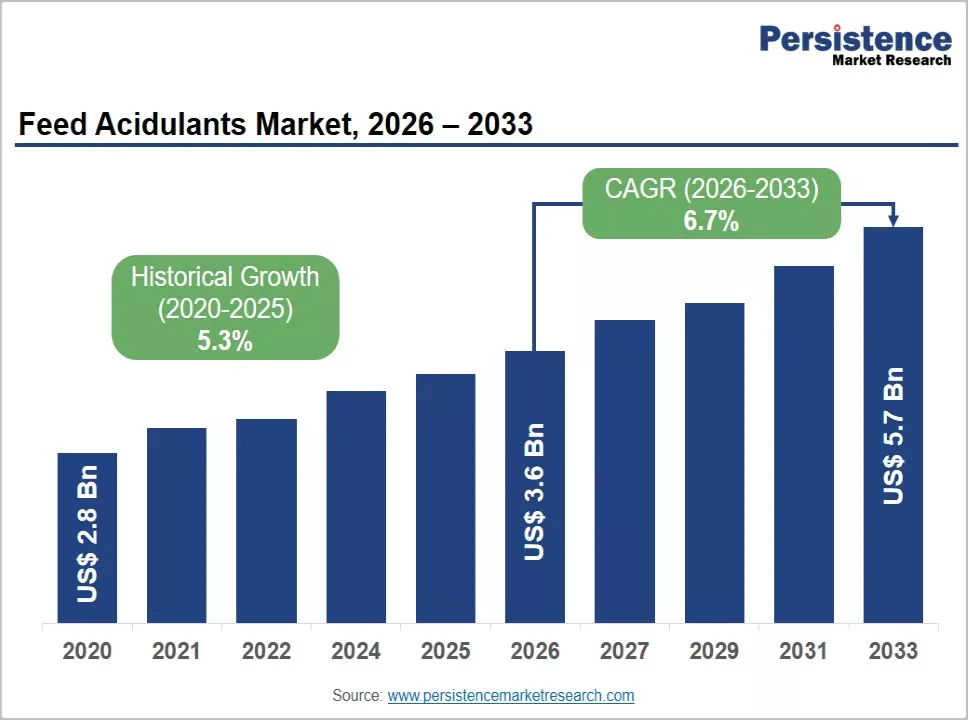
The global feed acidulants market size is likely to be valued at US$3.6 billion in 2026 and is expected to reach US$5.7 billion by 2033, growing at a CAGR of 6.7% between 2026 and 2033, driven by rising commercial feed production, increasing emphasis on feed hygiene, and the shift toward non-antibiotic approaches to gut health and pathogen management. Feed acidulants occupy an important position across feed preservation, pH management, pathogen control, and digestive support.
Propionic, formic, lactic, citric, fumaric, acetic, malic, and sorbic acids are used individually or in blends, while product development is increasingly shifting toward buffered, coated, encapsulated, and multi-acid formulations. Regulatory requirements are also influencing product development, with acidity regulators and preservatives subject to established feed-additive frameworks in major markets.
Key Industry Highlights:
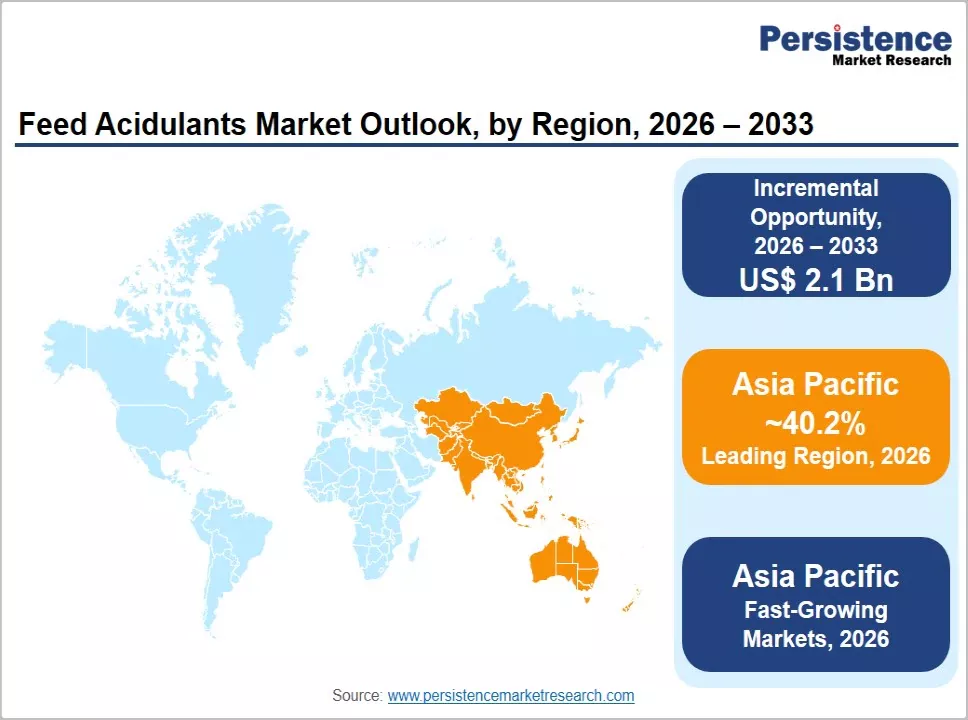
- Leading Region: Asia Pacific is projected to account for 40.2% of market revenue, supported by large commercial feed production and expanding poultry, livestock, and aquaculture industries.
- Fastest-growing Region: Asia Pacific, driven by increasing adoption of specialty feed additives, expanding aquaculture production, and investments in local feed manufacturing and animal nutrition infrastructure.
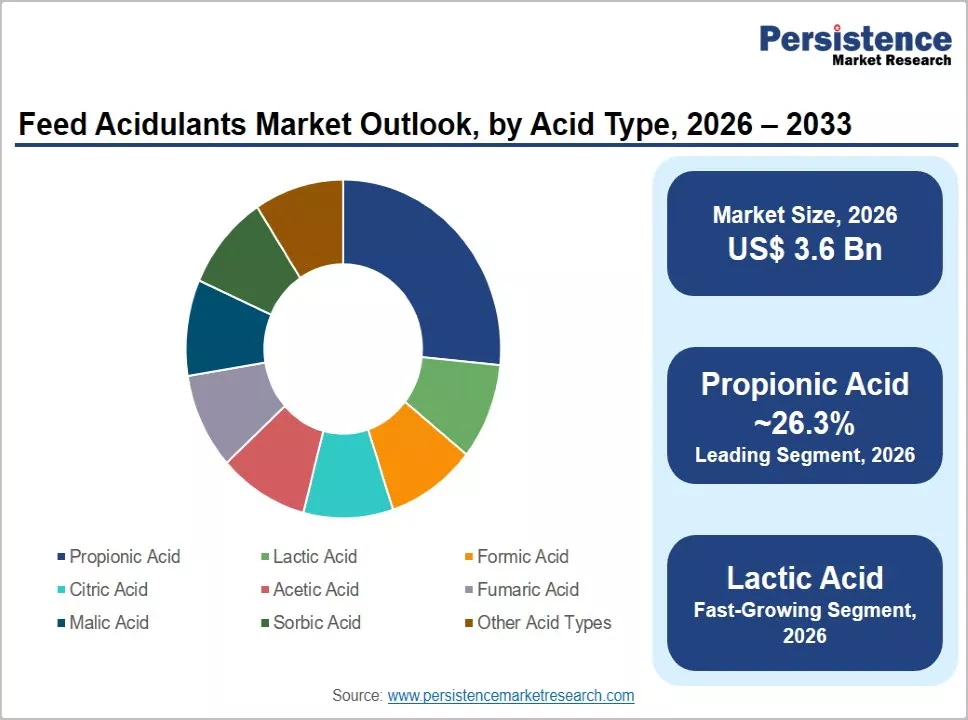
- Dominant Acid Type: Propionic acid, with an anticipated share of approximately 26.3%, supported by its established use in feed preservation and mold inhibition.
- Leading Form: Dry or powder acidulants, with an anticipated share of approximately 63.2%, supported by their compatibility with compound feed, storage convenience, and integration into automated feed-milling operations.
DRO Analysis
Driver - Expansion of Commercial Animal Protein Production and Feed Volumes
The growth of commercial livestock and aquaculture production is expanding the underlying demand for feed acidulants. Global feed production continued to increase in 2025, reflecting higher demand for professionally manufactured feed across poultry, livestock, and aquaculture. This expansion increases the need for ingredients that help maintain feed quality, control pH, limit mold growth, and support digestive health during storage and consumption.
The long-term growth of global protein production provides additional support. Rising meat, dairy, and egg production is encouraging greater use of compound feeds and professionally formulated nutrition programs. As livestock production becomes more intensive, feed manufacturers place greater emphasis on consistent formulation, shelf stability, microbial control, and nutrient utilization. These requirements are strengthening the role of acidulants as functional ingredients rather than simple feed preservatives.
Increasing Focus on Feed Hygiene and Reduced Antibiotic Use
The shift toward responsible antimicrobial use is creating additional demand for feed additives that support animal health without depending on antibiotic growth promoters. Acidulants can contribute to this approach by lowering feed pH, improving feed hygiene, limiting the growth of undesirable microorganisms, and supporting a favorable gastrointestinal environment.
Regulatory efforts to reduce antimicrobial use are reinforcing this trend, particularly in developed livestock markets. This environment is encouraging feed manufacturers and animal nutrition companies to develop solutions that combine acidification, preservation, pathogen management, and digestive support.
The commercial opportunity is consequently shifting toward multifunctional acidulant formulations. Products that provide several feed-health benefits within a single formulation can offer greater value than conventional single-acid products, particularly for intensive poultry, swine, and aquaculture production.
Restraint - Raw Material Costs and Product Handling Challenges
Feed acidulant manufacturers remain exposed to fluctuations in the cost of organic acids, energy, chemical feedstocks, transportation, and packaging. These cost pressures can affect product pricing and margins, particularly when feed manufacturers operate under strict cost controls.
Handling characteristics also influence product selection. Some organic acids are corrosive, have strong odors, or require specialized storage and dosing systems. These characteristics can increase handling requirements for feed mills and encourage customers to consider buffered, coated, or blended formulations that are easier to manage.
Regulatory Requirements and Product Qualification
Regulatory requirements can increase the time and investment required to commercialize feed acidulants. Products may need to demonstrate safety, efficacy, stability, and suitability for specific animal species and applications before entering regulated markets.
Requirements are particularly relevant for new acid combinations, targeted-delivery systems, and products making specific animal-health or performance claims. Manufacturers therefore need scientific data and regulatory expertise alongside formulation capabilities. These requirements can raise development costs and create barriers for smaller suppliers seeking to introduce differentiated products.
Opportunities - Growth of Encapsulated and Targeted-Delivery Formulations
Product innovation is moving the market beyond conventional free organic acids. Buffered, coated, encapsulated, and multi-acid formulations are gaining attention because they can improve handling, reduce corrosiveness, enhance stability during feed processing, and provide more controlled release within the digestive tract.
Encapsulation is particularly relevant where manufacturers want an acidulant to remain stable during feed production and reach a specific part of the gastrointestinal system. Buffered products can also improve ease of use while maintaining the desired acidification effect.
This creates opportunities for suppliers to compete through formulation performance rather than acid volume alone. Factors such as dose efficiency, pelleting stability, controlled release, reduced odor, compatibility with automated dosing systems, and species-specific performance can increasingly influence purchasing decisions.
Expansion of Aquaculture and Asian Feed Production
Aquaculture is emerging as an important application area for feed acidulants because intensive production systems require close control of feed quality, microbial conditions, digestion, and nutrient utilization. Global aquaculture production has continued to expand, particularly across Asia, where commercial farming of shrimp, fish, and other aquatic species is becoming increasingly sophisticated.
Asia Pacific provides a particularly important opportunity because of its large livestock and aquaculture industries and its expanding commercial feed manufacturing base. China and India are among the region's major feed-producing markets, while Southeast Asian countries are important centers for poultry and aquaculture production. Species-specific formulations, microbial management solutions, feed preservation systems, and products designed for intensive aquaculture operations can help address the increasingly specialized requirements of Asian producers.
Local manufacturing, regional distribution networks, and technical support are also becoming more important as feed production becomes increasingly industrialized. Suppliers that can provide consistent product quality together with application expertise can strengthen their position across rapidly expanding poultry, livestock, and aquaculture markets.
Category-wise Analysis
Acid Type Insights
Propionic acid is the leading acid type, with an anticipated market share of 26.3% in 2026. Its position is supported by established use as a preservative and mold inhibitor in compound feed, feed ingredients, and stored feed materials. For example, propionic acid-based products are widely used to control mold development and extend the storage stability of poultry and livestock feed. Its demand is closely linked to the need to reduce feed deterioration and nutrient losses during storage and distribution.
Lactic acid is the fastest-growing acid type, supported by increasing interest in pH control and microbial management. Lactic acid is used in feed applications where acidification and digestive support are important, while formic acid remains widely used for feed hygiene and bacterial control. Citric acid contributes to acidification and mineral utilization, while fumaric, malic, acetic, and sorbic acids provide additional formulation options. Suppliers are increasingly combining acids, such as formic and propionic acid blends, to provide broader preservation and microbial-control performance across poultry, swine, and aquaculture applications.
Form Insights
Dry or powder acidulants are the leading form, with an anticipated market share of 63.2%. Their dominance reflects compatibility with dry compound feed, convenient transportation and storage, and easy incorporation into premixes and finished feed. Powdered acidulant blends are particularly suitable for large poultry and swine feed mills using automated dosing and mixing systems.
Liquid acidulants are the fastest-growing form, supported by flexible dosing and applications in liquid feed and automated processing systems. Liquid organic acid products are used across poultry, swine, ruminant, and aquaculture operations where rapid and uniform application is required.
At the same time, suppliers are addressing the handling challenges of free acids through buffered and encapsulated formulations. For example, buffered propionic-formic acid blends can improve handling and reduce corrosiveness, while coated products can improve stability during pelleting and support more targeted gastrointestinal release. Premixed multi-acid formulations further simplify feed manufacturing while allowing suppliers to differentiate through application performance.
Regional Insights
North America Feed Acidulants Market Trends
North America is a mature feed acidulants market supported by large-scale poultry, swine, dairy, beef, and aquaculture production. Regional feed production reached approximately 288.6 million metric tons in 2025, with the U.S. accounting for most of the volume. Demand is increasingly centered on feed hygiene, pathogen control, precision nutrition, and multifunctional acidifier formulations.
U.S. Feed Acidulants Market Trends
The U.S. remains the region's primary market because of its extensive commercial feed infrastructure and concentration of integrated livestock producers and feed manufacturers. Acidulants are used for feed preservation, mold control, pH management, and microbial risk reduction. Perstorp's ProPhorce™ portfolio, including buffered formic acid and multi-acid solutions, illustrates the regional shift toward products that combine acidification with safer handling and bacterial control.
Industry consolidation is also influencing the market. In September 2025, ADM and Alltech announced a North American animal feed joint venture, combining Alltech's Hubbard Feeds and Masterfeeds businesses with ADM's U.S. feed mills. The transaction brings together 17 U.S. and 15 Canadian feed mills from Alltech and 11 U.S. mills from ADM, strengthening manufacturing scale and distribution capabilities. This type of consolidation can increase demand for standardized, scalable feed-additive solutions across larger production networks.
Canada Feed Acidulants Market Trends
Canada represents a significant market supported by commercial poultry, swine, dairy, and livestock production. Its integration with the broader North American feed industry also makes it an important market for suppliers operating across the region. The ADM-Alltech transaction further strengthens this integration by combining Masterfeeds' Canadian operations with a broader North American feed platform. Demand is increasingly shifting toward acidifier systems that provide measurable feed hygiene and animal-performance benefits while fitting automated feed manufacturing processes.
Europe Feed Acidulants Market Trends
Europe remains an important market because of its established compound-feed industry and stringent feed-safety framework. EU industrial compound-feed production was forecast at approximately 147.5 million tonnes in 2025, with poultry, pig, and cattle feed representing the principal applications.
Germany Feed Acidulants Market Trends
Germany has a highly developed livestock and feed manufacturing sector, creating demand for technically validated acidifiers and specialty feed additives. Regulatory compliance and documented efficacy are particularly important. Companies such as Perstorp are responding with buffered and multi-acid products such as ProPhorce™ AC 600, which combines formic acid with sodium formate to reduce corrosiveness while supporting bacterial control.
Spain Feed Acidulants Market Trends
Spain is another important European feed market, particularly because of its large pig and poultry industries. The scale of intensive livestock production supports demand for preservation and microbial-management products. Increasing emphasis on reducing antimicrobial use is also encouraging suppliers to develop multifunctional acidifier systems that combine feed preservation, pathogen management, and digestive support rather than relying on single-purpose acids.
Asia Pacific Feed Acidulants Market Trends
Asia Pacific is the leading regional market, accounting for approximately 40.2% of global revenue, and is also the fastest-growing region. Its position reflects large-scale feed manufacturing, expanding poultry and livestock production, and rapid aquaculture development.
China Feed Acidulants Market Trends
China has the region's largest feed manufacturing base and a highly integrated livestock industry. Large feed volumes create substantial demand for cost-efficient preservation, acidification, and microbial-control solutions. The market is increasingly moving toward standardized specialty formulations as large producers adopt more sophisticated feed-management systems.
India Feed Acidulants Market Trends
India is becoming an important growth market as poultry, dairy, and aquaculture production expand simultaneously. A major development came in February 2026, when Cargill opened a INR 300-crore dairy feed plant in Punjab with annual capacity of 400,000 metric tons. Products manufactured at the facility are marketed under the Provimi and Purina brands, expanding access to formulated dairy nutrition at scale.
In August 2025, dsm-firmenich opened its first feed-additive plant in India, a 11,200-square-meter facility in Jadcherla producing Mycofix® solutions for mycotoxin management. The investment strengthens local manufacturing and regional supply capabilities across Asia Pacific. Together, these developments demonstrate the region's shift toward localized production, larger commercial feed systems, and increasingly specialized feed-additive solutions.
Competitive Landscape
The global feed acidulants market remains moderately concentrated but competitive, with multinational chemical and animal nutrition companies operating alongside specialist feed additive manufacturers and regional suppliers. Leading companies benefit from established organic acid production capabilities, regulatory expertise, extensive distribution networks, and relationships with integrated feed manufacturers. Smaller and specialized suppliers compete through formulation flexibility, regional customization, encapsulation, microencapsulation, and species-specific technical support.
Leading suppliers are combining organic acid manufacturing, formulation science, regulatory capabilities, local production, and technical services. Product differentiation is shifting toward buffered, encapsulated, esterified, and multi-acid formulations. Geographic expansion, feed-mill partnerships, and integration with gut-health, mycotoxin, enzyme, and phytogenic portfolios are becoming increasingly important.
Key Industry Developments
- In February 2026, Cargill opened a INR 300-crore dairy feed plant in Wazirabad, Punjab, with annual production capacity of 400,000 tons.
- In February 2026, dsm-firmenich agreed to sell its Animal Nutrition & Health business to CVC Capital Partners for an enterprise value of approximately €2.2 billion, subject to regulatory and other closing conditions.
Companies Covered in Feed Acidulants Market
- BASF SE
- Cargill, Incorporated
- dsm-firmenich AG
- Kemin Industries, Inc.
- Perstorp Holding AB
- Yara International ASA
- Novus International, Inc.
- Corbion N.V.
- Adisseo
- Nutreco N.V.
- Impextraco NV
- ADDCON GmbH
- Anpario plc
- JEFO Nutrition Inc.
- EW Nutrition GmbH
- Alltech, Inc.
Frequently Asked Questions
The global feed acidulants market is expected to be valued at approximately US$3.6 billion in 2026.
The feed acidulants market is expected to reach approximately US$5.7 billion by 2033.
Key trends include growing adoption of non-antibiotic feed-health solutions, multifunctional acid blends, buffered and encapsulated formulations, targeted delivery technologies, and species-specific products. Increasing commercial feed production and aquaculture expansion are also supporting demand.
Propionic acid is the leading acid type, with an anticipated share of approximately 26.3%, while dry or powder acidulants lead by form with an anticipated share of 63.2%.
The market is projected to grow at a CAGR of 6.7% from 2026 to 2033.
Major players include BASF SE, Cargill, dsm-firmenich, Kemin Industries, and Perstorp Group.


