




- Specialty & Fine Chemicals
- Hydrogenation Catalyst Market
Hydrogenation Catalyst Market Size, Share, and Growth Forecast, 2026 - 2033
Hydrogenation Catalyst Market by Catalyst Type (Heterogeneous Catalysts, Homogeneous Catalysts, Others), Active Metal (Nickel-Based Catalysts, Cobalt-Molybdenum Catalysts, Others), Application, and Regional Analysis for 2026 - 2033

Hydrogenation Catalyst Market Size and Trends Analysis
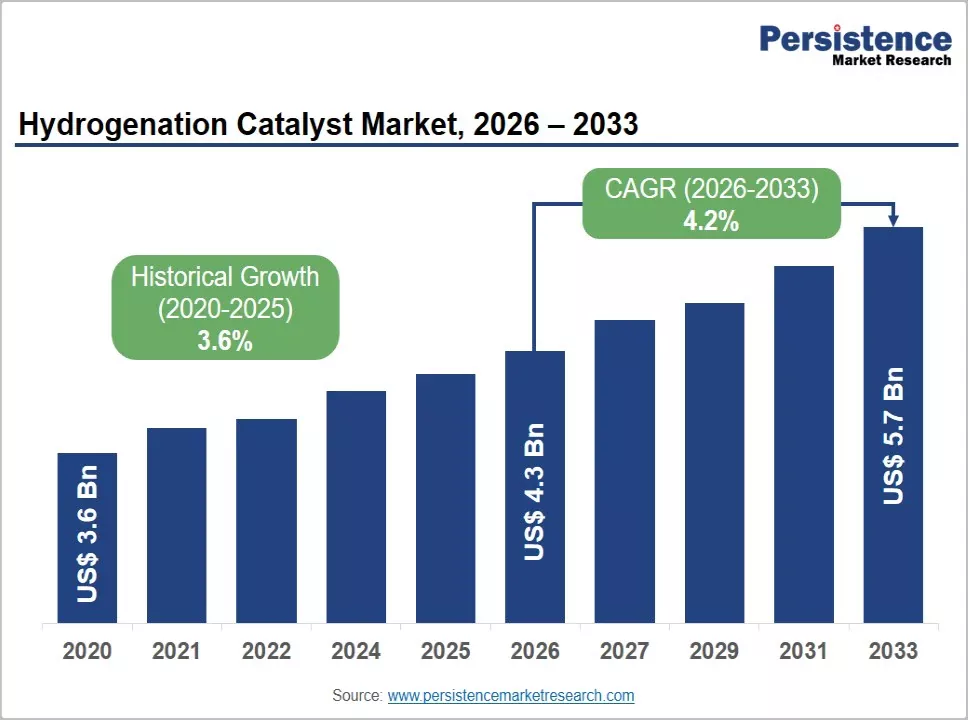
The global hydrogenation catalyst market size is likely to be valued at US$4.3 billion in 2026 and is expected to reach US$5.7 billion by 2033, growing at a CAGR of 4.2% during the forecast period from 2026 to 2033, driven by sustained hydrogen consumption in petroleum refining and chemical processing, increasing demand for cleaner transportation fuels, expansion of renewable diesel and sustainable aviation fuel production, and greater use of selective hydrogenation in pharmaceutical and specialty chemical manufacturing.
Global hydrogen demand exceeded 100 Mt in 2025, with established industrial applications accounting for nearly all consumption. Asia Pacific remains the largest regional market, supported by refinery expansions, petrochemical production, and pharmaceutical manufacturing across China, India, Japan, and Southeast Asia.
Key Industry Highlights:
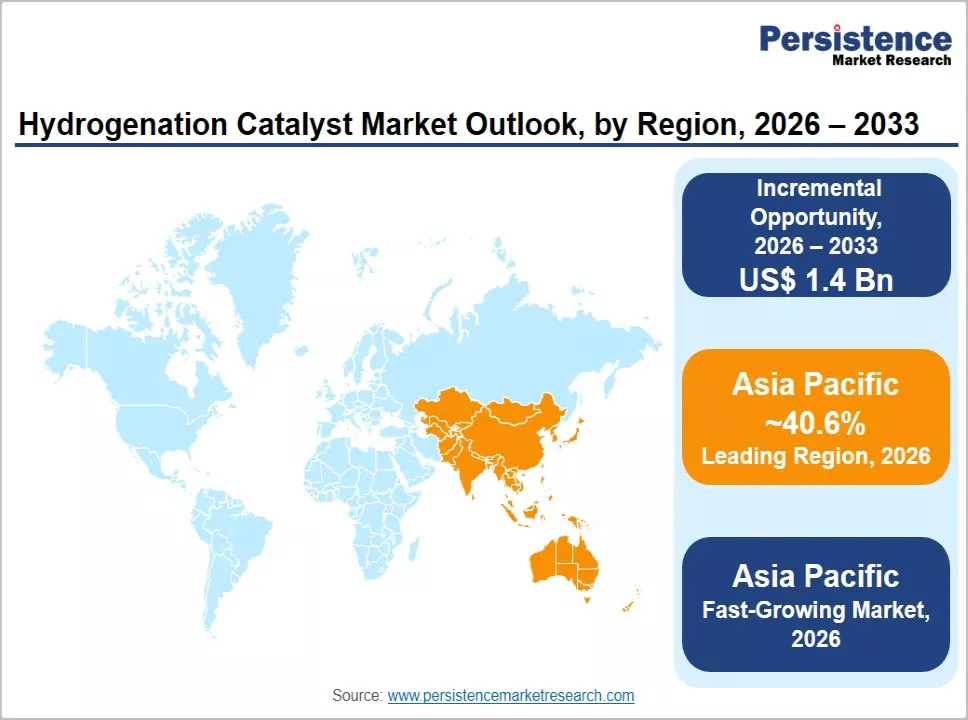
- Leading Region: Asia Pacific is projected to account for 40.6% of market share, supported by large refining, petrochemical, pharmaceutical, and chemical manufacturing industries.
- Fastest-growing Region: Asia Pacific is also anticipated to be the fastest-growing region, driven by refinery expansion, increasing petrochemical production, renewable-fuel investments, and growing hydrogen infrastructure across China, India, Japan, and Southeast Asia.
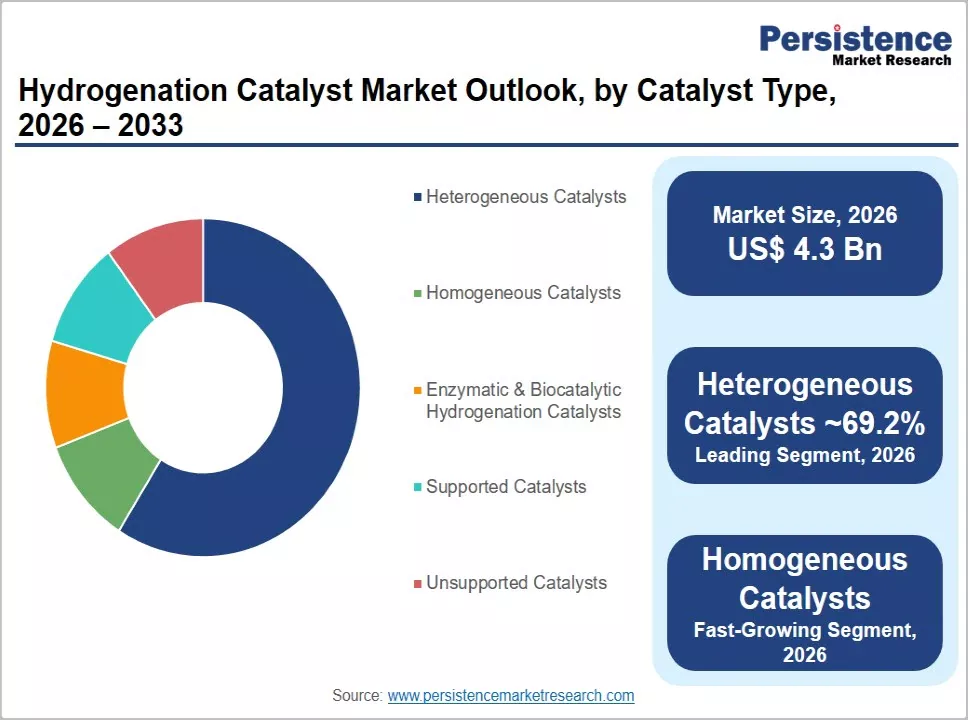
- Dominant Catalyst Type: Heterogeneous catalysts are anticipated to account for 69.2% of the market share in 2026, due to their extensive use in fixed-bed refinery reactors, hydrotreating, petrochemical purification, edible-oil processing, and industrial hydrogenation.
- Leading Active Metal: Nickel-based catalysts are anticipated to account for 31.5% of the market share in 2026, supported by their relatively low cost, broad availability, established technology, and extensive use in refining, chemicals, petrochemicals, and edible-oil hydrogenation.
DRO Analysis
Driver - Expansion of refinery hydroprocessing and renewable-fuel production
Hydrogenation and hydrotreating catalysts remain fundamental to refinery operations because sulfur, nitrogen, aromatics, olefins, and other contaminants must be removed or converted to meet fuel specifications. Global hydrogen demand exceeded 100 Mt in 2025, with refining and other established industrial applications accounting for almost all current consumption. Refinery capacity is also shifting toward Asia. Global refining capacity additions are expected to reach approximately 4.2 million barrels per day through 2030, partly offset by around 1.6 million barrels per day of closures, with China and India accounting for substantial additions. This supports recurring requirements for NiMo, CoMo, and other hydroprocessing catalysts.
Renewable diesel and other biofuel processes add another catalyst-intensive demand pool because hydrogenation and hydrodeoxygenation are required to convert oils, fats, and waste feedstocks into specification-grade fuels. U.S. renewable diesel and related biofuel production capacity reached approximately 324,000 barrels per day as of January 2026, strengthening demand for catalysts designed for feedstock flexibility, contaminant tolerance, and longer operating cycles.
Growing demand for selective hydrogenation across chemicals and pharmaceuticals
Hydrogenation catalysts are increasingly important in selective reduction, saturation, purification, intermediate production, and asymmetric synthesis across chemical and pharmaceutical manufacturing. Petrochemical production provides a large volume application base, particularly for monomer purification and removal of unsaturated impurities. Global petrochemical demand is expected to continue increasing as polymers and synthetic materials account for a growing portion of oil consumption.
Pharmaceutical manufacturing adds a higher-value application segment as hydrogenation reactions often require stringent control over selectivity, purity, conversion, and residual metals. India's pharmaceutical industry recorded turnover of approximately INR 471,898 crore in FY2024-25, representing annual growth of more than 13%. Government-supported production programs have also increased domestic manufacturing of critical pharmaceutical intermediates and active pharmaceutical ingredients. These developments support demand for palladium, platinum, ruthenium, nickel, homogeneous, and supported catalyst systems capable of meeting increasingly stringent product specifications.
Restraint - Precious-metal price volatility and stringent catalyst qualification requirements
The use of palladium, platinum, ruthenium, and rhodium creates exposure to raw-material price fluctuations and supply risks. Catalyst manufacturers and end-users therefore face pressure to reduce precious-metal loading while maintaining conversion and selectivity. This is encouraging the development of higher-dispersion catalysts, metal-recovery systems, and formulations that use lower quantities of expensive active metals.
Hydrogen economics also remain a structural constraint. Low-emissions hydrogen represented less than 1% of global hydrogen demand in 2025, despite strong year-over-year growth, reflecting the continuing cost gap between low-carbon hydrogen and conventional production. In addition, catalyst qualification can take considerable time in pharmaceutical, specialty chemical, and refinery applications as customers must establish process stability, product quality, catalyst life, and safety performance. These factors can lengthen sales cycles and increase development costs.
Opportunities - Renewable diesel, sustainable aviation fuel, and waste-feedstock upgrading
The transition toward renewable diesel, hydrotreated vegetable oil, sustainable aviation fuel, and waste-oil upgrading is creating new applications for hydrogenation and hydrodeoxygenation catalysts. U.S. renewable-fuel policy established applicable renewable-fuel volumes of approximately 26.81 billion gallons for 2026 and 27.02 billion gallons for 2027, providing a regulatory demand signal for renewable fuel production.
Renewable feedstocks can contain oxygenates, phosphorus, alkali metals, calcium, magnesium, and other contaminants that affect catalyst activity and operating life. This creates an opportunity for catalyst suppliers to develop formulations with higher contaminant tolerance, improved hydrodeoxygenation selectivity, lower hydrogen consumption, and longer cycle lengths. Suppliers that provide catalyst management, guard-bed technology, regeneration, and metals recovery can capture recurring revenue beyond the initial catalyst sale. The expansion of renewable-fuel capacity therefore supports both new catalyst installations and replacement demand.
Industrial decarbonization and low-carbon hydrogen development
Investment in low-emissions hydrogen is creating a second long-term opportunity for catalyst manufacturers. Capital expenditure on low-emissions hydrogen projects reached approximately US$7 billion in 2025, around twice the previous year's level, with investment expected to approach US$10 billion in 2026. More than half of committed investment remains connected to existing industrial hydrogen applications, particularly refining and chemicals.
The European Union requires renewable hydrogen to account for at least 42% of hydrogen used in industry by 2030, increasing to 60% by 2035. Japan has introduced a long-term support mechanism for low-carbon hydrogen, while India's National Green Hydrogen Mission targets 5 million metric tons per year of green hydrogen production capacity.
Category-wise Analysis
Catalyst Type Insights
Heterogeneous catalysts are anticipated to lead, accounting for 69.2% of the market share in 2026. Their position reflects extensive use in fixed-bed refinery reactors, hydroprocessing units, petrochemical purification, edible-oil processing, and industrial hydrogenation. Supported nickel, cobalt-molybdenum, nickel-molybdenum, palladium, and platinum formulations provide advantages in catalyst separation, continuous operation, thermal stability, mechanical strength, and regeneration. These characteristics are particularly important in large-scale refining, where catalysts operate continuously under high pressure and temperature.
For example, nickel and nickel-molybdenum catalysts are widely used in hydrotreating, while palladium-supported systems are used for selective hydrogenation in chemical manufacturing. Their compatibility with established fixed-bed reactor configurations also reduces the need for major process modifications.
Homogeneous catalysts are anticipated to be the fastest-growing segment, supported by rising demand from pharmaceuticals, specialty chemicals, advanced materials, and polymer-related applications. Their molecular-level control enables selective hydrogenation and asymmetric reactions where conversion alone is insufficient. For example, homogeneous catalysts are used in pharmaceutical intermediate synthesis where functional-group selectivity and stereochemical control are critical.
In May 2025, Umicore announced an expansion of homogeneous catalyst production at its Catoosa, Oklahoma facility, with production targeted for early 2027. Enzymatic and biocatalytic hydrogenation remains specialized, while supported and unsupported systems are selected according to feedstock, reactor design, operating conditions, recovery requirements, and lifecycle cost.
Active Metal Insights
Nickel-based catalysts are anticipated to lead, accounting for 31.5% of the market share in 2026. Nickel benefits from lower material costs than precious metals, broad availability, established processing technology, and extensive use across edible oils, chemicals, petrochemicals, and refining.
Examples include nickel catalysts used in vegetable-oil hydrogenation and nickel-molybdenum systems used for refinery hydrotreating, hydrodesulfurization, and hydrodenitrogenation. Cobalt-molybdenum catalysts also remain important in refinery applications where their activity profile suits the feedstock and operating conditions. Established supply chains and compatibility with fixed-bed and slurry processes support nickel's position, while catalyst developers increasingly focus on dispersion, deactivation resistance, regeneration, and contaminant tolerance.
Palladium-based catalysts are anticipated to be the fastest-growing precious-metal segment, driven by their high hydrogenation activity, strong selectivity, and ability to achieve high conversion at relatively low catalyst loadings. They are used in pharmaceuticals, specialty chemicals, petrochemicals, and selective hydrogenation processes. A recent example is the hydrogenation catalyst developed by Evonik and Westlake-Vinnolit for vinyl chloride monomer production, which achieves more than 98% acetylene conversion while using 20% less palladium than conventional technology. Platinum remains important in applications requiring high activity and stability, while ruthenium and rhodium serve specialized high-performance reactions.
Regional Insights
North America Hydrogenation Catalyst Market Trends
North America represents a major hydrogenation catalyst market, supported by the large refining base in the U.S., petrochemical infrastructure, renewable-fuel investments, and pharmaceutical manufacturing.
U.S. Hydrogenation Catalyst Market Trends
Renewable fuels are creating an additional catalyst demand stream. U.S. renewable diesel and related biofuel production capacity reached approximately 324,000 barrels per day in January 2026, increasing the requirement for catalysts used in hydrodeoxygenation, hydrotreating, and feedstock upgrading. In May 2025, Umicore announced an expansion of homogeneous catalyst production at its Catoosa, Oklahoma facility, with production targeted for early 2027. The investment is linked to long-term specialty-chemical partnerships and strengthens North American supply for pharmaceutical, polymer, and fine-chemical applications. In May 2026, BASF opened a new refinery-catalyst R&D center in Attapulgus, Georgia, colocated with its largest refinery catalyst production site, reinforcing the region’s focus on application-specific catalyst development and faster commercialization.
Canada Hydrogenation Catalyst Market Trends
Canada contributes through refining, chemicals, and growing low-carbon hydrogen activity. Federal and provincial decarbonization initiatives are encouraging refiners and chemical producers to evaluate lower-emission hydrogen and renewable feedstocks, creating opportunities for catalysts that maintain performance under changing feedstock conditions. Across North America, the US$8 billion Regional Clean Hydrogen Hubs program is also strengthening links between hydrogen production, refining, chemicals, transportation, and industrial users.
Europe Hydrogenation Catalyst Market Trends
Europe represents a mature but technologically advanced market supported by refining, chemicals, pharmaceuticals, specialty materials, and stringent environmental requirements. Germany accounted for approximately 4.4% of global hydrogenation catalyst sales in 2025, while the U.K. represented approximately 2.1%. European chemical manufacturing generated approximately €635 billion in turnover in 2025, sustaining demand for both bulk and highly selective hydrogenation systems.
Germany Hydrogenation Catalyst Market Trends
Germany remains a major catalyst technology and chemical manufacturing hub. European policy requires renewable hydrogen to account for at least 42% of industrial hydrogen consumption by 2030, rising to 60% by 2035. Clariant’s chromium-free HySat catalyst platform illustrates the shift toward catalyst technologies that address both performance and regulatory requirements by eliminating hazardous hexavalent chromium. Germany is also an important production base for Umicore’s Grubbs Catalyst technology, linking European specialty-chemical demand with advanced homogeneous catalysis.
Spain Hydrogenation Catalyst Market Trends
Spain is becoming increasingly important for renewable hydrogen integration with industrial operations. In September 2025, Repsol approved a 100 MW electrolyzer at Cartagena, with investment exceeding €300 million and planned production of approximately 15,000 tonnes of renewable hydrogen annually. In January 2026, Repsol announced a second 100 MW electrolyzer for its Petronor refinery, supported by €160 million in public funding. These projects demonstrate how renewable hydrogen is being integrated directly into refinery processes, supporting demand for catalysts capable of operating within lower-carbon hydrogen and feedstock pathways.
Asia Pacific Hydrogenation Catalyst Market Trends
Asia Pacific is the leading and fastest-growing regional market, accounting for approximately 40.6% of market share. China represents approximately 46% of regional demand, followed by India, Japan, South Korea, and Southeast Asian markets. The region benefits from large refining capacity, integrated chemical manufacturing, pharmaceutical production, edible-oil processing, and expanding hydrogen infrastructure.
China Hydrogenation Catalyst Market Trends
China’s large refining and petrochemical industries provide a substantial installed base for hydrogenation catalysts. The country accounted for approximately 65% of global installed electrolysis capacity and capacity that had reached final investment decision by 2025, while Chinese manufacturers represented nearly 60% of global electrolyzer manufacturing capacity. Shell Catalysts & Technologies has expanded its selective-hydrogenation catalyst business to 17 ethylene producers in China, with its C2 front-end catalyst selected by three of the country’s largest petrochemical plants. This demonstrates the region’s growing demand for high-performance catalysts in integrated petrochemical complexes.
India Hydrogenation Catalyst Market Trends
India represents another major growth market, with installed refinery capacity reaching approximately 267.116 million metric tons per year in April 2026. Refinery expansion, petrochemical integration, pharmaceutical manufacturing, and renewable-fuel projects are broadening catalyst requirements. Government support for low-emissions hydrogen is also creating new applications in refining and industrial processing. Southeast Asia adds further regional momentum, with hydrogen demand reaching approximately 4 Mt in 2024; Indonesia accounted for more than one-third, followed by Malaysia, Vietnam, and Singapore.
Competitive Landscape
The global hydrogenation catalyst market consists of several large global catalyst manufacturers alongside regional suppliers and application-specific specialists. Major participants include BASF, Honeywell UOP, Shell, Johnson Matthey, Clariant, Evonik, Topsoe, Albemarle, W. R. Grace, Axens, Umicore, Heraeus Precious Metals, JGC Catalysts and Chemicals, Reilly Industries, and Sinopec Catalyst. The market is relatively concentrated among major suppliers for large refinery accounts, while specialty chemicals and pharmaceutical applications have a more fragmented competitive structure.
Leading suppliers are focusing on catalyst innovation, lower precious-metal loading, longer operating cycles, feedstock flexibility, and integrated technical services. Companies are increasingly combining catalyst formulation with reactor optimization, regeneration, recycling, and process technology. Customer-specific formulations, long-term supply agreements, and collaborative catalyst development are also becoming more important competitive strategies.
Key Industry Developments:
- In January 2026, Evonik highlighted its jointly developed Noblyst® hydrogenation catalyst technology with Westlake-Vinnolit for vinyl chloride monomer production, using a palladium-on-silica catalyst for selective acetylene-to-ethylene hydrogenation.
- In March 2026, BASF started operations at the world’s first industrial-scale production plant for 3D-printed catalysts at its Ludwigshafen site in Germany, using its X3D® technology to manufacture catalysts with optimized geometries.
Companies Covered in Hydrogenation Catalyst Market
- BASF SE
- Johnson Matthey
- Evonik Industries AG
- Clariant AG
- Honeywell UOP
- Albemarle Corporation
- W. R. Grace & Co.
- Topsoe A/S
- Axens
- Shell Catalysts & Technologies
- Umicore
- Sinopec Catalyst Co., Ltd.
- JGC Catalysts and Chemicals Ltd.
- Nippon Ketjen Co., Ltd.
- Criterion Catalysts & Technologies
- Advanced Refining Technologies LLC
Frequently Asked Questions
The global hydrogenation catalyst market is expected to be valued at US$4.3 billion in 2026.
The market is projected to reach approximately US$5.7 billion by 2033.
Key trends include increasing adoption of high-activity supported catalysts, lower precious-metal loading, catalyst recycling and recovery, selective hydrogenation for pharmaceuticals and specialty chemicals, and catalyst development for renewable fuels and low-carbon hydrogen applications.
Heterogeneous catalysts are anticipated to remain the leading catalyst-type segment, accounting for approximately 69.2% of the market.
The hydrogenation catalyst market is projected to grow at a CAGR of 4.2% from 2026 to 2033.
Major players include BASF SE, Johnson Matthey, Honeywell UOP, Clariant AG, and Evonik Industries AG.


